Brighthouse Smartguard Plus
REGISTRATION STATEMENT FILE NO. 333-297104
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
REGISTRATION STATEMENT
UNDER THE SECURITIES ACT OF 1933
Pre-Effective Amendment No. 1
BRIGHTHOUSE LIFE INSURANCE COMPANY
(Exact name of registrant as specified in its charter)
(State or other jurisdiction of incorporation or organization)
(I.R.S. Employer Identification Number)
11225 North Community House Road, Charlotte, NC 28277
(980) 365-7100
(Address, including zip code, and telephone number, including area code,
of registrant’s principal executive offices)
Brighthouse Life Insurance Company
c/o The Corporation Trust Company
1209 Orange Street
Corporation Trust Center
Wilmington, DE 19801
(302) 658-7581
(Name, address, including zip code, and telephone number,
including area code, of agent for service)
Dodie C. Kent
Eversheds
Sutherland (US) LLP
The Grace Building, 40th Floor
1114 Avenue of the Americas
New York, NY
10036-7703
Approximate date of commencement of proposed sale to the public: As soon as practicable following the effectiveness of the registration statement.
If the only securities being registered on this Form are being offered pursuant to dividend
or interest reinvestment plans, please check the following box: ☐
If any of the securities being registered on this Form are to be offered on a delayed or continuous basis pursuant to Rule 415 under the Securities Act of 1933, other than offered only in connection with dividend or interest
reinvestment plans, check the following box: ☒
If
this Form is filed to register additional securities for an offering pursuant to Rule 462(b) under the Securities Act, please check the following box and list the Securities Act
registration statement number of the earlier effective registration statement for the same offering.
☐
If this Form is a post-effective amendment filed pursuant to Rule 462(c) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same
offering. ☐
If this Form is a registration statement pursuant to General Instruction
I.D. or a post-effective amendment thereto that shall become effective upon filing with the Commission pursuant to Rule 462(e) under the Securities Act, check the following box. ☐
If this Form is a post-effective amendment to a
registration statement filed pursuant to General Instruction I.D. filed to register additional securities or additional classes of securities pursuant to Rule 413(b) under the
Securities Act, check the following box. ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,”
“accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
Large accelerated filer ☐ |
|
| |
Smaller reporting company ☐ |
| |
Emerging growth company ☐ |
If an emerging growth company, indicate by check mark if the registrant has elected not to
use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 7(a)(2)(B) of the Securities Act. ☐
The Registrant hereby amends this registration statement on such date or dates as may be necessary to delay its effective date until the Registrant shall file a further amendment which specifically states that this registration statement shall
thereafter become effective in accordance with Section 8(a) of the Securities Act of 1933 or until the registration statement shall become effective on such date as the Commission, acting pursuant to Section 8(a), may determine.
BRIGHTHOUSE SMARTGUARD PLUS®
Brighthouse SmartGuard Plus® is a flexible premium adjustable life insurance policy (the
“Policy”) issued by Brighthouse Life Insurance Company (“BLIC”, “we”, “our” or “us”) that provides life insurance
protection.
BLIC is located at 11225 North Community House Road, Charlotte, NC 28277. The telephone number is (800)
882-1292. Brighthouse
Securities, LLC, 11225 North Community House Road, Charlotte, NC 28277, is the principal underwriter and distributor of the Policies.
The Risk Factors for this Policy appear on Page 18. Please read the prospectus carefully before investing and keep it for future reference. This prospectus includes important information, including a description of all material features, rights, and obligations of the Policy. BLIC’s obligations under the Policy are subject to our financial strength and claims-paying ability. Index-linked Policies are complex insurance and investment vehicles. Before you invest, be sure to ask your financial representative about the Policy’s features, benefits, risks, and charges, and whether the Policy is appropriate for you based upon your financial situation and objectives. The availability of investment options, Policy benefits, or other Policy
features described in this prospectus may vary depending on the state
through which your Policy is issued. Also, you should note that your Policy features and charges may vary depending on the date on
which you purchased your Policy. For more information about the particular features, charges, and options applicable to you, please contact your financial
representative or refer to Appendix F to this prospectus or your Policy for Policy variation
information.
The Policy provides Owners the opportunity to participate in
index-linked (through Indexed Accounts) and fixed interest investment returns. We are not obligated to offer any one particular Indexed Account, but after your Policy is
issued, there will always be one Indexed Account available with a minimum of 5% downside protection. If we were to offer only one Indexed Account, you would be limited to investing in that one Indexed Account. If that Indexed Account does not meet your investment objectives or financial goals, you could transfer to the Fixed Account (subject to applicable conditions described in the “TRANSFERS” section, including the requirement to remain invested in the Fixed Account until the next Policy Anniversary), Surrender your Policy and/or invest in another investment vehicle. If you Surrender your Policy, you might incur Surrender charges, taxes, tax penalties or other adjustments. If you invest in another investment vehicle, that investment may have different features, fees and risks than your Policy.
Each Indexed Account has a Segment Term of one year in length,
a Buffer Rate (10%, 15%, 20% or 100%) and a Cap Rate. For each Indexed Account, you select the Buffer Rate and the Index you want your investment performance to be based
on. We limit the amount you can earn on an Indexed Account through the Cap Rate.
The Cap Rates will not be less than the Guaranteed Minimum Cap Rate stated in your Policy, which will not be less than 3%.
The Policy also offers the option to receive Distribution Payments through the Guaranteed Distribution Rider (“GDR”), which is automatically included in the Policy at an additional cost. Each Distribution Payment cannot exceed a specified amount and a minimum amount of premium must be paid to avoid terminating the GDR. Distribution Payments are treated as loans and reduce the Cash Value and the death benefit amount. Such reductions could potentially deplete the Policy’s Cash Value and significantly reduce the death benefit. The GDR includes a Lifetime Lapse Prevention Benefit, and, if necessary, we will increase your Cash Value in order for the Distribution Payments to continue. In addition, the GDR guarantees a minimum death benefit amount ($10,000) upon the Insured’s death.
The Policy is a complex investment and involves risks,
including potential loss of principal. The Policy is not a short-term investment and is not appropriate for an investor who needs ready access to cash. There are risks associated with investing in Indexed Accounts. You may lose money, up to all or a significant
amount of any Net Premium allocations, as well as earnings from prior Indexed Account allocations. You should not buy this Policy if you are not willing to assume these
investment risks. Surrenders and loans, if taken from the Indexed Accounts before the end of a
Segment Term, will be based on an Interim Segment Value calculation. In extreme circumstances, you could lose all or a significant portion of the value of an Indexed Account if you Surrender or take a loan from the Indexed Account before the Segment Maturity Date.
Partial withdrawals are not permitted under the Policy.
If you are a new investor in the Policy, you may
cancel your Policy within 10 days of receiving it without paying fees or penalties. In some states, this cancellation period may be longer. If you cancel the Policy,
depending on state law, we refund either: (a) premiums paid, less any loan amount; or (b) the Policy’s Cash Value as of the date we receive the returned Policy,
plus any charges we
deducted, less the outstanding loan amounts plus accrued interest. You should review this prospectus or consult with your financial professional, for additional information
about the specific cancellation terms that apply.
Neither the Securities and Exchange Commission (the “SEC”) nor any state securities commission has
approved or disapproved these securities or the adequacy of this prospectus. Any representation to the contrary is a criminal offense. Insurance products, including this one, are not deposits of any bank and are not insured or guaranteed by the Federal Deposit Insurance Corporation (the “FDIC”) or any other government agency. You may lose money invested in the Policy.
The Policies may be distributed through
broker-dealers that have relationships with banks or other financial institutions or by employees of such banks. However, the Policies are not deposits or
obligations of, or guaranteed by such institutions or any Federal regulatory agency. Investment in the Policy involves investment risks, including possible loss of principal.
The principal underwriter of the Policy is
Brighthouse Securities, LLC. The offering of the Policy is intended to be continuous.
Prospectus dated November 2, 2026
SPECIAL TERMS
In this prospectus, the following capitalized terms have the indicated meanings:
Accrued Buffer Rate. The portion of the Buffer Rate that has accrued from the Segment Start Date to any day within the
Segment Term. This is the amount that we will absorb when calculating Interim Segment Value on any day prior to the Segment Maturity Date if Segment Index Performance is less than zero. The Accrued Buffer Rate is equal to the Buffer Rate multiplied by the number of days elapsed since the Segment Start Date, divided by the total number of days in the Segment Term. The Buffer Rate accrues during the Segment Term and only reaches full accrual on the last day of a Segment Term, which means the Accrued Buffer Rate is lower earlier in the Segment Term and will be reflected in the Interim Segment Value calculation.
Accrued Cap Rate. The portion of the Cap Rate that has accrued from the Segment Start Date to any day within the Segment Term. This is the maximum Segment Index Performance that may be applied in calculating the Interim Segment Value on any day prior to the Segment Maturity Date if Segment Index Performance is greater than zero. The Accrued Cap Rate is equal to the Cap Rate multiplied by the number of days elapsed since the Segment Start Date, divided by the total number of days in the Term. The Cap Rate accrues during the Segment Term and only reaches full accrual on the last day of a Segment Term, which means the Accrued Cap Rate is lower earlier in the Segment Term and will be reflected in the Interim Segment Value calculation.
Accrued Index Return. The amount added to the Segment Value to determine the Interim Segment Value. The Accrued Index
Return is equal to the current Segment Value (on the date of the Interim Segment Value calculation) multiplied by the Segment Performance Rate. The Accrued Index Return can be positive, zero or negative.
Administrative Office. The office, or any other office that we may designate for the purpose of administering the Policy, to which
Notices and requests must be sent, or as otherwise changed by notification from us.
Annual Deduction. An amount deducted from the Policy’s Cash Value on the Policy Start Date and on each Policy Anniversary, consisting of the Annual Administrative Charge, the Annual Indexed Account Charge, the Annual Cost of Insurance Charge, and the GDR charge, if applicable. A description of Annual Administrative Charge, the Annual Indexed Account Charge, the Annual Cost of Insurance Charge can be found in the “CHARGES” section, and a description of the GDR Charge can be found in the “GUARANTEED DISTRIBUTION RIDER” section.
Annual Lapse Prevention Premiums. The premiums that must be paid in order to keep the Lifetime Lapse Prevention Benefit in force.
Annual Lapse Prevention Premiums are calculated at issue and payable for 10 years. If not paid when due, the GDR will terminate. Payment of the Annual Lapse
Prevention Premiums will ensure that your Policy remains in force so that Policy Proceeds are payable upon the death of the Insured (see “Risk of
Lapse” under the “Risk Factors” section), provided the GDR is in force. Payment of the Annual Lapse Prevention Premiums do not increase the
Face Amount; however, premium payments may increase the death benefit. See “DEATH BENEFIT.”
Attained Age. The Attained Age is equal to the Issue Age plus the number of
completed Policy Years. This includes any period during which the Policy was lapsed.
BLIC (“we,” “us,” “our,” or the
“Company”). Brighthouse Life Insurance Company.
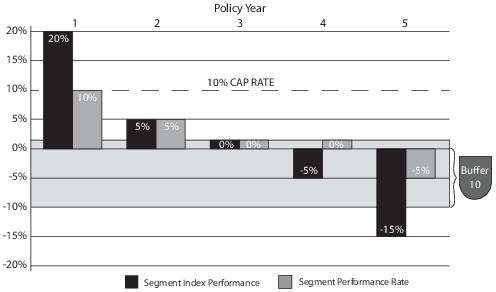
Buffer 10. The Policy provides downside protection through Buffer 10, which is a Buffer Rate where negative Segment Index Performance of up to 10% is absorbed by us at the Segment Maturity Date, which would leave you to absorb up to 90% of any remaining negative Segment Index Performance.
Buffer 15. The Policy offers downside protection through Buffer 15, which is a Buffer Rate where negative Segment Index Performance of up to 15% is absorbed by us at the Segment Maturity Date, which would leave you to absorb up to 85% of any negative Segment Index Performance.
Buffer 20. The Policy offers downside protection through Buffer 20, which is a Buffer Rate where negative Segment Index Performance of up to 20% is absorbed by us at the Segment Maturity Date, which would leave you to absorb up to 80% of any remaining negative Segment Index Performance.
Buffer 100. The Policy offers downside protection through Buffer 100, which is where 100% of negative Segment Index Performance is absorbed by us, which means you are 100% protected from any negative Segment Index Performance throughout the entire Segment Term.
Buffer
Rate. An Indexed Account Factor. The amount of negative Segment Index Performance from which we protect you at the Segment Maturity Date. Any negative Segment Index Performance beyond the Buffer Rate will reduce the Segment Value associated with the Indexed Account by any negative Segment Index performance in excess of the Buffer Rate. The Buffer Rate may vary among Indexed Accounts and is an annual rate. We currently offer the following Buffer Rates: Buffer 10, Buffer 15, Buffer 20, and Buffer 100.
Business Day. Our “business day” is generally any day the New York Stock Exchange (“NYSE”) is open for regular trading. For purposes of administrative requests and transactions, a Business Day ends at 4:00 PM Eastern Standard Time. If the SEC determines the existence of emergency conditions on any day, and consequently, the NYSE does not open, then that day is not a Business Day.
Cap Rate. An Indexed Account Factor. The maximum positive Segment Index Performance that may be credited at the Segment Maturity Date. The Cap Rate may vary among Indexed Accounts and is an annual rate. It is not a guaranteed rate of return.
Cash Surrender Value. The amount you receive if you Surrender the Policy. It is equal to the Policy’s Cash Value and any Annual Deduction refund reduced by any Surrender charge that would apply on Surrender and by any outstanding Policy Loan Balance.
Cash Value. Cash Value is equal to the total of the values in the Fixed Account, Holding Accounts, Indexed Accounts, and the
Loan Account.
Closing Value of the Index. The value of the Index as of the close of the NYSE, or any other relevant stock exchange. If the
Index is on an exchange other than the NYSE, or any other relevant stock exchange, we will use that exchange’s Closing Value. We will use consistent sources to obtain the Closing Value. If these sources are no longer available for specific indices, we will select an alternative published source for the Closing Value. If no Closing Value is published for a given day, we will use the Closing Value for the nearest prior day for which the Closing Value was published. In calculating the change in value of the Index, we use the Closing Value of the Index. We may also refer to this as the “Closing Value” in the prospectus.
Distribution Payment. Represents the amounts you receive under the GDR
beginning on the Distribution Start Date. Distribution Payments are loans, and you can change the amount of your Distribution Payment at any time up to the
Maximum Distribution Payment.
Distribution Payment Duration. The period of time we guarantee you will receive Distribution Payments. The available durations are 10-year,
20-year, and lifetime (up to Attained Age 121).
Distribution Payment Frequency. The
frequency of your Distribution Payments. The available frequencies are annual, semi-annual, quarterly, or monthly.
Distribution Start Date. The date you elect to start receiving Distribution Payments under
the GDR.
Excess Loan. An Excess Loan occurs when there is a loan outstanding, and the
Cash Value of the Policy, less any Surrender charge, is less than or equal to the outstanding loan amounts plus accrued interest. An Excess Loan will
terminate the Lifetime Lapse Prevention Benefit.
Exchange Act. Securities Exchange Act of 1934, as amended.
Face Amount. The dollar amount we use to calculate the death benefit. The minimum Face Amount is $50,000.
Fixed Account. An account that is part of our General Account and provides guarantees of principal and a fixed rate of return. We credit interest daily at an effective annual rate, no less than the Fixed Account Guaranteed Minimum Interest Rate, which is the minimum interest rate allowed by state law—see Appendix C. The actual Fixed Account Guaranteed Minimum Interest Rate for your Policy is shown on your Policy specification page and applies only to amounts in the Fixed Account.
General Account. Comprised of BLIC’s assets, other than assets in any separate accounts
it may maintain.
Good Order. A request or transaction generally is considered in “Good
Order” if it complies with our administrative procedures and the required information is complete and accurate. A request or transaction may be rejected
or delayed if not in Good Order. A complete description of “Good Order” can be found in the “REQUESTS AND ELECTIONS” section.
Guaranteed Distribution Rider (“GDR”). A rider that provides for
guaranteed Distribution Payments in the form of loans of the Policy’s Cash Value for a set amount of time and is automatically included with your Policy
on the date we issue your Policy at an additional charge. We may also refer to this as the “GDR” in the prospectus and the “Rider” in
the Guaranteed Distribution Rider attached to your Policy.
Guaranteed Minimum Distribution Payment. The minimum amount that we guarantee will be available to you as an annual Distribution
Payment; however, you may take less than the Guaranteed Minimum Distribution Payment when you start Distribution Payments.
Holding Accounts. A temporary account that holds Net Premium prior to being
transferred to the Indexed Account to which you intend to allocate on the next Segment Start Date, which is always on a Policy Anniversary. Each Holding
Account has its own Holding Account interest rate, which is a fixed interest rate, and interest is credited daily at an effective annual rate that we declare periodically.
Index (Indices). An Indexed Account Factor. The index to which Segment Index Performance for a selected Indexed Account is linked. We currently offer Indexed Accounts with indices based on the performance of securities. In the future we may offer Indexed Accounts based on other types of Indices. We may also add other indices for new Policies at our discretion.
Indexed Accounts. One or more Policy accounts, for which values will vary over
time, based, in part, on the change in value of an external Index. You may allocate Net Premiums and transfer unloaned Cash Value to one or more Indexed
Accounts. Each Indexed Account will have associated Indexed Account Factors and an associated Holding Account.
Indexed Account Cash Value. The Cash Value in an Indexed Account. On the
Segment Start Date and Segment Maturity Date, the Indexed Account Cash Value equals the Segment Value in that Indexed Account. On any other day, it equals the
Interim Segment Value in that Indexed Account.
Indexed Account Factors. The Indexed Account Factors consist of an Index, Segment Term, Holding Account interest rate, a
Buffer Rate, and a Cap Rate. For each Indexed Account, the Indexed Account Factors, except for the Holding Account interest rate, apply from the Segment Start Date to the Segment Maturity Date.
Insured. The person whose life is covered by the Policy.
Issue Age. The age of the Insured as of the Insured’s last birthday on the Policy Start Date.
Interim Segment Value.
The value we assign to each Indexed Account on any Business Day prior to the Segment Maturity Date. During the Transfer Period and for purposes of transfers only, the Interim Segment Value of each Segment is equal to the Segment Value at the Segment Maturity Date. For all other purposes during and after the Transfer Period, the Interim Segment Value of that Segment is equal to the current Segment Value adjusted for the Accrued Index Return. The Interim Segment Value is the amount we use to determine the Indexed Account Cash Value prior to the Segment Maturity Date. The Indexed Account Cash Value is part of the Cash Value, which determines how much is available for death benefits (including Policy Proceeds and an Acceleration of Death Benefit for Terminal Illness payment), loans (not including loans in connection with Distribution Payments under the GDR), transfers from Indexed Account Cash Value to the Fixed Account if you choose to start (or restart) Distribution Payments under the GDR, and Surrenders (including Surrenders in connection with the Free Look Period). An Acceleration of Death Benefit for Terminal Illness payment and a loan that is not a Distribution Payment will reduce the Interim Segment Value by the dollar amount of the transaction.
Lifetime Lapse Prevention Benefit. A benefit, offered through the GDR, that guarantees the Policy will not lapse if the
Policy’s unloaned Cash Value is insufficient to cover any Surrender charge and any Annual Deduction due on a monthly anniversary date, provided the GDR is in force, Annual Lapse Prevention Premiums are paid when due, and there is no Excess Loan.
Loan Account. The account to which Cash Value from the Indexed Accounts, Holding Account, and/ or Fixed Account is
transferred when a loan is taken, or unpaid interest is added to the loan.
Loan Interest. An amount of Interest that accrues daily based on the outstanding loan amounts plus accrued interest and is
due on each Policy Anniversary. Loan Interest is the interest we charge you for taking a loan.
Maximum Distribution Payment. Represents the maximum amount available to you
for each Distribution Payment if you were to start Distribution Payments that Policy Year. Starting in Policy Year 11, it is calculated at each Policy
Anniversary prior to the Distribution Start Date and is equal to the Policy’s Cash Value on that date multiplied by the Distribution Payment rate. If
you select an annual Distribution Payment Frequency, the Maximum Distribution Payment is an annual amount and is the maximum that you may receive as a Distribution Payment on the Distribution Start Date and on each Distribution Start Date anniversary. If you select a Distribution Payment Frequency other than annual (monthly, quarterly, or semi-annual), the Maximum Distribution Payment is not an annual amount but is the maximum amount you can receive for each Distribution Payment based on your selected frequency.
Net Premium. An amount equal to the premium minus the Percent of Premium Charge. The Net Premium is the portion of the
premium that will be applied to your Policy’s Cash Value.
Notice.
Any form of communication providing information we need, within a signed writing or other manner that we approve in advance. All Notices to us must be sent to our Administrative Office and received in Good Order. To be effective for a Business Day, a Notice must be received in Good Order prior to the end of that Business Day.
One-time Payment. After the Distribution Start Date, if you have received less than your cumulative Maximum Distribution Payments, you may choose to receive a One-time Payment amount that is separate from your scheduled Distribution Payments. You may only make this election once, provided your Distribution Payments have not been terminated.
Owner (“you”, “yours”). The person(s) entitled to the
ownership rights under the Policy. Subject to our administrative procedures, we may also permit ownership by a corporation (a type of non-natural person) or
certain other legal entities. If Joint Owners are named, all references to Owner shall mean Joint Owners.
Percent of Premium Charge. A charge imposed on each premium payment that
covers the sales charge, premium tax charge, and federal tax charge.
Planned Premium Payment.
The Planned Premium Payment is the premium payment schedule you choose to help meet
your future goals under the Policy. The Planned Premium Payment consists of a first-year premium amount and an amount for premium payments in subsequent Policy Years. It is subject to certain limits under the
Policy.
Policy Anniversary. An anniversary of the Policy Start Date.
Policy Deduction Method. Policy deductions are taken proportionally from each
Indexed Account and its associated Holding Account, considered together, and the Fixed Account. The proportional amounts are calculated based on the Cash
Values across these accounts. The sum of the values in an Indexed Account and its associated Holding Account is considered one proportion. The corresponding proportional amount is subtracted first from the Holding Account until it has been reduced to zero and then any remaining amount is subtracted from the associated Indexed Account.
Policy Loan Balance. An amount equal to the outstanding loan amounts plus accrued Loan Interest.
Policy Proceeds. The amount paid to the beneficiary upon the Insured’s death. The Policy Proceeds calculation is in the
“DEATH BENEFIT” and “GUARANTEED DISTRIBUTION RIDER” section.
Policy Start Date. The effective date of the Policy that is used to measure Policy Years,
months and anniversaries.
Policy Year. A one-year period starting on the Policy Start Date and on each Policy
Anniversary thereafter.
Segment. An allocation option we establish when any part of the initial Net
Premium is allocated to an Indexed Account on the Policy Start Date. Thereafter, a new Segment is started when a transfer of Cash Value is made to that
Indexed Account on a Policy Anniversary. Once a Segment is created, the Indexed Account Factors will not change for the Segment during the Segment Term. We may also refer to a “Segment” as an “Indexed Account Segment” in this prospectus and in your Policy.
Segment Credit. The amount that is applied to the Segment Value on the Segment
Maturity Date. On the Segment Maturity Date, the amount is equal to that Segment’s Segment Performance Rate multiplied by the current Segment Value. The
Segment Credit may be positive, negative or zero. When the Segment Credit is positive we may also refer to this adjustment as “earnings.” When the Segment Credit is negative we may also refer to this adjustment as “losses.” The Segment Credit is only applied to amounts that remain in a Segment until the Segment Maturity Date. We refer to this as the “Segment Index-Linked Credit” in your Policy.
Segment Index Performance. The percentage change in the Closing Value measured from the Segment Start Date to any day within the Segment
Term. Segment Index Performance can be positive, negative, or zero.
Segment Maturity Date. The Policy Anniversary on which a
Segment ends.
Segment Performance Rate. The Segment Performance Rate is based on the Segment
Index Performance, adjusted as follows. Prior to Segment Maturity Date, the Segment Index Performance is adjusted for the applicable Accrued Buffer Rate
and Accrued Cap Rate. On the Segment Maturity Date, the Segment Index Performance is adjusted for the applicable Buffer Rate and Cap Rate. The Segment Performance Rate can be positive, zero, or negative. At the Segment Maturity Date, any increase or reduction in the Segment Value of a particular Segment is determined by multiplying the Segment Performance Rate by the current Segment Value. We refer to this as the “Segment Index-Linked Credit Rate” in your Policy.
Segment Start Date. The date a Segment is created. The initial Segment Start
Date(s) begins on the Policy Start Date, and thereafter, will be the Policy Anniversary.
Segment Term. An Indexed Account Factor. The Segment Term is the number of
years that the Segment is in effect. We currently offer a Segment Term of 1 year. The Initial Segment Term(s) begin on the Policy Start Date.
Segment
Value. The Segment Value, for each Segment, is used to determine the amount available for any transaction or reallocation on the Segment Maturity Date. It is the amount that is applied to the Segment at the Segment Start Date, reduced proportionately for an Acceleration of Death Benefit for Terminal Illness payment and any loans that are not Distribution Payments by the same percentage that the loan or payment reduces the Interim Segment Value attributable to that Segment. A proportionate reduction to the Segment Value can be greater than the dollar amount of the transaction when the Segment Performance Rate is negative. The Segment Value is then, at the Segment Maturity Date, adjusted by the Segment Credit. The remaining Segment Value after a loan or Acceleration of Death Benefit for Terminal Illness payment will be used as the new Segment Value for the remainder of the Segment Term or until you take another loan or request an Acceleration of Death Benefit for Terminal Illness payment.
Separate Account. Brighthouse Separate Account L.
Surrender. A full withdrawal of your Cash Surrender Value.
Transfer Period. The 21 calendar days following the Policy Anniversary coinciding with the Segment Maturity Date for each
applicable Segment.
SUMMARY
The Brighthouse SmartGuard Plus® life insurance policy is a flexible premium adjustable index-linked life insurance policy issued by BLIC that
provides life insurance protection. It also provides Policy Owners with the opportunity for guaranteed distributions through the Guaranteed Distribution Rider
(“GDR”), as well as access to index-linked investments.
The GDR is automatically included with the Policy for an
additional charge. Subject to certain conditions, the GDR guarantees that you will receive distribution payments over a specific period of time, which you select when we
issue the Policy. You can choose to receive Distribution Payments for a period of 10 years, 20 years, or for lifetime (up to Attained Age 121). You are eligible to start Distribution Payments after the Policy has been in force for 10 years, provided the Policy is not a modified endowment contract (“MEC”), and you have repaid any Policy Loan Balance before starting Distribution Payments. A MEC is a cash value life insurance policy that exceeds federal tax law limits. Your Policy may become a MEC, for example, due to the payment of excess premiums or due to a reduction in your death benefit.
Distribution Payments and the One-time Payment are paid
in the form of loans. The Distribution Payments will reduce the Policy’s unloaned Cash Value (total of the values in the Fixed Account, Indexed Accounts, and Holding
Accounts) and the Policy Proceeds payable to your beneficiary. The maximum One-time Payment is the lesser of: (i) the difference between the cumulative Maximum Distribution Payments available to you based on your chosen Distribution Payment Duration and
Distribution Payment Frequency and the total Distribution Payments you have received since the Distribution Start Date; or (ii) The lesser of: three times the Maximum Distribution Payment or $150,000 (which is referred to as the One-time Payment Limit and is shown in the GDR). The GDR also includes a Lifetime Lapse Prevention Benefit and guarantees a minimum amount of Policy Proceeds ($10,000) upon the Insured’s death.
The Policy offers various Indexed Accounts, which permit Owners
to link their investments to the return of an Index for a specified period of time, which is called a Segment Term. Owners may receive positive interest based on the
Index’s positive returns, subject to a Cap Rate. Owners are also protected from a specified level of negative Index return—in the form of various Buffer Rate options where each provides its own specified level of protection from negative returns. The maximum downside protection provided by the Buffer Rate and the
potential maximum level of positive investment experience allowed by the Cap Rate are only fully available for amounts held until the end of the Segment
Term, which is called the Segment Maturity Date.
We currently offer Indexed Accounts with indices based on
the performance of securities. Each Indexed Account has a Segment Term of one year in length, a Buffer Rate (10%, 15%, 20% or 100%) and a Cap Rate. For each Indexed Account,
you select the Buffer Rate and the Index you want your investment performance to be based on. The performance of each Indexed Account will be subject to a Cap Rate.
The Indexed Account Factors for each Indexed Account, except for
the Holding Account interest rate, apply from the Segment Start Date to the Segment Maturity Date. We can add or discontinue any Indexed Account for transfers, renewals
and/or new allocations of Net Premiums prior to the start of a new Segment Term. You bear the risk that an Indexed Account in which you initially allocate to will not continue to be available in the future. While we are not obligated to offer any one particular Indexed Account, there will always be one Indexed Account available with a minimum of 5% downside protection. A Fixed
Account that guarantees a fixed rate of interest will also be available. Unless you allocate your Net Premiums to the Fixed Account or the Buffer 100, you may lose money by investing in the
Policy.
The Cap Rate is the maximum rate that may be credited at the Segment Maturity Date based on positive Segment Index Performance. For example, if the Cap Rate is 10% and the Segment Index Performance is 15%,
you will only be credited with a 10% gain. The Cap Rate is not a guaranteed positive rate of return.
New Cap Rates are declared for each subsequent Segment Term. The Cap Rates will not be less
than the Guaranteed Minimum Cap Rate stated in your Policy (“Guaranteed Minimum Cap Rate”), which will not be less than 3%. Thirty (30) days before the current Segment Term expires, we will mail you a notification indicating which
Indexed Accounts will be available at the start of the next Segment Term and their renewal Cap Rates. See “CAP RATE.” You may also obtain the new Cap Rates
by accessing the Company’s website at
https://www.brighthousefinancial.com/products/rates/ where at least two months of renewal Cap Rates are posted – i.e., for the current month and the following month.
You must notify us if you want to
transfer some or all of your Segment Value to a new Indexed Account or to the Fixed Account. The request to transfer must be received at our Administrative Office. See “REQUESTS AND ELECTIONS.” At the Segment Maturity Date, the Segment Value allocated to the maturing Indexed Account will automatically be renewed into the same Indexed Account unless you instruct us to transfer such amount into a different Indexed Account(s) or the Fixed Account or have elected the automatic Cash Value rebalancing program.
Under our current administrative procedures, we will also allow you to make transfers to and from the Indexed Accounts until the end of the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary. The Buffer Rate is the level of
negative Segment Index
performance from which the Company will protect you at the Segment Maturity Date. You are not protected from any negative performance in excess of the Buffer Rate. For example, if you choose an Indexed Account with a 10% Buffer Rate, we will only protect you from the first 10% of negative Segment Index Performance. If the Segment Index Performance is -50%, you will be credited with a -40% loss.
The Buffer Rates and Cap Rates accrue during the Segment Term and only reach full accrual on the last day of a Segment Term. The Buffer 100 is always fully accrued.
The Segment Value is used to determine the amount available for
any transaction or reallocation on the Segment Maturity Date. It is the amount that is applied to the Segment at the Segment Start Date, reduced proportionately for an
Acceleration of Death Benefit for Terminal Illness (“Accelerated Death Benefit”) payment and any loans that are not Distribution Payments by the same percentage that the loan or payment reduces the Interim Segment Value attributable to that Segment. A proportionate reduction to the Segment Value can be greater than the dollar amount of the transaction when the Segment Performance Rate is negative. The Segment Value is then adjusted, positively or negatively, by the Segment Credit on the Segment Maturity Date. The remaining Segment Value after a loan or Accelerated Death Benefit payment will be used as the new Segment Value for the remainder of the Segment Term or until you take another loan or request an
Accelerated Death Benefit payment. The Segment Value is calculated differently than the Interim Segment Value, as described below.
The value of an investment in a Segment before the Segment
Maturity Date (defined in the SPECIAL TERMS section above as “Interim Segment Value”) is the amount we use to determine the Indexed Account Cash Value prior to
the Segment Maturity Date. The Indexed Account Cash Value is part of the Cash Value, which determines how much is available for death benefits (including Policy Proceeds and an Accelerated Death Benefit payment), loans (not including loans in connection with Distribution Payments under the GDR), transfers from Indexed Account Cash Value to the Fixed Account if you choose to start (or restart) Distribution Payments under the GDR, and Surrenders (including Surrenders in connection with the Free Look Period).
To calculate Interim Segment Value, we use the Segment
Performance Rate as of the date of the calculation to determine the Segment return (defined in the SPECIAL TERMS section above as “Accrued Index Return”). The
Accrued Index Return is added to the current Segment Value amount to determine the Interim Segment Value. If the performance is negative on that date, any negative interest we calculate could be greater than it would be at the end of the term because the Buffer Rate is lower earlier in the term and does not fully accrue until the Segment Maturity Date. If the performance is positive on that date, any positive interest we calculate could be lower than it would be on the Segment Maturity Date because the Cap Rate is lower earlier in the Segment Term and does not fully accrue until the Segment Maturity Date.
An Accelerated Death Benefit payment and a loan that is not a Distribution Payment will reduce the Interim Segment Value by the dollar amount of the transaction and will reduce the current Segment Value by the percentage reduction in the Interim Segment Value (i.e. a proportional reduction). Accordingly, when negative performance has caused the Interim Segment Value to be
less than the current Segment Value, the reduction to the Segment is on more than a dollar for dollar basis. On the other hand, when positive performance has caused the
Interim Segment Value to be greater than the current Segment Value, the reduction to the Segment is on a less than dollar for dollar basis.
The Policy is only available in those states where it has been approved for sale.
We have the right to substitute a comparable index prior to the Segment Maturity Date if any Index is discontinued or we determine that our use of such Index should be discontinued because we are no longer licensed to use the Index, the method of calculation is substantially changed, or if Index Values become unavailable for any reason. We would attempt to choose a substitute Index that has a similar investment objective and risk profile to the replaced Index. See “Discontinuation or Substantial Change to an Index.”
See “SPECIAL TERMS” in this prospectus for more
detailed explanations of the terms associated with the Indexed Accounts.
The following chart describes the key
features of the Policy. Please read this prospectus for more detailed information about the Policy.
Key Features of the Policy
| |
Flexible premium adjustable index-linked life insurance policy. |
| |
You choose the amount and frequency of premium payments, subject to the
limits described herein. You select a Planned Premium Payment
schedule, which consists of a first-year premium amount and an
amount for subsequent premium payments. You can make Planned
Premiums Payments on an annual, semi-annual, quarterly, or
monthly schedule. No premium payment can be less than $1,000,
except with our consent. See “PREMIUMS.” We will not
accept additional premium payments after you start Distribution
Payments, unless the GDR terminates.
If you have a loan and we receive a payment from you, we will treat it as a
loan repayment, unless you request for us to treat it as a
premium payment. See “Loan Repayment” under
“LOANS” and “REQUESTS AND ELECTIONS.” |
Guaranteed Distribution Rider |
The GDR guarantees you will receive distribution payments over a specific
period of time. On the Policy Start Date, you may choose when
to receive Distribution Payments and the duration (10-year,
20-year or lifetime (up to Attained Age 121)). The GDR is
automatically included with your Policy, and you pay an annual
charge for this benefit. This GDR Charge, which is assessed
based on the Cash Value or the Face Amount, will be deducted from your
Policy’s Cash Value as part of the Annual Deduction.
Distribution Payments do not reduce the Face Amount, which means the GDR charge could continue
to be based on the full Face Amount even though the Policy
Proceeds payable to your beneficiary are
reduced because of the Distribution
Payments.
Once the Policy has been in force for at least 10 years, you are eligible to
receive Distribution Payments. The Policy cannot be a MEC, and
you must repay any Policy Loan Balance before starting
Distribution Payments. Distribution Payments are paid in the
form of loans. The Distribution Payments will reduce the
Policy’s unloaned Cash Value and the Policy Proceeds payable to your beneficiary. However, the GDR also includes a Lifetime Lapse Prevention Benefit
and guarantees a minimum amount of Policy Proceeds ($10,000) upon the
Insured’s death. If the Cash Value is insufficient to
cover Distribution Payments, we will increase the Cash Value in
order for the Distribution Payments to continue. All
Distribution Payments are subject to the minimum Distribution
Payment amount ($250) and Maximum Distribution Payment.
The GDR also provides a Lifetime Lapse Prevention Benefit that guarantees the
Policy will not lapse while the GDR is in force, provided
Annual Lapse Prevention Premiums are paid when due and the Cash
Value of the Policy, less any Surrender charge, is more than
the outstanding loan amounts plus accrued
interest.
See “GUARANTEED DISTRIBUTION RIDER.” |
| |
35-65 (see “THE LIFE POLICY”) |
| |
The total of the Fixed Account, Holding Accounts, Indexed Accounts, and the
Loan Account. See “CASH VALUE.”
|
| |
An Indexed Account provides the opportunity to link your investments to the
return of an Index. Each Indexed Account has the following
Indexed Account Factors: Index, Segment Term, Holding Account
interest rate, a Buffer Rate, and a Cap Rate. For each Indexed
Account, the Indexed Account Factors, except for the Holding
Account interest rate, apply from the Segment Start Date to the
Segment Maturity Date. See “INDEXED ACCOUNTS.”
|
| |
All Segment Terms are 1 year. See “SEGMENT TERM.”
|
| |
The current Indices are as follows:
•S&P 500® Index (Price Return Index);
•Russell 2000® Index (Price Return Index); and
•MSCI EAFE Index (Price Return Index). See “INDICES.” |
| |
We currently offer different levels of protection:
•Buffer 10 — A Buffer Rate where negative Segment
Index Performance of up to 10% is absorbed by us at the
Segment Maturity Date, which would leave you to absorb any
remaining negative Segment Index Performance of up to 90%.
•Buffer 15 — A Buffer Rate where negative Segment
Index Performance of up to 15% is absorbed by us at the
Segment Maturity Date, which would leave you to absorb any
remaining negative Segment Index Performance of up to
85%.
•Buffer 20 — A Buffer Rate where negative Segment
Index Performance of up to 20% is absorbed by us at the
Segment Maturity Date, which would leave you to absorb any
remaining negative Segment Index Performance of up to
80%.
•Buffer 100 — A Buffer Rate where 100% of negative
Segment Index Performance is absorbed by us throughout the
entire Segment Term. See “BUFFER
RATES.” |
| |
The maximum rate that may be credited at the Segment Maturity Date based
on positive Segment Index Performance. The Cap Rates will not
be less than the Guaranteed Minimum Cap Rate stated in your
Policy, which will not be less than 3%. See “CAP
RATES.” |
| |
We calculate an Interim Segment Value on each Business Day between the
Segment Start Date and prior to the Segment Maturity Date. The Interim
Segment Value is the amount we use to determine the Indexed
Account Cash Value prior to the Segment Maturity Date. The
Indexed Account Cash Value is part of the Cash Value, which
determines how much is available for death benefits (including
Policy Proceeds and an Accelerated Death Benefit payment),
loans (not including loans in connection with Distribution Payments under the
GDR), transfers from Indexed Account Cash Value to the Fixed
Account if you choose to start (or restart) Distribution
Payments under the GDR, and Surrenders (including Surrenders in
connection with the Free Look Period), if these transactions
occur on any day other than the Segment Maturity Date. An
Accelerated Death Benefit payment and a loan that is not a Distribution
Payment will reduce the Interim Segment Value by the dollar
amount of the transaction.
The Interim Segment Value of an Indexed Account is equal to the current
Segment Value in the Indexed Account plus Accrued Index Return.
Accrued Index Return is determined using the Accrued Buffer
Rate, which is less than the full Buffer Rate (except for the
Buffer 100, the Accrued Buffer Rate is always 100%), and the
Accrued Cap Rate, which is less than the full Cap Rate. This
means any negative interest we use to calculate the Interim Segment Value
may be greater than it would be on the Segment Maturity Date,
and any positive interest we credit may be less than it would
be on the Segment Maturity Date. See “INTERIM SEGMENT
VALUE CALCULATION.” You may obtain your Interim Segment
Value on any Business Day by calling us at 1-800-882-1292 or by accessing our website at
www.brighthousefinancial.com. |
Allocations and Transfers |
You may allocate Net Premiums among the Fixed Account and the Indexed
Accounts. The initial Net Premium will be allocated according
to the allocations you chose at the time you apply for the
Policy. Future Net Premiums are allocated as
follows:
•Future Net Premium to the Fixed Account will always go directly into the
Fixed Account.
•Future Net Premium to Indexed Accounts received within the Transfer Period, which is the 21 day period following any Policy Anniversary, will be
treated as if it had been received on the Policy Anniversary, and we will
apply the Net Premium directly to the Indexed Accounts.
•Future Net Premium received after the Transfer Period will remain in the
associated Holding Account until the next Policy Anniversary. On the Policy
Anniversary, we will transfer amounts in the Holding Account
to its associated Indexed Account according to your latest
instructions on file with us unless you provide us different
allocation instructions before the end of the Transfer Period
or have elected the automatic Cash Value rebalancing
program. In connection with any Segment Maturity Date, the
Segment Value allocated to the maturing Indexed Account will
automatically be renewed into the same Indexed Account unless
you instruct us to transfer such amount into a different
Indexed Account(s) or the Fixed Account or have elected the automatic Cash
Value rebalancing program. If the same Segment is not
available, the Segment Value will be transferred to the Fixed
Account. Under our current administrative procedures, you have
the Transfer Period to notify us that you want to transfer some
or all of your Segment Value to a new Indexed Account(s) or the
Fixed Account. The request to transfer must be received at our
Administrative Office. See “REQUESTS AND ELECTIONS.”
Transfers out of an Indexed Account before Segment Maturity Date are not
permitted. See “TRANSFERS.”
In addition, you may transfer any unloaned Cash Value among the Fixed
Account and Indexed Accounts on a Policy Anniversary. Unloaned
Cash Value is the total of the values in the Fixed Account,
Holding Accounts, and Indexed Accounts. Under our current
administrative procedures, we will allow you to make transfers
during the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary. See “TRANSFERS” and “AUTOMATIC CASH
VALUE REBALANCING.”
If you have started Distribution Payments under the GDR, all of your unloaned
Cash Value will have been transferred to the Fixed Account, and
you may not transfer to the Indexed Accounts while receiving
Distribution Payments. When you start Distribution Payments,
even though you are no longer allocated to any Indexed Account,
we will not refund any portion of your Annual Indexed Account
Charge. Your Annual Deduction will not include an Annual Indexed
Account Charge if all your unloaned Cash Value is in the Fixed Account. If
you stop receiving Distribution Payments and instruct us to
transfer amounts from the Fixed Account to one or more Indexed
Accounts, the transfer will take effect on the next Policy
Anniversary, and you will be assessed an Annual Indexed Account
Charge as part of the Annual Deduction. See “Annual Deduction” under “CHARGES.” |
| |
We offer a Fixed Account. See Appendix C. |
| |
You may borrow money from your Policy by taking a loan. A loan reduces the
Policy’s Cash Value in the Indexed Accounts, Holding
Accounts, and the Fixed Account and may increase your risk of
Policy lapse. Policy Proceeds will also be reduced by the
Policy Loan Balance. Loans may have tax consequences. There are
two ways to take a loan: (1) by borrowing some portion of the Policy’s unloaned Cash Value, if available. We will calculate the maximum amount you
may borrow, as of the date the loan is requested; and (2) by taking a
Distribution Payment or the One-time Payment, which is
available through the GDR. The maximum One-time Payment is the
lesser of: •The difference between the cumulative Maximum Distribution
Payments available to you based on your chosen Distribution
Payment Duration and Distribution Payment Frequency and the
total Distribution Payments you have received since the
Distribution Start Date; or, •The lesser of: three times the Maximum Distribution Payment or
$150,000 (which is referred to as the One-time Payment Limit
and is shown in the GDR).
See Appendix D for examples of the One-time Payment.
Please note that while Distribution Payments and the One-time Payment are
loans, the terms, conditions, and limitations are not the same
as loans not covered by the GDR. For a complete understanding
of the differences, see “LOANS” and
“GUARANTEED DISTRIBUTION RIDER.” Additionally, you
may Surrender the Policy for its Cash Surrender Value during
the lifetime of the Insured at any time. Surrenders could result in surrender
charges and taxes. Surrenders and loans, if taken from the
Indexed Accounts before the end of a Segment Term, will be
based on an Interim Segment Value calculation. In extreme
circumstances, you could lose all or a significant portion of
the value of an Indexed Account if you Surrender or take a loan from the Indexed Account before the Segment Maturity Date. Partial withdrawals are not
permitted under the Policy. See “SURRENDERS.”
|
| |
During the first ten Policy Years, if you Surrender or lapse your Policy, then we
will deduct a Surrender charge from the Cash Value. We deduct the Surrender
charge using the Policy Deduction Method. The maximum Surrender
charge per $1,000 of Face Amount that could apply under any
Policy is $45 (in Policy Year 1), which reduces to $0 in Policy
Year 11 and later. See “SURRENDERS.” |
| |
The death benefit is determined as of the date of the Insured’s death.
We must receive Notice of due proof of death. The amount we pay
to the beneficiary (or beneficiaries) is referred to as the
Policy Proceeds. The Policy Proceeds are generally equal to the
greater of Policy’s Face Amount and the Cash Value (plus
any applicable refund of a portion of annual charges) multiplied by a certain
factor specific to the Insured and provided in the Policy. See
“DEATH BENEFIT.” All Distribution Payments taken
under the GDR reduce the death benefit amount on a dollar for
dollar basis, and such reductions could be significant. The GDR
guarantees a minimum amount of Policy Proceeds ($10,000). See “Impact
of Distribution Payments on Your Policy” under
“GUARANTEED DISTRIBUTION RIDER.”
|
| |
You will bear the following charges and expenses:
(i)Annual Indexed Account Charge;
(ii)Annual Administrative Charge;
(iii)Annual Cost of Insurance Charge; (v)Percent of Premium Charge; and
(vi)Surrender charge, if applicable. The Annual Deduction is comprised of (i) through (iv). See “FEE TABLES” below. |
FEE TABLES
The following tables describe the fees and expenses that an Owner will pay when buying, owning and Surrendering the Policy. Please refer to your Policy specifications page for information about the specific fees you will pay each year.
The first table describes the fees and expenses
that you will pay at the time that you buy or Surrender the Policy.
| |
|
|
Percent of Premium Charge |
|
|
| |
Upon Surrender or lapse in the first
ten Policy Years |
|
| |
|
In Policy year 1, $45 per $1,000 of
Face Amount |
| |
|
In Policy year 1, $14.48 per $1,000 of
Face Amount |
Charge for a Representative
Insured
(The Representative Insured is a
male, age 50, in the nonsmoker
risk class under a Policy with a
Face Amount of $200,000) |
|
In Policy year 1, $22.83 per $1,000 of
Face Amount |
Illustration of Benefits Charge |
On provision of each illustration in
excess of one per year |
$25 per illustration
(Not currently charged) |
1
The Surrender charge varies based on individual characteristics, including the Policy’s duration and the
Insured’s issue age, risk class, sex (except for unisex Policies). The Surrender
charge may not be representative of the charge that a particular Policy Owner would pay. You can obtain more information about the Surrender charge that would apply for a particular insured by contacting your financial professional.
The next
table describes the charges that you will pay periodically during the time that you own the Policy.
| |
|
|
| |
Annual Cost of Insurance Charge1 |
On Policy Start Date and each Policy
Anniversary |
|
| |
|
$1,000 per $1,000 of net amount at
risk2 |
| |
|
$0.74 per $1,000 of net amount at
risk2 |
Charge in the first Policy year for a
Representative Insured
(The Representative Insured is a
male, age 50, in the nonsmoker
risk class, under a Policy with a
Face Amount of $200,000) |
|
$2.34 per $1,000 of net amount at
risk2 |
Annual Administrative Charge3 |
On Policy Start Date and each Policy
Anniversary |
|
| |
|
$0.65 per $1,000 of Face Amount |
| |
|
$0.31 per $1,000 of Face Amount |
Charge in the first Policy year for a
Representative Insured
(The Representative Insured is a
male, age 50, in the nonsmoker
risk class, under a Policy with a
Face Amount of $200,000) |
|
$0.44 per $1,000 of Face Amount |
Annual Indexed Account Charge4 |
On Policy Start Date and each Policy
Anniversary if you allocate to one or
more Indexed Accounts |
0.5% of Cash Value in the Indexed
Accounts |
| |
|
8% on Policy Loan Balance |
Charges for Optional Benefits (Riders)
|
| |
On Policy Start Date and each Policy
Anniversary8 |
|
| |
|
$19.40 per $1,000 of the greater of
(1) 60% of the Policy’s Face Amount9,
or (2) Cash Value. |
| |
|
$6.08 per $1,000 of the greater of
(1) 67% of the Policy’s Face Amount9,
or (2) Cash Value. |
Charge in the first Policy year for a
Representative Insured
(The Representative Insured is a
male, age 50, in the nonsmoker
risk class, under a Policy with a
Face Amount of $200,000 and a
lifetime Distribution Payment
Duration) |
|
$12.50 per $1,000 of the greater of
(1) 55% of the Policy’s Face Amount9,
or (2) Cash Value. |
1
The Annual Cost of Insurance Charge varies based on individual characteristics,
including the Policy’s Face Amount and the Attained Age, risk class, and (except for unisex Policies) sex. The cost of insurance charge may not be representative
of the charge that a particular Owner would pay. You can obtain more information about the cost of insurance charge that would apply for a particular insured by contacting your financial representative.
2
The net amount at risk is the difference between the death benefit (generally discounted at 1%) and the Cash Value.
3
The Annual Administrative Charge equals: the Face Amount at the beginning of the
Policy Year; times the applicable Annual Administrative Charge rate for that Policy Year divided by 1,000. The actual Annual Administrative Charge rate we use may be lower than the maximum Annual Administrative Charge rate shown above and on the Policy specifications
pages.
4
The current Annual Indexed Account Charge rate is 0.2%. If you start receiving Distribution Payments and we transfer all your Cash Value from the Indexed Accounts and/or Holding Accounts to the Fixed Account, you will not be refunded any portion of the Annual Indexed Account Charge for that Policy Year.
5
Interest accrues daily on the Policy Loan Balance at an annual rate not more than the annual maximum fixed loan interest rate of 8%. We also credit interest on the Cash Value in the Loan Account at a rate not less than the Loan Account guaranteed minimum interest rate of 1%. As a result, the loan interest spread, the difference between the interest rates we charge on Policy Loan Balance and the interest earned on Cash Value we hold as security for the loan (“loan collateral”) could be as much as 7%.
6
Charged annually or on loan termination, if earlier.
7
The GDR Charge rate varies based on individual characteristics, including the Insured’s Issue Age and (except for unisex Policies) sex. The GDR Charge rate ranges from $6.08 to $19.04 per $1,000 of the greater of (1) the GDR Charge
percentage multiplied by the Policy’s Face Amount, or (2) the Policy’s Cash Value. We refer to the GDR Charge rate as the Guaranteed Rider Charge Rate in the GDR. The GDR Charge percentage varies based on individual characteristics,
including the Insured’s Issue Age, (except for unisex Policies) sex, and Distribution Payment Duration. The GDR Charge percentage ranges from 48% to 67%. We refer to the GDR Charge percentage as the Guaranteed Rider Charge
Percentage in the GDR. The GDR Charge may not be representative of the charge that a particular
Owner would pay. You can obtain more information about the GDR Charge that would apply for a particular insured by contacting your financial representative.
8
The GDR Charge will not be deducted after Distributions Payments terminate or the GDR terminates.
9
The percentage of Face Amount varies based on individual characteristics, including
the Distribution Payment Duration selected and the Insured’s age and (except for unisex Policies) sex. The percentage of Face Amount may not be representative of the charge that a particular Owner would pay. You can obtain more information about the percentage of Face Amount that would apply to a particular insured by contacting your financial professional.
The purchase of the Policy involves certain risks. You should carefully consider the following factors, in addition to the matters set forth elsewhere in the prospectus, prior to purchasing the Policy.
There is a risk of substantial loss of your principal and
any earnings (unless you allocate your Net Premiums and any earnings to the Fixed Account or Buffer 100) because you agree to absorb all losses that exceed the Buffer Rate
for the Indexed Accounts you select under the Policy. This means that if the negative Segment Index Performance for an Indexed Account you select exceeds the corresponding Buffer Rate at the Segment Maturity Date, you will bear the portion of the loss that exceeds the Buffer Rate.
Buffer Rates are not cumulative, and their protection does not
extend beyond the length of any given Segment Term. If you keep amounts allocated to an Indexed Account over multiple Segment Terms in which negative interest is credited,
the total combined loss of Segment Value over those multiple Segment Terms may exceed the stated Buffer Rate for a single Segment Term.
The method we use in calculating your Interim Segment Value may result in an amount that is less than the amount you would receive had you held the investment until the Segment Maturity Date. The Interim Segment Value is the amount we use to determine the Indexed Account Cash Value prior to the Segment Maturity Date. The Indexed Account Cash Value is part of the Cash Value, which determines how much is available for death benefits (including Policy Proceeds and an Accelerated Death Benefit payment), loans (not including loans in connection with Distribution Payments under the GDR), transfers from Indexed Account Cash Value to the Fixed Account if you choose to start (or restart) Distribution Payments under the GDR, and Surrenders (including Surrenders in connection with the Free Look Period). If Segment Index Performance is negative when we process these transactions, any remaining Segment Value may be significantly less than if you waited to when Segment Index Performance was positive.
When we calculate the
Interim Segment Value, we use the Segment Performance Rate as of the date of the calculation. The Buffer Rates and Cap Rates accrue during the Segment Term and only reach
full accrual on the last day of a Segment Term. For Buffer 100, the Buffer Rate will always be 100% throughout the Segment Term. This means that if the Segment Index Performance is negative on the Interim Segment Value calculation date, any negative interest we calculate could be greater than it would be on the Segment Maturity Date because the Buffer Rate is lower earlier in the Segment Term and does not fully accrue until the Segment Maturity Date. If Segment Index Performance is positive on the Interim Segment Value calculation date, any positive interest we calculate could be lower than it would be on the Segment Maturity Date because the Cap Rate is lower earlier in the Segment Term and does not fully accrue until the Segment Maturity Date. Any losses could be significant.
•
If you allocate to Indexed Accounts and request any of the following transactions on any
day other than a Policy Anniversary (i.e., a Segment Maturity Date), we use the Interim Segment Value calculation to:
•
Surrender your Policy (including Surrenders in connection with the Free Look
Period),
•
take a loan (not including loans in connection with Distribution Payments under the
GDR)
•
request a payment under the Accelerated Death Benefit, or
•
transfer Indexed Account Cash Value to the Fixed Account if you choose to start (or
restart) Distribution Payments under the GDR.
•
If
Segment Index Performance is negative, when we process these transactions, you bear the risk that any remaining Segment Value may be significantly less than if you waited to
when Segment Index Performance was positive or on the Segment Maturity Date. In extreme
circumstances, you could lose all or a significant portion of the value of an Indexed Account if you Surrender or take a loan from the Indexed Account before the Segment
Maturity Date.
•
If you die, your beneficiary will receive the Policy Proceeds. If you are allocated to
Indexed Accounts and we calculate the Policy Proceeds on any day other than a Segment Start Date or Segment Maturity Date, your Indexed Account Cash Value will equal the Interim Segment Value, which may be less than if the Indexed Accounts reached their
Segment Maturity Dates or if Segment Index Performance was positive.
The Cap Rate may limit any positive Segment Index Performance
used in calculating the Segment Performance Rate on the Segment Maturity Date. This means that the Segment Performance Rate may be lower than the Segment Index Performance because any positive return of the respective Index is subject to a maximum in the form of the Cap Rate. We set Cap Rates at our discretion, subject to the Guaranteed Minimum Cap Rate. You bear the risk that we will not set Cap Rates higher than the Guaranteed Minimum Cap Rate.
No company other than BLIC has any legal responsibility to pay amounts that BLIC owes under the Policy. An Owner should look to the financial strength of BLIC for its claims-paying ability.
No ownership of the underlying securities
When you purchase the Policy and allocate your Net Premiums to an Indexed Account(s), you will not be investing in the Index or the securities tracked by
the Index.
Surrender—Unsuitable as a Short-Term Savings Vehicle
If you Surrender the Policy within
the first ten years, you will be subject to a Surrender charge as well as income tax on any gain that is distributed or deemed to be distributed from the Policy. If you
Surrender the Policy, the Surrender charge could exceed the Cash Value of your Policy and you would receive no proceeds upon Surrender. In addition, if you Surrender your Policy on any day
other than a Policy Anniversary date (including to exercise your Free Look Right), any available Cash Surrender Value that is invested in Indexed Accounts will be based on
Interim Segment Value.
Partial withdrawals are not permitted under the Policy. As a result, you may only access your Policy’s Cash Value through loans (including Distribution Payments through the GDR) or by full Surrender of the Policy.
You should purchase
the Policy only if you have the financial ability to keep it in force for a substantial period of time. You should not purchase the Policy if you intend to Surrender it in
the near future. Even if you do not Surrender your Policy, Surrender charges may play a role in determining whether your Policy will lapse (terminate without value), because
Surrender charges determine the Cash Surrender Value, which is a measure we use to determine whether your Policy will enter a 62-day grace period (“Grace Period”) and possibly lapse.
You select a Planned Premium Payment schedule, which consists of a first-year premium amount and an amount for subsequent premium payments. This schedule appears in your Policy. Your Planned Premium Payments may not be sufficient to keep your Policy in force and avoid lapse.
If the GDR has been terminated, your Policy may lapse if you
have paid an insufficient amount of premiums and your Cash Surrender Value is not enough to pay the Annual Deduction. If this happens, your Policy may enter a 62-day Grace
Period. We will notify you that the Policy will lapse unless you make a sufficient payment of additional premium during the Grace Period. If your Policy does lapse, your insurance coverage will terminate. No Policy Proceeds will be payable. Lapse of a Policy on which there is an outstanding loan may have adverse tax consequences.
While the GDR is in force, the Lifetime Lapse Prevention
Benefit guarantees your Policy will not lapse. However, if premiums paid to date are less than the accumulated Annual Lapse Prevention Premiums due since the Policy Start
Date, you have the Grace period to pay the difference and the Excess Loan amount, if any. If this payment is not made within the 62-day Grace Period, the GDR will terminate, and your Policy may lapse.
The GDR is automatically included with your Policy for a charge. Distribution Payments cannot begin until the Policy has been in force for at least 10 years, your Policy cannot be a MEC and you must repay any outstanding Policy Loan Balance. Distribution Payments are subject to minimum and maximum distribution amounts. Distribution Payments are treated as loans and reduce your unloaned Cash Value and Policy Proceeds.
There are circumstances that, on their own, will terminate the
GDR. The GDR will terminate the date an additional loan is taken outside of your scheduled Distribution Payments, if the One-time Payment is not available, or that
additional loan exceeds the One-time Payment (if available). If you request an amount that exceeds the One-time Payment, your request will not be considered in Good Order. We will contact you to ask if you want to change the One-time Payment amount to an amount that does not exceed the maximum One-time Payment or confirm that you want to process the request using the original amount, which will terminate the GDR. Your request will not be in Good Order until we confirm your instructions or receive new ones.
In addition, the GDR will terminate if the Policy terminates or
if premiums paid are less than the accumulated Annual Lapse Prevention Premiums due since the Policy Start Date.
Distribution Payments will also terminate if your Policy becomes a MEC or you exercise the Accelerated Death Benefit or reach Attained Age 121.
When you begin receiving Distribution Payments, any Cash Value in
the Indexed Accounts and Holding Accounts will be transferred into the Fixed Account. While you are receiving Distribution Payments, you cannot transfer or allocate Cash
Value to the Indexed Accounts. This means you will no longer be invested in any of the Indexed Accounts, and you will no longer be exposed to any potential positive market investment performance. In addition, you will no longer be eligible to make premium payments. If you choose to start (or restart) Distribution Payments on any day other than a Policy Anniversary date, any Indexed Account Cash Value transferred to the Fixed Account will be based on Interim Segment Value, which could be significantly less than if you waited to the Segment Maturity Date.
When you start Distribution Payments, even though you are no
longer allocated to any Indexed Account, we will not refund any portion of your Annual Indexed Account Charge. On the next Policy Anniversary, your Annual Deduction will not
include an Annual Indexed Account Charge if all your unloaned Cash Value is in the Fixed Account. If you stop receiving Distribution Payments and instruct us to transfer amounts from the Fixed Account to one or more Indexed Accounts, the transfer will take effect on the next Policy Anniversary, and you will be assessed an Annual Indexed Account Charge as part of the Annual Deduction.
If you suspend Distribution Payments, you may not restart
Distribution Payments until the suspension is in effect at least one year from the date of your last Distribution Payment. If it has been less than one year since you
received your last Distribution Payment and you request a loan, we will treat this loan as your One-time Payment, as long as you have not already received your One-time Payment. If the loan amount taken exceeds the One-time Payment amount available at the
time of your request, we
will process the loan, however the GDR will terminate. If the One-time Payment is not available and you request a loan during the one-year suspension period, we will process
the loan, however the GDR will terminate.
You should consult with your attorney or qualified tax advisor to determine the tax consequences of the GDR and the Policy. See, “FEDERAL TAX CONSIDERATIONS” section.
Transfers among the Fixed Account, the Holding Accounts, and the Indexed Account(s) occur on the Policy Anniversary. This means you cannot transfer out of a current Indexed Account, Holding Account, or the Fixed Account until the Policy Anniversary. Any amounts transferred can only be transferred to new Indexed Accounts or the Fixed Account. This may limit your ability to react to market conditions. Under our current administrative procedures, we will allow you to make transfers during the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary. Holding Accounts are not available for direct investments; they are accounts for temporarily holding Cash Value until the next Policy Anniversary.
In addition, you should understand that for renewals into the same Indexed Account, a new Cap Rate will go into effect on the Policy Anniversary that coincides with the beginning of the new Segment. Moreover, at the Segment Maturity Date, the Segment Value allocated to the Indexed Account that has reached its Segment Maturity Date will be automatically renewed into the same Indexed Account unless you instruct us to transfer such amount into a different Indexed Account(s) or the Fixed Account or have elected the automatic Cash Value rebalancing program. The request must be received at our Administrative Office. See “REQUESTS AND ELECTIONS.” Under our current administrative Procedures, you have the Transfer Period to notify us that you want to transfer some or all of your Segment Value to a new Indexed Account(s) or the Fixed Account. Failure to provide such instructions during the Transfer Period will result in an automatic renewal for the duration of the new Segment Term, which is a period of one (1) year. You cannot allocate or transfer Cash Value to the Indexed Accounts while you are receiving Distribution Payments under the GDR. See the “TRANSFERS” section.
Risks Associated with the Referenced
Indices
Each of the reference Indices is a “price return index," not a “total return index," and therefore does not reflect dividends declared by any of the component companies in the Index. This will reduce the Segment Index Performance and will cause the Index to underperform a direct investment in the securities composing the Index. Because the S&P
500® Index (Price Return Index), the Russell 2000® Index (Price Return Index) and the MSCI EAFE Index (Price Return Index) are each comprised of a collection of
equity securities, in each case the value of the component securities is subject to market risk, or the risk that market fluctuations may cause the value of the component
securities to go up or down, sometimes rapidly and unpredictably. In addition, the value of equity securities may increase or decline for reasons directly related to the
issuers of the securities. (See “INDICES” and “BUFFER RATES.”)
In
addition, each index has its own unique risks, as follows:
•
S&P 500® Index. This index is composed of equity securities issued by large-capitalization (“large cap”) U.S.
companies. In general, it is more difficult for large-cap companies to pivot their strategies quickly in response to changes in their industry. In addition, because they typically are more well-established, it is rare to see large-cap companies have the high growth rates that can be seen with successful small-capitalization (“small cap”) companies.
•
Russell 2000® Index. This index is composed of equity securities of small-cap U.S. companies. Generally, the securities of
small-cap companies are more volatile and riskier than the securities of larger companies. Small-cap companies are more likely to fail than larger companies.
•
MSCI EAFE Index. The MSCI EAFE Index is comprised of equity securities of large- and mid-capitalization
(“mid-cap”) companies and it is designed to measure the equity market performance of developed markets, including countries in Europe, Australia, and the Far East. In general, large-cap companies may be unable to respond quickly in response to changes in their industry and new competitive challenges and may not be able to attain the high growth rates of successful smaller companies. The securities of mid-cap companies may be more volatile and
may involve more risk than the securities of larger companies. Securities issued by non-U.S. companies (including related depositary receipts) are subject to the risks related to investments in foreign markets (e.g., increased price volatility; changing currency exchange rates; and greater political, regulatory, and economic uncertainty).
Availability of Indexed Accounts
Your selling firm may limit the Indexed Accounts available through that firm when your Policy is issued or at Segment Maturity Date. Additionally, we may discontinue our use of an Index at any time. After the Policy is issued, there will always be one Indexed Account available with a minimum of 5% of downside protection. Consequently, a particular Indexed Account
may not be available for
you to transfer your Segment Value, or the Cash Value in the Fixed Account (“Fixed Account Cash Value”) into after a Segment Maturity Date. You
cannot allocate or transfer Cash Value to the Indexed Accounts while you are receiving Distribution Payments under the GDR.
If we were to offer only one Indexed Account, you would be limited to investing in that one Indexed Account. If that Indexed Account does not meet your investment objectives or financial goals, you could transfer to the Fixed Account (subject to applicable conditions described in the “TRANSFERS” section, including the requirement to remain invested in the Fixed Account until the next Policy Anniversary), Surrender your Policy and/or invest in another investment vehicle. If you Surrender your Policy, you might incur Surrender charges, taxes, tax penalties or other adjustments.
If you invest in another investment vehicle, that investment may have different features, fees and risks than your Policy.
An Indexed Account may be Substituted
In addition to reserving the right to discontinue
the use of an Index, we have the right to substitute a comparable index prior to the Segment Maturity if any Index is discontinued or we determine that our use of such Index
should be discontinued because we are no longer licensed to use the Index, the method of calculation of the Closing Value of the Index is substantially changed, or if Index values become unavailable for any reason. We would attempt to choose a substitute Index that has a similar investment objective and risk profile to the replaced Index. In the event that a similar index is not
found, we will substitute the original Index with a domestic or international broad-based securities market index. An Indexed Account will not end prior to the Segment Maturity End Date due to our inability to find a similar index. The substituted Index
may not be acceptable to you, and you will be unable to transfer your Indexed Account Cash Value
in the associated Indexed Account to another Indexed Account(s) or the Fixed Account (if available) until the Transfer Period coinciding with the Segment Maturity Date. If you no longer want to
remain invested in that Indexed Account for the remainder of the Segment Term, your only option will be to Surrender the Policy. See “Risk of Loss” above for
more information about the risks of withdrawals based on Interim Segment Value. Additionally, you might incur surrender charges and taxes. Upon substitution of an Index, we will calculate your Segment Index Performance on the replaced Index up
until the date of substitution and the substitute Index from the date of substitution to the Policy Anniversary. An Index substitution will not change the Buffer Rate or Cap
Rate for an existing Indexed Account. The performance of the new Index may not be as good as the one that it substituted and as a result your Segment Index Performance may have been better if there had been no substitution.
We anticipate that the Policy should be deemed to be a life insurance policy under Federal tax law. However, the rules are not entirely clear in certain circumstances. The insurance proceeds payable on the death of the Insured will never be less than the minimum amount required for the Policy to be treated as life insurance under section 7702 of The Internal Revenue Code of 1986, as amended (the “Code”), as in effect on the date the Policy was issued. If your Policy is not treated as a life insurance policy under Federal tax law, increases in the Policy’s Cash Value will be taxed on a current basis.
Even if your Policy is treated as a life insurance policy for Federal tax purposes, it may become a modified endowment contract, for example, due to the payment of excess premiums or due to a reduction in your death benefit. If your Policy becomes a modified endowment contract, Surrenders, loans, and use of the Policy as collateral for a loan will be treated as a distribution of the earnings in the Policy and will be taxable as ordinary income to the extent thereof. In addition, if the Policy Owner is under age 59½ at the time of the Surrender or loan, the amount that is included in income will generally be subject to a 10% additional tax.
If the Policy is not a modified endowment contract,
distributions generally will be treated first as a return of basis or investment in the policy and then as taxable income. However, different rules apply in the first
fifteen Policy Years, when distributions accompanied by benefit reductions may be taxable prior to a complete Surrender of your investment in the Policy. Moreover, loans will generally not be treated as distributions prior to termination of your Policy, whether by lapse, Surrender or exchange. Finally, neither distributions nor loans from a Policy that is not a modified endowment contract are subject to the 10% additional tax.
See “FEDERAL TAX CONSIDERATIONS.” You should
consult a qualified tax adviser for assistance in all Policy-related tax
matters.
Tax laws, regulations, and interpretations have often been changed in the past and such changes continue to be proposed. To the extent that you purchase a Policy based on its potential tax benefits, there is no certainty that such tax benefits will always continue to exist.
Loan Risks
A loan, whether or not repaid, will affect the Cash Value of your Policy over time because we subtract the amount of the loan from the Indexed Accounts, Holding Accounts, and/or Fixed Account as collateral, and hold it in the Loan Account. Loans also reduce the Policy Proceeds.
Although you can call our Administrative Office at any time to
determine what is available for a loan, the maximum amount you may borrow (the “Loan Value”) will be calculated at the end of the Business Day when we process
the loan. These amounts may be different. If you request a loan that exceeds the Loan Value, your request will not be considered in Good Order. We will contact you to let you know that your requested amount exceeds the Loan Value. We will not consider the request in Good Order unless you revise the loan request to an amount that is less than or equal to the Loan Value.
Any portion of Loan Interest that is not paid when due will be added to the loan and will bear interest at the same rate as the loan.
Any loans taken from Indexed Accounts prior to the Segment
Maturity Date will be based on Interim Segment Value. Due to the application of the Accrued Buffer Rate and the Accrued Cap Rate, this means you may experience greater
losses, if Segment Index performance is negative and constant throughout the Segment Term, and lesser gains, if Segment Index Performance is positive and constant throughout the Term, than you would if you waited until the end of the Segment Term. If your Policy has an Excess Loan, we will provide a Grace Period for payment of the excess due. If the excess due remains unpaid at the end of the Grace Period, the Policy will terminate without value. The Grace Period will end 62-days from the date the notification is sent.
In order to keep the GDR in force on and after the Distribution
Start Date, the only loans permitted to be taken are Distribution Payments and the One-time Payment. While you are receiving Distribution Payments, you can change the amount
of future Distribution Payments, as long as you do not exceed the Maximum Distribution Payment amount available to you. Any amount you request outside of your scheduled Distribution Payments is an additional loan, and we will treat this loan as your One-time Payment, as long as you have not already received your One-time Payment. If the One-time Payment has not been taken and the loan amount taken exceeds the One-time Payment amount available at the time of your request, this GDR will terminate.
Cybersecurity and Certain Business Continuity Risks
Our business is largely conducted through complex information technology and communications systems operated by us and our service providers and
business partners (e.g., the firms involved in the distribution and sale of our products). Our operations rely on the secure processing, storage and transmission of data and confidential and other information in our systems and
the systems of
third-party service providers. We have established administrative and technical controls and business continuity and resilience plans to
protect our operations against attempts by unauthorized third parties to improperly access, modify, disrupt the operation of, or prevent access to critical networks or
systems or data within them (a “cyber-attack”). Despite these protocols, the
techniques used to attack systems and networks change frequently, are becoming more sophisticated,
and
can originate from a wide variety of sources including internal actors (through malicious or accidental
acts),
terrorists, nation
states, financially or politically motivated actors, or other third parties,
such as external service providers. Furthermore, the rapid evolution
and increased adoption of artificial intelligence technologies may intensify our cybersecurity
risks, including the deployment of artificial intelligence technologies
(“AI”)
by
malicious third parties and threat actors that may increase in sophistication and
effectiveness in the future. There may be an increased risk of cyber-attacks
that
may adversely disrupt or degrade our operations and compromise our data during periods of
geo-political or military conflict. There is also a chance that certain risks have not been identified or prepared for, or that an attack may not be
detected which limits our ability, as well as that of our service providers and business partners, to plan for or respond to,
an attack.
A failure of our computer systems could cause significant interruptions in our operations, compromise the security, confidentiality or privacy of sensitive data, and otherwise adversely affect our business and ability to administer the Policy. Unanticipated problems with, or failures of, our disaster recovery systems and business continuity plans could also have a material, negative impact on our ability to conduct business and on our financial condition and operations, as well as on individual Owners and their Policies. Our operations also could be negatively impacted by a cyber-attack or system failure affecting a third party, such as a service provider, business partner, another
participant in the financial markets or a governmental or regulatory authority. Disruptions or failures to our operations, systems and networks can originate from a wide variety of sources including, but not limited to, a disaster
such as a natural catastrophe, epidemic or pandemic crisis, military or terrorist actions, cyber-attack, and unanticipated problems with our or our service providers’
disaster recovery systems (and the disaster recovery systems of such vendors’ suppliers, vendors, or subcontractors). Such disasters and events may adversely affect our ability to conduct business or administer the Policy.
Cyber-attacks
and disruptions or failures to our systems and business operations could result in regulatory fines or sanctions, litigation, penalties or financial losses, reputational
harm, loss of customers, and/or otherwise adversely affect our business. Such events could also interfere with our processing of Policy transactions, including the
processing of transfer orders from our website; impact our ability to calculate Policy values; cause the release and/or possible loss, misappropriation or corruption of data or confidential Owner or business information; or impede order processing or cause other operational issues.
We cannot control the cybersecurity plans and systems implemented by third parties, including service providers. Although we continually make efforts to identify and
reduce our exposure to cybersecurity risks and operations failures, there can be no assurance
that we or our third party service providers will be able to detect, manage, prevent, or avoid
cyber-attacks, disruptions, or failures affecting your Policy in the future.
This prospectus describes the Brighthouse SmartGuard
Plus® life insurance policy issued by us and describes all
the material features of the Policy. Brighthouse SmartGuard
Plus® is a life insurance policy between you as the Owner,
and us, the insurance company, where you agree to make premium payments to us and we agree to provide you life insurance coverage. The minimum Issue Age for this Policy is 35, and the maximum Issue Age is 65.
The Policy includes the application, any
attached riders, and any endorsements. Together they comprise the entire Policy and are made a part of the Policy when the insurance applied for is accepted. Any endorsement
to the Policy must be approved by our President, Vice President or Secretary. No other persons have the authority to alter or change any terms, conditions, or agreements of the Policy, or to waive any provisions.
The primary purpose of the Policy is to provide life insurance
protection. Upon receipt of satisfactory proof of the death of the Insured, we pay the Policy Proceeds to the beneficiary of the Policy.
The Policy also provides Owners with the opportunity for guaranteed distributions through the GDR. The GDR comes standard with the Policy and provides you with the opportunity for a specified amount of guaranteed distributions for a certain period of time. The minimum amount you can receive is guaranteed at issue. Distribution Payments will be based on the Cash Value at the time payments begin and subject to certain minimum and maximum limits. If necessary, we will increase your Policy’s Cash Value to cover any Distribution Payments. The Policy must be in force for at least 10 years before you are eligible to start Distribution Payments. In addition, the Policy cannot be a MEC and you must repay any Policy Loan Balance before Distributions Payments may begin. The GDR also has a Lifetime Lapse Prevention Benefit that guarantees that the Policy will not lapse, subject to certain conditions. The GDR also guarantees a minimum amount of Policy Proceeds ($10,000). See “GUARANTEED DISTRIBUTION RIDER.”
When you purchase the Policy, you can choose one or more of the
available Indexed Accounts and the Fixed Account. We are obligated to pay all money we owe under the Policy, including Policy Proceeds and Guaranteed Minimum Distribution
Payments. Any such amount that exceeds the assets in the Separate Account is paid from our General Account. Our ability to do so is subject to our financial strength and claims-paying ability and is not guaranteed by any other party.
The Policy is designed to be held over a long term, is not offered primarily as an investment, and should not be used as a short-term savings vehicle. Various negative consequences can occur if you fail to hold the Policy long-term. For example, if you Surrender your Policy, the Surrender charge could exceed the Cash Value of your Policy and you would receive no proceeds upon Surrender. In addition, before any applicable Segment Maturity Date, your Cash Surrender Value would be based on the Interim Segment Value.
The Policy has features and benefits that may be appropriate for
you based on your financial situation and objectives, but we are not a fiduciary and do not provide investment advice or make recommendations regarding insurance or investment products, or any securities transactions or investment strategies involving securities. You should ask your financial representative for guidance as to whether this Policy may be appropriate for you. Please bear in mind that your financial representative, or any financial firm or financial professional with whom you consult for advice, acts on your behalf, not ours. We are not party to any agreement between you and your financial professional. See “DISTRIBUTION OF THE POLICIES” for information on firms that sell the Policy.
Generally, the Policy benefits from tax deferral. Tax deferral
means that you are not taxed on any increase in your Policy’s Cash Value until a distribution or deemed distribution is made from your Policy, such as a Surrender or
lapse of the Policy. (See “FEDERAL TAX CONSIDERATIONS.”)
Our General Account consists of all assets
owned by us other than those in the Separate Account and our other separate accounts. We have sole discretion over the investment of assets in the General Account and the
Separate Account.
As Owner, you exercise
all interests and rights under the Policy. You can change the Owner at any time, subject to our underwriting requirements. The Policy may be owned generally by more than one
Owner. (See “OWNERSHIP PROVISIONS.”)
Upon notification to you, this Policy may
be modified by us, but only if such modification is necessary to make changes as required by the Internal Revenue Code or by any other applicable law, regulation or
interpretation in order to continue treatment of this Policy as life insurance.
If we make any payment in good faith,
relying on our records or evidence supplied to us, our duty will be fully discharged. We have the right to correct any errors in the Policy.
Statements Made in the Application for the Policy
In the absence of fraud, all statements
made by the Insured or on the Insured’s behalf, or by the Owner or on the Owner’s behalf, will be deemed representations and not warranties. Material
misstatements will not be used to void the Policy or any rider or to deny a claim unless made in the Application for the Policy or a rider.
Misstatement of Age or Sex
If we determine that there was a misstatement of age or sex
reflected in the Policy, the death benefit will be recalculated based on the Annual Cost of Insurance Charge on the prior Policy Anniversary and the Annual Cost of Insurance
Charge rate based on the correct age and sex. Future Annual Deductions will be based on the correct age and sex.
If the Policy is issued on a unisex basis, all rates, benefits
and values that contain differences based on sex are modified to provide the same rates, benefits, and values regardless of sex.
We cannot contest the coverage after the Policy has been in
force during the lifetime of the Insured for two years from its Policy Issue Date (the date we created your insurance policy). This provision will not apply to any rider
that contains its own incontestability clause. If the Policy is reinstated, a new two-year contestability period, during the lifetime of the Insured, will begin as of the date the Policy was reinstated. The Policy will be contestable only as to statements made in the reinstatement application.
If the Policy was issued as the result of the exercise of an
option given in another policy and proof of insurability was not required, the contestable period applicable to the coverage resulting from the option exercise will end at
the same time as it would have under the original policy.
It may not be in your best interest to Surrender, lapse, change or borrow from existing life insurance policies or annuity contracts in connection with the purchase of the Policy. You should compare your existing insurance and the Policy carefully. You should replace your existing insurance only when you determine that the Policy is better for you. You may have to pay a Surrender charge on your existing insurance, and the Policy will impose a new Surrender charge period. You should talk to your financial professional or tax adviser to make sure the exchange will be tax-free. If you Surrender your existing policy for cash and then buy the Policy, you may have to pay a tax, including possibly a penalty tax, on the Surrender. Because we may not issue the Policy until we have received an initial premium from your existing insurance company, the issuance of the Policy may be delayed.
Paid-Up Life Insurance Option
Paid-Up Life Insurance (“Paid-Up Life Insurance”) is permanent life insurance with no further premiums due. The Paid-Up Life Insurance Option allows you to exchange your Policy while it is in force, on any Policy Anniversary before Attained Age 121, for a new policy that provides Paid-Up Life Insurance. Your request for the exchange must be in Good Order on or before the Policy Anniversary on which the exchange is to be effective. This Policy will be void as of the date of the exchange.
Paid-Up Life Insurance will be provided by using the Cash Surrender Value of the Policy as a net single premium at the then current age of the Insured as calculated by the issuing company for that plan of insurance. The Paid-Up Life Insurance will be issued on a plan of insurance offered by us or one of our affiliates; and with a start date as of the date the Policy ends.
PREMIUMS
Subject to the limits described below, you choose the amount
and frequency of premium payments. You select a Planned Premium Payment schedule, which consists of a first-year premium amount and an amount for subsequent premium payments. This schedule appears in your Policy. Your Planned Premium Payments will not
necessarily keep your Policy in force. You may skip Planned Premium Payments or
make additional payments. You should consider the risks of paying an insufficient amount of premiums (see “RISK FACTORS”). Additional payments could be subject
to underwriting. No payment can be less than $1,000, except with our consent.
A Percent of Premium Charge will be
deducted from each premium we receive. Premiums paid after the first premium must be paid to our Administrative Office or as otherwise approved by us. A premium received
within the Transfer Period will be applied as if it had been received on the anniversary.
You can make Planned Premiums Payments on an annual, semi-annual, quarterly, or monthly schedule. We will send premium notices for annual, semi-annual, or quarterly Planned Premiums Payments, only if premium payments are not drawn directly from your checking account pursuant to the pre-authorized checking arrangement. You can change your Planned Premium Payment schedule by sending your request to us in Good Order at our Administrative Office. You may also change your Planned Premium Payments; however, a new Policy Specification page will not be sent to you. You may not make premium payments on or after the Policy Anniversary when the Insured reaches Attained Age 121, except for premiums required during the Grace Period.
You may allocate Net Premiums among the Fixed Account and the
Indexed Accounts. The Net Premium will be allocated according to the allocations you chose at the time you apply for the Policy. While your Policy is in force, you may
request to change the allocation of future Net Premiums among the Fixed Account and Indexed Accounts. If an Indexed Account is not available, any amount allocated to that Indexed Account will automatically be allocated to the Fixed Account.
If any premium payments under the Policy exceed the “7-pay limit” under Federal tax law, your Policy will become a MEC, and you may have more adverse tax consequences with respect to certain distributions than would otherwise be the case if premium payments did not exceed the “7-pay limit.” Information about your “7-pay limit” is found in your Policy illustration. If we receive a premium payment 30 days or less before the anniversary of the 7-pay testing period that exceeds the “7-pay limit” and would cause the Policy to become a MEC and waiting until the anniversary to apply that payment would prevent the Policy from becoming a MEC, we may retain the premium payment in a non-interest- bearing account and apply the payment to the Policy on the anniversary. If we follow this procedure, we will notify you and give you the option of having the premium payment applied to the Policy before the anniversary. Otherwise, if you make a premium payment that exceeds the “7-pay limit,” we will apply the payment to the Policy according to our standard procedures described below and notify you that the Policy has become a MEC.
Under our current processing, if you have a loan and we receive a
payment from you, we will treat it as a loan repayment, unless you request for us to treat it as a premium payment. See “REQUESTS AND ELECTIONS.” Loan repayments
may be allocated in the same manner as Net Premium. We will not accept additional premium payments on and after the Distribution Start Date unless the GDR terminates.
Attained Age 121. You may not make premium payments on or after the Policy Anniversary when the Insured reaches Attained Age
121, except for premiums required during the Grace Period.
Brighthouse SmartGuard Plus® is an index-linked insurance policy. Its Indexed Accounts offer
potential interest based upon Index performance. This potential interest—the Segment Performance Rate—may be a positive or negative percentage or zero.
Based upon the Segment Index Performance of the Index associated
with the Indexed Account, we calculate the Segment Value and Interim Segment Value, as follows:
•
On the Segment Maturity Date, a Segment Credit, which reflects the full downside
protection of the Buffer Rate and the full upside potential of the Cap Rate, is applied to the current Segment Value to calculate the Segment Value on the Segment Maturity Date. The current Segment Value on any given date is the Segment Value as of the close of the prior day before any adjustments for transactions occurring on the present Business Day are taken into account.
•
On any Business Day prior to the Segment Maturity Date, we calculate Interim Segment
Value. The Interim Segment Value on that day is the current Segment Value plus the Accrued Index Return, which reflects an Accrued Buffer Rate
(less
than the full downside protection of the Buffer Rate) and an Accrued Cap Rate (less than the full upside potential of the Cap Rate). The remaining Segment
Value after a loan or Accelerated Death Benefit payment will be used as the new Segment Value for the remainder of the Segment Term or until you take
another loan or request an Accelerated Death Benefit payment. The Interim Segment Value is the amount we use to determine the Indexed Account Cash Value prior to the Segment Maturity Date. The Indexed Account Cash Value is part of the Cash Value, which determines how much is available for the following:
(i)
death benefits (including Policy Proceeds and an Accelerated Death Benefit
payment);
(ii)
loans (not including loans in connection with Distribution Payments under the
GDR);
(iii)
transfers from Indexed Account Cash Value to the Fixed Account if you choose to
start (or restart) Distribution Payments under the GDR; and
(iv)
Surrenders (including Surrenders in connection with the Free Look Period).
(See “INTERIM SEGMENT VALUE CALCULATION.”)
Given that Segment Index Performance may be positive, zero or negative, your Accrued Index Return or Segment Credit may be positive, zero or negative. Therefore, it is possible for you to lose a portion of premium payments and any earnings invested in the Policy. The Accrued Index Return and Segment Credit are based on a certain amount of protection against decreases in the Closing Value of the Index and a limitation on increases in the Closing Value of the Index. The extent of the downside protection varies by the Buffer Rate you select. If you access amounts in the Indexed Accounts before the Segment Maturity Date, we will instead calculate an Interim Segment Value on each Business Day between the Segment Start Date and the Segment Maturity Date. (See “INTERIM SEGMENT VALUE CALCULATION.”)
Prior to starting Distribution
Payments under the GDR and when Distribution Payments are suspended or terminated, you have the opportunity to allocate your Net Premiums and unloaned Cash Value to any of
the Indexed Accounts described below. We are not obligated to offer any one particular Indexed Account and your selling firm may limit the Indexed Accounts available through that firm when your Policy is issued. After the Policy is issued, there will always be one Indexed Account available with a
minimum of 5% downside protection.
The following chart lists the Indexed Accounts (each of which is issued with a Cap Rate, which will be announced prior to the Segment Start Date) available:
INDEXED ACCOUNTS available before the Distribution Start Date |
| |
|
BUFFER 100 (100% downside protection) |
| |
S&P 500® Index
Russell 2000® Index
MSCI EAFE Index |
BUFFER 20 (up to 20% downside protection) |
| |
S&P 500® Index
Russell 2000® Index
MSCI EAFE Index |
BUFFER 15 (up to 15% downside protection) |
| |
S&P 500® Index
Russell 2000® Index
MSCI EAFE Index |
BUFFER 10 (up to 10% downside protection) |
| |
S&P 500® Index Russell 2000® Index
MSCI EAFE Index |
On each Indexed
Account Segment Start Date, we establish a Cap Rate for each Segment Term. The initial Cap Rate, as applicable, for each Indexed Account is established on the Policy Start
Date. Thereafter the Cap Rate, as applicable, for each subsequent Indexed Account is established for each subsequent Segment Term. See “Cap Rate”. The Indices
are described in more detail below, under the heading “Indices.”
Please note, Indexed Accounts with
higher Buffer Rates tend to have lower Cap Rates than other Indexed Accounts that use the same Index and Segment Term but provide lower Buffer Rates.
For example, an S&P 500® Index with a Buffer 20 will tend to have a Cap Rate that is
lower than an S&P 500® Index with a Buffer 10.
We reserve the right to change or stop offering any of the Indexed Accounts or suspend offering any of the Indexed Accounts. After your Policy is issued, there will always be one Indexed Account available
with a minimum of 5% downside protection. We may also
add Indexed Accounts in the future. All Indexed Accounts may not be available through every selling
broker-dealer.
The Indexed Account Factors consist of an Index, Segment Term, Holding Account interest rate, a Buffer Rate, and a Cap Rate.
Indexed Account Factors are used in calculating Accrued Index
Return for Interim Segment Value, the Segment Credit for Segment Value on Segment Maturity Date, and, if applicable, any interest credited to amounts in the Holding Account.
Indexed Account Factors, except for the Holding Account interest rate, apply from the Segment Start Date to the Segment Maturity Date. Each Holding Account has its own Holding Account interest rate, which is declared periodically by us. See “HOLDING ACCOUNTS.”
Indexed Account Segment (“Segment”)
On the Policy Start Date, a Segment is created when any part of the initial Net Premium is allocated to that Indexed Account. After the Policy Start Date, a Segment is created when a transfer of Cash Value is made to that Indexed Account. Cash Value can be transferred to an Indexed Account only on a Policy Anniversary. Under our current administrative procedures, we will allow you to make transfers during the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary. The date a Segment is created is called the Segment Start Date. The Segment Maturity Date is the last date of the Segment Term. This date will always be a Policy Anniversary. Any Segment in effect at the time of Policy lapse will not be reinstated upon Reinstatement of the Policy.
The Indices are described in more detail below, under the heading
“Indices.” For each new Indexed Account we declare a new Cap Rate, as applicable, for each Segment Term. The initial Cap Rate, as applicable, for each Indexed
Account is declared on the Policy Start Date. Thereafter the Cap Rate, as applicable, for each subsequent Indexed Account is declared for each subsequent Segment Term. See “Cap Rate”.
The Segment Term is the period of time that an Indexed
Account’s performance is linked to the return of an Index. For all Indexed Accounts we currently offer Segment Terms of 1 year. A Segment Term(s) begins on the Segment
Start Date and ends on a Segment Maturity Date.
For initial Net Premium allocated to an Indexed Account, the Segment Start Date is the Policy Start Date. The Segment Maturity Date is the Policy Anniversary coinciding with the 1-year Segment Term for the Indexed Account you have selected. The Segment Start Date for each subsequent Segment Term will always be a Policy Anniversary.
We will send you written notification
thirty (30) days in advance of the maturing Segments in which you are currently invested. The notification will include a list of all Indexed Accounts that will be available
to you at your next Segment Start Date, specifically applicable Cap Rates. You may also obtain the new Cap Rates by accessing the Company’s website at https://www.brighthousefinancial.com/products/rates/ where at least two months of renewal Cap Rates are posted
– i.e., for the current month and the following month.
Segment Maturity
Date
At the Segment Maturity Date, the Segment Value allocated to the maturing Indexed Account will automatically be renewed into the same Indexed Account unless you instruct us to transfer such amount into a different Indexed Account(s) or the Fixed Account or have elected the automatic Cash Value rebalancing program. Under our current administrative
procedures, you have the Transfer Period to notify us that you want to transfer some or all of your Segment Value to a new Indexed Account(s) or the Fixed Account. The request to transfer must be received at our Administrative Office. See “REQUESTS AND ELECTIONS.” For renewals into the same Indexed Account, a new Cap Rate will apply, which could be higher, lower or equal to the prior Cap Rate.
The Segment Performance Rate of an Indexed Account is based on
the performance of the associated Index. We currently offer Indexed Accounts with indices based on the performance of securities. In the future we may offer Indexed Accounts based on other types of indices. We may also add or remove indices for new Policies at our discretion.
The following Indices are currently available:
S&P 500® Index (Price Return Index). The S&P 500® Index includes 500 large cap stocks from leading companies in leading industries of the U.S. economy,
capturing approximately 80% coverage of U.S. equities by market capitalization. The S&P 500® Index does not include dividends declared by any of the companies in
this Index.
Russell 2000® Index (Price Return Index). The Russell 2000® Index measures the performance of the small-cap segment of the U.S. equity universe. The Russell 2000 is a subset of the Russell 3000® Index representing approximately 10% of the total market capitalization of that index. It includes approximately 2000 of the smallest securities based on a combination of their market cap and current index membership. The Russell
2000®Index does not include dividends declared by any of the companies in this Index.
MSCI EAFE Index (Price Return Index). The MSCI EAFE Index (Europe, Australasia, Far East) is a free float-adjusted market capitalization index that
is designed to measure the equity market performance of developed markets, excluding the US & Canada. As of the date of this prospectus the MSCI EAFE Index consists of
the following 21 developed market country indices: Australia, Austria, Belgium, Denmark, Finland, France, Germany, Hong Kong, Ireland, Israel, Italy, Japan, the Netherlands, New Zealand, Norway, Portugal, Singapore, Spain, Sweden, Switzerland, and the United Kingdom. The MSCI EAFE Index does not include dividends declared by any of the companies in this Index. Index Value and Index Performance will be calculated without any exchange rate adjustment.
See Appendix A for important information regarding the
publishers of the Indices.
Discontinuation or Substantial Change to an Index.
If any Index is discontinued or we determine
that our use of such Index should be discontinued because we are no longer licensed to use the Index, the method of calculation is substantially changed, or if Index Values
become unavailable for any reason, we may substitute a comparable index with a similar investment objective and risk profile. The substituted index may not be acceptable to you. We will send you written notification thirty (30) days in advance of such substitution or as soon as reasonably possible. Upon substitution of an Index, we will calculate your Segment Index Performance on the existing Index up until the date of substitution and the substitute Index from the date of substitution to the Segment Maturity Date. The Segment Index Performance as of the Segment Maturity Date will be equal to the return from having invested in the initial Index up to the substitution date and then investing in the substitute Index from the date of substitution to the Segment Maturity Date, based on the following formula: (initial Index at Index substitution date ÷ initial Index at Segment Start Date) x (substituted Index at Segment Maturity Date ÷ substituted Index at substitution date) – 1. An Index substitution will not change the Segment Term, Buffer Rate, or Cap Rate for an existing Indexed Account. The performance of the new Index may not be as good as the one that it substituted and as a result your Segment Index Performance may have been better if there had been no substitution.
See Appendix B for an Index substitution Segment Value
example.
Closing Value of the Index
The Closing Value of the Index, on a Business Day, is the
published Closing Value on that Business Day. The Closing Value on any day that is not a Business Day is the value as of the prior Business Day. We will use consistent
sources to obtain Closing Values. If these sources are no longer available for specific indices, we will select an alternative published source(s) for these Closing Values.
Segment Index
Performance
The Segment Performance Rate of a Segment is based, in part, on the performance of an Index. Segment Index Performance is the percentage change in the Closing Value of the Index measured from the Segment Start Date to any day, including the Segment Maturity Date, during the Segment Term. The Segment Index Performance can be positive, zero or negative.
The Buffer Rate is accrued from the Segment Start Date to the
Segment Maturity Date, and the full Buffer Rate only applies if you hold the Indexed Account until the Segment Maturity Date. The Buffer Rate for each Indexed Account is the
maximum amount of any negative Segment Index Performance we protect you from at the Segment Maturity Date. Any negative Segment Index Performance beyond the Buffer Rate will reduce the Segment Maturity Value. If Segment Index Performance is negative, the Segment Performance Rate can
never be greater than zero.
We currently offer the following Buffer Rates: Buffer 10, Buffer 15, Buffer 20 and Buffer
100:
For example, a -15% Segment Index Performance with a 10% Buffer Rate will result in a -5% Segment Performance Rate; or a -10% Segment Index Performance with a 20% Buffer Rate will result in a 0% Segment Performance Rate. The Buffer Rate may vary between Indexed Accounts and is an annual
rate.
In deciding whether to choose an Indexed Account with a higher Buffer Rate, you should consider that Indexed Accounts with higher Buffer Rates tend to have lower Cap Rates than Indexed Accounts with lower Buffer Rates that have the same Index and Segment Term. This is because higher Buffer Rates offer greater downside protection.
The Cap Rate is measured from the Segment Start Date to the Segment Maturity Date, and the full Cap Rate only applies if you hold the Indexed Account until the Segment Maturity Date. The Cap Rate is the maximum rate that may be credited at the Segment Maturity Date based on Segment Index Performance. For example, a 15% Segment Index Performance with a 10% Cap Rate will result in a 10% Segment Performance Rate; or a 5% Segment Index Performance with a 10% Cap Rate will result in a 5% Segment Performance Rate. The Cap Rate may vary between Indexed Accounts and is an annual rate but not a guaranteed rate of return. A new Cap Rate is declared for each new Segment Term, and such rate will not be less than the guaranteed minimum Cap Rate stated in your Policy, which will not be less than 3%.
A thirty (30) day advance written notification will be mailed to
you indicating your maturing Segments, the Indexed Accounts that will be available upon your next Segment Start Date, and the new Cap Rates and current interest rate for the
Fixed Account. At the Segment Maturity Date, the Segment Value will automatically be renewed into the same Indexed Account, with the new Cap Rate, unless you elect to transfer such amount into a different Indexed Account(s) or the Fixed Account. See “TRANSFERS.”
ADDITION OR DISCONTINUANCE OF AN INDEXED ACCOUNT
The Indexed Account Factors for each Indexed Account, except for the Holding Account interest rate, apply from the Segment Start Date to the Segment Maturity Date. We can add or discontinue any Indexed Account for transfers, renewals and/or new allocations of Net Premiums prior to the start of a new Segment Term. You bear the risk that an Indexed Account in which you initially allocate to will not continue to be available in the future. While we are not obligated to offer any one particular Indexed Account, there will always be one Indexed Account available with a minimum of 5% downside protection. When a change
is made to an Indexed Account or an Index, we will send a notification describing any changes to the Indexed Account, as required by law. This change will take effect under
your Policy as of the next Policy Anniversary for any transfers and/or Net Premium allocations into the Indexed Account(s). If you are currently allocated to an Indexed
Account that is no longer available, you will remain in that Indexed Account until the Segment Maturity Date. For more on transfers and renewals, see “TRANSFERS.”
HOLDING ACCOUNTS
Each Indexed Account has an associated Holding Account. When you can allocate new premium or a loan repayment to an Indexed Account outside of the Transfer Period, the amounts will remain in the associated Holding Account until the Policy Anniversary (i.e., the next Segment Start Date) when such amounts will automatically transfer to the Indexed Accounts according to your latest instructions on file with us. The Holding Accounts are part of our General Account. Future Net Premiums and loan repayments allocated to the Fixed Account will always go directly into the Fixed Account.
Each Holding Account has its own Holding Account interest rate and interest is credited daily at an effective annual rate that we declare periodically. The Holding Account guaranteed minimum interest rate for all Holding Accounts will not be less than 1%. The Holding Account guaranteed minimum interest rate for each Holding Account that applies to your Policy can be found in the Policy specifications pages. We refer to the Holding Account guaranteed minimum interest rate as the Guaranteed Minimum Holding Account Interest Rate in the Policy specifications pages. Your financial representative can tell you the current interest rates that apply to the Holding Accounts. We reserve the right to change the Holding Account interest rates.
We will transfer the Cash Value in a Holding Account (“Holding Account Cash Value”) to the associated Indexed Account on the Policy Anniversary. Under our current administrative procedures, we will allow you to make transfers during the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary.
Thirty (30) days before the Policy
Anniversary, we will mail you a notification identifying your current Indexed Account allocations, including any Holding Accounts, and indicating all Indexed Accounts and
Indexed Account Factors that will be available on your Policy Anniversary.
Before the Holding Account Cash Value is
transferred into its associated Indexed Account, you can change your allocation instructions and transfer to other investment options under the Policy. For example, if you
allocated Net Premium to the S&P 500 Indexed Account and such amounts are being held in the associated Holding Account, you can notify us that you want to change your allocation to the MSCI EAFE Indexed Account. On the next Segment Start Date, we will transfer the Holding Account Cash Value in the S&P 500 Indexed Account to the MSCI EAFE Indexed
Account.
The Segment Value for each Segment is used to determine the
amount available for any transactions or reallocations on the Segment Maturity Date. It is the amount that is applied to the Segment at the Segment Start Date, reduced
proportionately for an Accelerated Death Benefit payment and any loans that are not Distribution Payments by the same percentage that the loan or payment reduces the Interim Segment Value attributable to that Segment. A proportionate reduction can be greater than the dollar amount of the transaction when the Segment Performance Rate is negative. The Segment Value is then at the Segment Maturity Date, adjusted by the Segment Credit. The remaining Segment Value after a loan or Accelerated Death Benefit payment will be used as the new Segment Value for the remainder of the Segment Term or until you take another loan or request an Accelerated Death Benefit payment.
The Segment Value on the Policy Start Date equals:
(i)
the portion of the initial Net Premium allocated to the Indexed Account, less
(ii)
any Annual Deduction taken from that Indexed Account at such time.
On Segment Start Dates after the Policy Start Date, which is always a Policy Anniversary, the Segment Value equals:
(i)
Any amount (including Holding Account Cash Value and any amounts from the Fixed
Account and/or from a maturing Indexed Account) transferring into the new Segment; plus
(ii)
Any Net Premium paid on that date allocated to the Indexed Account; less
(iii)
Any amount transferred from the Segment into the Fixed Account or a different Indexed
Account; less
(iv)
Any part of the Annual Deduction charged to the Indexed Account to cover the Policy
Year that starts on that day.
On any
other day, prior to the Segment Maturity Date, the Segment Value equals:
(i) The Segment Value as of the close of the prior day (we also refer
to this as the “current Segment Value”); less
(ii)
A proportional reduction to reflect any amount transferred from the Segment due to a
loan; less
(iii) A proportional reduction to reflect any
Cash Value reduction resulting from a payment under the Accelerated Death
Benefit.
On the
Segment Maturity Date, the Segment Value, equals:
(i)
The Segment Value as of the prior day; less
(ii)
Any amount transferred from the Segment to the Loan Account on that day; less
(iii) Any Cash Value reduction resulting from a payment under the Accelerated Death Benefit; plus
CALCULATING YOUR SEGMENT VALUE ON A
SEGMENT MATURITY DATE
On the Segment Maturity Date, we apply the Segment Credit to your current Segment Value. The Segment Credit is based on the Segment Performance Rate, which is the rate credited at the Segment Maturity Date. The Segment Performance Rate is determined by the Segment Index Performance adjusted for the applicable Buffer Rate or Cap Rate. The Segment Performance Rate can be positive, zero or negative and is determined as follows:
| |
If Segment Index Performance (can be
positive,
zero or negative) is: |
Segment Performance Rate will equal: |
Indexed Accounts with a Cap Rate |
|
•The lesser of: zero or the
Segment Index Performance
increased by the Buffer Rate
(For example: a -15% Segment
Index Performance with a Buffer
10 will result in a -5% Segment
Performance Rate. The Segment
Performance Rate can never be
greater than zero if the Segment
Index Performance is negative.) |
| |
•Greater than or equal to zero and less than the Cap Rate |
•The Segment Index Performance |
| |
•Greater than zero and equal to or greater than the Cap Rate |
|
Example 1 set forth below, as well as Examples 2-5 found throughout this prospectus, are intended to illustrate how various features of your Policy work.
Example 1—Calculating your Segment Value on a Segment
Maturity Date (See below.)
Example 2—Calculating your Interim Segment Value (See “INTERIM SEGMENT VALUE CALCULATION.”)
Example
3—Transfers (See “TRANSFERS.”)
Example 4—Loans (See “LOANS.”)
Example 5—Death Benefit (See “DEATH BENEFIT.”)
These examples should not be considered a representation of past or future performance for any Indexed Accounts. Actual performance may be greater or less than those shown in the examples. Similarly, the Closing Values of the Index in the examples are not an estimate or guarantee of future Segment Index Performance.
The Cap Rates shown in the following examples are for
illustrative purposes only and may not reflect actual declared rates.
Values are rounded for display purposes
only.
Example 1—Calculating your Segment Value on a Segment Maturity Date
Example 1 is intended to show how the Segment Value on a Segment Maturity Date is calculated. The example assumes Owner 1 allocates to an Indexed Account and she allows her allocation to renew year to year for five years. In the example she has selected an Indexed Account with S&P 500® Index, 1-Year Segment Term, Buffer 10 and a Cap Rate of 10%. Her Segment Value on the Segment Start Date is
$50,000. For purposes of the example, assume no loans are taken, there is no payment of the Accelerated Death Benefit, and no Annual Deduction during the five-year example
period, and the Cap Rate stays at 10% for all five years. If a loan was taken or a payment under the Accelerated Death Benefit was made during the Segment Term,
an Interim Segment Value
calculation will apply; and consequently, the Segment Value for the Segment Term will reflect that calculation. On the Policy Start Date and each Policy
Anniversary thereafter, we deduct the charges for the Annual Deduction from your Cash Value. The Annual Deduction for each Policy Year will be taken from any
Indexed Account according to the Policy Deduction Method. This example assumes no Annual Deduction.
Example 1—Indexed Account with Cap Rate:
Owner 1 allocates to an Indexed Account with a 1-Year Segment
Term / Buffer 10 / S&P 500® Index with a Cap Rate of
10% and lets it renew year after year for five years. We assume the Cap Rate is 10% for each subsequent Segment Term. Her Segment Value on the Segment Start Date is $50,000. The following example illustrates how her initial Indexed Account could perform over a five-year period given fluctuating Closing Values of the Index. For renewals into the same Indexed Account, a new Cap Rate would be declared and go into effect on the Policy Anniversary that coincides with the beginning of the new Indexed Account.
| |
|
|
|
|
|
| |
| |
|
|
|
|
|
Closing Value of the Index |
|
|
|
|
|
| |
Closing Value of the Index |
|
|
|
|
|
Segment Index Performance(2) |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
|
Segment Performance Rate (one
year)(3) |
|
|
|
|
|
| |
|
|
|
|
|
| |
|
|
|
|
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
Segment Value at Segment Start Date in year one is $50,000 of Net Premiums. In
years two through five, the Segment Value at Segment Start Date would be $55,000, $57,750, $57,750 and $57,750, respectively, which was the Segment Value at Segment Maturity Date for the prior year. These values do not reflect the Annual Deduction. The Annual Deduction is taken from the Segment Value on the Segment Start Date.
(2)
Segment Index Performance is equal to the percentage change in the Closing Value of the Index measured from the
Segment Start Date to the Segment Maturity Date. For example, in year one, Segment Index Performance is calculated as follows:
(1,200 [Closing Value of the Index at Segment Maturity Date]
÷ 1,000 [Closing Value of the Index at Segment Start Date]) – 1 = 20%
(3)
In year one, Segment Index Performance exceeds the Cap Rate and therefore the Segment Performance Rate is equal to the Cap Rate. In years two and three the Segment Performance Rate is equal to the Segment Index Performance because the Segment Index Performance is not negative and does not exceed the Cap Rate. In year four the Segment Performance Rate is 0% because the Segment Index Performance is –5% and the Buffer 10 absorbs up to 10% of the negative Segment Index Performance. In year five, the Segment Performance Rate is –5% because the Segment Index
Performance is –15% and the Buffer 10 absorbs up to 10% of negative Segment Index Performance.
(4)
The Segment Credit is equal to the product of the current Segment Value (Segment
Value at the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) multiplied by the Segment Performance Rate. For example, in year one the Segment Credit is calculated as follows:
$50,000 [current Segment Value] x 10% [Segment Performance Rate] = $5,000
(5)
The Segment Value on the Segment Maturity Date is equal to the current Segment
Value (Segment Value at the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) plus the Segment Credit. For example, in year one the Segment Value on the Segment Maturity Date is calculated as follows:
$50,000 [current Segment Value] + $5,000 [Segment Credit] = $55,000
INTERIM SEGMENT VALUE
CALCULATION
Your Segment Value in each Indexed Account on the Segment Maturity Date is calculated as described above under “Calculating your Segment Value on a Segment Maturity Date.” In setting the various rates we use in calculating the Segment Value, we assume that you are going to hold a Segment until the Segment Maturity Date. Nevertheless, you have the right under the Policy to Surrender the Policy, request a payment under the Accelerated Death Benefit, take a loan, or start Distribution Payments under the GDR before the Segment Maturity Date. Therefore, we calculate an Interim Segment Value on each Business Day between the Segment Start Date and prior to the Segment Maturity Date. The Interim Segment Value is the amount we use to determine the Indexed Account Cash Value prior to the Segment Maturity Date.
The Indexed Account Cash Value is part of
the Cash Value, which determines how much is available for the following:
(i)
death benefits (including Policy Proceeds and an Accelerated Death Benefit
payment);
(ii)
loans (not including loans in connection with Distribution Payments under the
GDR);
(iii)
transfers from Indexed Account Cash Value to the Fixed Account if you choose to
start (or restart) Distribution Payments under the GDR; or
(iv)
Surrenders (including Surrenders in connection with the Free Look Period).
An Accelerated Death Benefit payment and a loan that is not a Distribution Payment will reduce the Interim Segment Value by the dollar amount of the transaction.
When calculating Interim Segment Value, we apply the Segment
Index Performance adjusted for the Segment Performance Rate to the current Segment Value as of the date of the calculation to determine the Accrued Index Return. The Accrued Index Return is added to the current Segment Value amount to determine the Interim Segment Value. This means that if the Segment Index Performance is negative on the Interim Segment Value calculation date, any negative interest we calculate could be greater than it would be on the Segment Maturity Date because the Buffer Rate is lower earlier in the Segment Term and does not fully accrue until the Segment Maturity Date. If Segment Index Performance is positive on the Interim Segment Value calculation date, any positive interest we calculate could be lower than it would be on the Segment Maturity Date because the Cap Rate is lower earlier in the Segment Term and does not fully accrue until the Segment Maturity Date. Losses could be significant. The Interim Segment Value will be reduced, dollar for dollar, by any loans or reductions due to an Accelerated Death Benefit payment.
If you take a loan that is not a Distribution Payment or
accelerate the death benefit, we will apply the Policy Deduction Method to determine the reduction to your current Segment Value. You cannot instruct us to deduct the loan
or payment from specific Indexed Accounts or the Fixed Account. When we apply the Policy Deduction Method, the sum of the values in an Indexed Account and its associated Holding Account is considered one proportion. The corresponding proportional amount is subtracted first from the Holding Account until it has been reduced to zero and then any remaining amount is subtracted from the associated Indexed Account.
You may obtain
your Interim Segment Value on any Business Day by calling us at 1-800-882-1292 or by accessing
our website at www.brighthousefinancial.com. However, Interim Segment Values fluctuate daily, and
the current value(s) quoted may differ from the actual value(s) calculated.
This is the positive or negative return we add to the Segment Value amount to determine the Interim Segment Value. The Accrued Index Return is equal to the current Segment Value multiplied by the Segment Performance Rate. The Accrued Index Return can be positive, zero or negative. If the negative Segment Index Performance is constant during the Segment Term, any negative interest we calculate on an Interim Segment Value calculation date when negative Segment Index Performance exceeds the Buffer Rate will be greater than it would be on the Segment Maturity Date because the Buffer Rate, except for the Buffer 100, is lower earlier in the Segment Term and does not fully accrue until the Segment Maturity Date. The Buffer 100 is always fully accrued. If positive Segment Index Performance is constant during the Term, any positive interest we calculate on an Interim Segment Value calculation date when positive Segment Index Performance exceeds the Cap Rate will be lower than it would be on the Segment Maturity Date because the Cap Rate lower earlier in the Segment Term and does not fully accrue until the Segment Maturity Date.
The Accrued Buffer Rate is the portion of the Buffer Rate that has accrued from the Segment Start Date to any day within the Segment Term. This is the amount that may be applied in calculating the Interim Segment Value on any day prior to the Segment Maturity Date if Segment Index Performance is less than zero. The Accrued Buffer Rate is equal to the Buffer Rate multiplied by the number of days elapsed since the Segment Start Date, divided by the total number of days in the Segment Term. The portion of the Buffer Rate that applies increases as you get closer to the Segment Maturity Date.
The Accrued Cap Rate is the portion of the Cap Rate that has
accrued from the Segment Start Date to any day within the Segment Term. This is the maximum Segment Index Performance that may be applied in calculating the Interim Segment
Value on any day prior to the Segment Maturity Date if Segment Index Performance is equal to or greater than zero. The Accrued Cap Rate is equal to the Cap Rate multiplied by the number of days elapsed since the Segment Start Date, divided by the total number of days in the Segment Term. The portion of the Cap Rate that applies increases as you get closer to the Segment Maturity Date.
Segment Performance Rate for Determination of Interim Segment
Value
The Segment Performance Rate during a particular Segment Term is the Segment Index Performance, adjusted for the applicable Accrued Buffer Rate or Accrued Cap Rate.
As noted above, the Interim Segment Value is calculated on each
Business Day between the Segment Start Date and prior to the Segment Maturity Date using accrued values for the Buffer Rate and Cap Rate. For example, if you have an Indexed Account with a 1-Year Segment Term, a Buffer 10 and a 10% Cap Rate, the Interim Segment Value halfway through the Segment Term will be calculated using your Accrued Buffer Rate of 5% and Accrued Cap Rate of 5%.
The accrued rates are calculated as follows:
The Buffer Rate (10%) is multiplied by the number of days elapsed
since the Segment Start Date (183) and divided by the total number of days in the Segment Term (365), so the Accrued Buffer Rate is 5%.
The Cap Rate (10%) is multiplied by the number of days elapsed since the Segment Start Date (183) and divided by the total number of days in the Segment Term (365), so the Accrued Cap Rate is 5%.
Example 2—Calculating your Interim
Segment Value
Examples 2A and 2B are intended to show how an Interim Segment Value is calculated. We calculate an Interim Segment Value on each Business Day between the Segment Start Date and prior to the Segment Maturity Date. An Interim Segment Value calculation is used to determine how much is available for death benefits (including Policy Proceeds and an Accelerated Death Benefit payment), loans (not including loans in connection with Distribution Payments under the GDR), transfers from Indexed Account Cash Value to the Fixed Account if you choose to start (or restart) Distribution Payments under the GDR, and Surrenders (including Surrenders in connection with the Free Look Period). If you choose to start (or restart) Distribution Payments on any day other than a Policy Anniversary, any Indexed Account Cash Value transferred to the Fixed Account will be based on Interim Segment Value. In both examples, assume Owner 1 allocates her $51,000 of Net Premiums
to an Indexed Account
with a 1-Year Segment Term / Buffer 10/ S&P 500® Index
with a Cap Rate of 10%. Her Segment Value on the Segment Start Date is $51,000 (before deducting the Annual Deduction). Example 2A will illustrate an Interim
Segment Value calculation with positive Segment Index Performance and Example 2B will illustrate an Interim Segment Value calculation with negative Segment Index Performance. For purposes of these examples, the Interim Segment Value calculation occurs exactly halfway through the Segment Term.
To see how a loan reduces the Interim Segment Value, dollar for
dollar, and how we calculate Segment Value on a Segment Maturity Date reflecting the impact of an Interim Segment Value calculation resulting from a loan that is not a
Distribution Payment, see “LOANS” and Examples 4B and 4C.
Example 2A—Positive Segment
Index Performance:
| |
Segment Value (before deducting the Annual Deduction)(1) |
|
Segment Value (after deducting the Annual Deduction)(1) |
|
| |
|
| |
|
Closing Value of the Index |
|
Interim Segment Value Calculation Halfway Through
Term |
Closing Value of the Index |
|
Segment Index Performance(2) |
|
| |
|
Segment Performance Rate(4) |
|
| |
|
| |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
On the Policy Start Date and each Policy Anniversary thereafter, we deduct the
charges for the Annual Deduction from your Cash Value. The Annual Deduction for each Policy Year will be taken from any Indexed Account according to the Policy Deduction Method. For purposes of this example, assume the Annual Deduction is $1,000.
(2)
Segment Index Performance is equal to the percentage change in the Closing Value of the Index measured from the
Segment Start Date to the date of the Interim Segment Value calculation. Segment Index Performance is calculated as follows:
(600 [Closing Value of the Index on date of Interim Segment Value
calculation]
÷ 500 [Closing Value of the Index at Segment Start Date]) – 1 = 20%
(3)
The Accrued Cap Rate is equal to the Cap Rate multiplied by the number of days
elapsed since the Segment Start Date divided by the total number of days in the Segment Term. The Accrued Cap Rate is calculated as follows:
10% [Cap Rate] x 183 [number of days elapsed since the Segment Start Date]
÷ 365 [total number of days in the Segment Term] = 5%
(4)
The Segment Performance Rate is equal to the Accrued Cap Rate because it cannot
exceed the Accrued Cap Rate even though the Segment Index Performance was at 20% and the Cap Rate is 10%.
(5)
The Accrued Index Return is equal to the product of the current Segment Value
(Segment Value at the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) multiplied by the Segment Performance Rate. The Accrued Index Return is calculated as follows:
$50,000 [current Segment Value] x 5% [Segment Performance Rate] = $2,500
(6)
The Interim Segment Value is equal to the current Segment Value (Segment Value at
the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) plus the Accrued Index Return. The Interim Segment Value is calculated as follows:
$50,000 [current Segment
Value] + $2,500 [Accrued Index Return] = $52,500
Example
2B—Negative Segment Index Performance:
| |
Segment Value (before deducting the Annual Deduction)(1) |
|
Segment Value (after deducting the Annual Deduction)(1) |
|
| |
|
| |
|
Closing Value of the Index |
|
Interim Segment Value Calculation Halfway Through
Term |
Closing Value of the Index |
|
Segment Index Performance(2) |
|
| |
|
Segment Performance Rate(4) |
|
| |
|
| |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
On the Policy Start Date and each Policy Anniversary thereafter, we deduct the
charges for the Annual Deduction from your Cash Value. The Annual Deduction for each Policy Year will be taken from any Indexed Account according to the Policy Deduction Method. For purposes of this example, assume the Annual Deduction is $1,000.
(2)
Segment Index Performance is equal to the percentage change in the Closing Value of the Index measured from the
Segment Start Date to the date of the Interim Segment Value calculation. Therefore, the Segment Index Performance is calculated as follows:
(400 [Closing Value of the Index on date of Interim Segment Value
calculation]
÷ 500 [Closing Value of the Index at Segment Start Date]) – 1 = –20%
(3)
The Accrued Buffer Rate is equal to the Buffer Rate multiplied by the number of
days elapsed since the Segment Start Date divided by the total number of days in the Segment Term. The Accrued Buffer Rate is calculated as follows:
10% [Buffer Rate] x 183 [number of days elapsed since the Segment Start Date]
÷ 365 [total number of days in the Segment Term] = 5%
(4)
The Segment Performance Rate is –15% because the Segment Index Performance
is –20% and the Accrued Buffer Rate of 5% absorbs up to 5% of the negative Segment Index Performance even though the Buffer Rate is 10%.
(5)
The Accrued Index Return is equal to the product of the current Segment Value
(Segment Value at the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) multiplied by the Segment Performance Rate. The Accrued Index Return is calculated as follows:
$50,000 [current Segment Value] x –15% [Segment Performance Rate] = –$7,500
(6)
The Interim Segment Value is equal to the current Segment Value (Segment Value at
the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) plus the Accrued Index Return. The Interim Segment Value is calculated as follows:
$50,000 [current Segment
Value] + –$7,500 [Accrued Index Return] = $42,500
You can transfer all or a portion of your unloaned Cash Value to
or from the Fixed Account and/or to or from the Indexed Account, subject to the restrictions and requirements stated below. If you have elected automatic Cash Value
rebalancing, transfers will be made in accordance with your current specified percentages, unless the election is terminated. See “AUTOMATIC CASH VALUE REBALANCING.”
Transfer to and from the Fixed Account. The amounts transferred to the Fixed Account must remain in the Fixed Account for one (1) year and can only
be transferred on the Policy Anniversary. Under our current administrative procedures, we will also allow you to make transfers to and from the Fixed Account until the end
of the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary.
Transfer to and from the Indexed Accounts if You are Not Receiving Distribution Payments
Under the GDR. If Distribution Payments have not started or have been voluntarily suspended or
terminated or the GDR is no longer in effect, you may transfer all or a portion of any unloaned Cash Value between the Fixed Account and the Indexed Accounts. The amount
will be transferred on the next Policy Anniversary. Transfers will be made in accordance with the latest instructions on file with us. If you wish to change those instructions, you have to notify us of your election to transfer. The request to transfer must be received at our Administrative Office.
See “REQUESTS AND ELECTIONS.” Under our current administrative procedures, we will allow you to make transfers or change your allocation
instructions until the end of the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary.
Please note, any premium received during the Transfer Period will be allocated directly to the Indexed Accounts according to your instructions as if it had been received on the Policy Anniversary. In addition, on a Policy Anniversary, any amount in a Holding Account will be automatically transferred to its associated Indexed Account. If the associated Indexed Account is no longer available on the Policy Anniversary, the Holding Account Cash Value will automatically transfer into the Fixed Account. Your financial representative can provide more information, or you may contact our Administrative Office. After the Transfer Period, you cannot make transfers until the next Policy Anniversary.
At the Segment Maturity
Date, the Segment Value allocated to the Indexed Account will automatically be renewed into the same Indexed Account unless you have elected the automatic
Cash Value rebalancing program or notify us, before the end of the Transfer Period, to transfer into a different Indexed Account or the Fixed
Account. The request to transfer must be received at our Administrative Office before the end of
the Transfer Period. See “REQUESTS AND ELECTIONS.” If the same Indexed Account with the same Segment is no longer available at the Segment Maturity Date, the
Segment Value in the applicable Segment will automatically transfer into the Fixed Account.
Thirty (30) days before the Segment Maturity Date, we will mail you a notification identifying your current Indexed Account allocations, including any Holding Accounts, and indicating all Indexed Accounts and Indexed Account Factors that will be available on your Policy Anniversary. See “CAP RATE.” You may also obtain the new Cap Rates by accessing the Company’s website at https://www.brighthousefinancial.com/products/rates/ where at least two months of renewal Cap Rates are posted – i.e., for the current month and the
following month. You have to notify us if you want to transfer some or all of your Segment Value to a new Indexed Account or to the Fixed Account. The request to transfer must be received at our Administrative
Office. See “REQUESTS AND ELECTIONS.” Under our current administrative procedures, we will also allow you to make transfers to and from the Indexed Accounts until the end of the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary.
Renewals. For renewals into the same Indexed Account, a new Cap Rate will go into effect on the Policy Anniversary that
coincides with the new Segment Start Date.
Transfer Requirements for Indexed Accounts While
Distribution Payments are Voluntarily Suspended or Terminated Under the GDR. If
Distribution Payments are suspended or terminated, you may transfer any Cash Value in the Fixed Account to any of the available Indexed Accounts. You may request to change
the allocation of Cash Value among the Fixed Account and the Indexed Accounts. The request must be received at our Administrative Office and will take effect on the next Policy Anniversary. See “REQUESTS AND ELECTIONS.” Under our current administrative procedures, we will also allow you to make transfers until the end of the Transfer Period, and we will treat the transfer as if it occurred on the Policy Anniversary.
Once you start Distribution Payments under the
GDR, all of your unloaned Cash Value will be in the Fixed Account, and you may not transfer to the Indexed Accounts while receiving Distribution
Payments.
Example 3 is intended to show how transfers work. Owner 1 allocates her $51,000 of Net Premiums to an Indexed Account with a 1 Year Segment Term / Buffer 10 / S&P 500® Index with a Cap Rate of 10%. Her Segment Value on the Segment Start Date is $51,000 (before deducting the
Annual Deduction). At the end of the 1 Year Segment Term, she transfers 50% of her Segment Value into an Indexed Account with a 1 Year Segment Term / Buffer 10 / Russell
2000® Index with a Cap Rate of 12% and opts to let the remaining 50% of her Segment Value automatically renew. For purposes of the examples, assume there is no Cash Value in the Holding Accounts associated with the Indexed Accounts.
Indexed Accounts prior to Transfer:
| |
|
| |
Segment Value (before deducting the Annual Deduction)(1) |
|
Segment Value (after deducting the Annual Deduction)(1) |
|
Closing Value of the Index |
|
| |
Closing Value of the Index |
|
Segment Index Performance(2) |
|
| |
|
| |
|
Segment Performance Rate (one year)(3) |
|
| |
|
| |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
On the Policy Start Date and each Policy Anniversary thereafter, we deduct the
charges for the Annual Deduction from your Cash Value. The Annual Deduction for each Policy Year will be taken from any Indexed Account according to the Policy Deduction Method. For purposes of this example, assume the Annual Deduction is $1,000.
(2)
Segment Index Performance is equal to the percentage change in the Closing Value of the Index measured from the
Segment Start Date to the Segment Maturity Date. Segment Index Performance is calculated as follows:
(1,200 [Closing Value of the Index at Segment Maturity Date]
÷
1,000 [Closing Value of the Index at Segment Start Date]) – 1 = 20%
(3)
Since Segment Index Performance is greater than zero and exceeds the Cap Rate, the
Segment Performance Rate equals the Cap Rate.
(4)
The Segment Credit is equal to the product of the current Segment Value (Segment Value at the Segment Start Date
adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) multiplied by the Segment Performance Rate. The Segment Credit is calculated as follows:
$50,000 [current
Segment Value] x 10% [Segment Performance Rate] = $5,000
(5)
The Segment Value on the Segment Maturity Date is equal to the current Segment
Value (Segment Value at Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) plus the Segment Credit. The Segment Value on the Segment Maturity Date is calculated as follows:
$50,000 [current Segment Value] + $5,000 [Segment Credit] = $55,000
Indexed Accounts after Transfer:
| |
|
| |
1-Year Term / Buffer 10 / S&P 500® Index with a Cap Rate of 10% |
1-Year Term / Buffer 10 / Russell
2000® Index with a Cap Rate of 12% |
Segment Value at Segment Start Date
(second term)(1) |
|
|
Notes to the table above.
(1)
The Segment Value at Segment Maturity Date is reallocated so that 50% is renewed
in the same Indexed Account and 50% is allocated to a new Indexed Account.
AUTOMATIC CASH VALUE REBALANCING PROGRAM
If you elect the automatic Cash Value rebalancing program, we will automatically reset your unloaned Cash allocated to each Indexed Account and the Fixed Account to percentage levels that you request. If you elect this program, we will transfer amounts among the Indexed Accounts and the Fixed Account necessary to “rebalance” the Cash Value to your specified percentages. Once you elect this program, the automatic rebalancing will occur on every Policy Anniversary.
An automatic Cash Value rebalancing program is intended to transfer unloaned Cash Value from those accounts that have increased in value to those that have declined or not increased as much in value. Over time, this method of allocating may help you “buy low and sell high,” although there can be no assurance that this objective will be achieved. Automatic Cash Value rebalancing does not guarantee profits, nor does it assure that you will not have
losses.
For example, assume that you want your initial Net Premium split between two Indexed Accounts. You want 40% to be in Indexed Account “A” and 60% to be in Indexed Account “B.” Hypothetically, over the next year Indexed Account “A” does very well while Indexed Account “B” performs poorly. On the Segment Maturity Date, Indexed Account “A” now represents 50% of your Cash Value because of the interest that was credited. If you have elected automatic Cash Value rebalancing, we will bring back the Indexed Account Cash Value in Indexed Account “A” back to 40% by transferring amounts to Indexed Account “B,” thus increasing its Indexed Account Cash Value to 60%.
If you submit a subsequent premium payment, the Net Premium
will be allocated to the Indexed Accounts (or the associated Holding Accounts if outside the Transfer Period) and Fixed Account in accordance with your current specified
percentages. You cannot allocate or make transfers to or from the Fixed Account and/or to or from the Indexed Accounts on a basis other than the specified percentages if you have elected the automatic Cash Value rebalancing program. Automatic Cash Value rebalancing will remain in effect until we receive your written termination request in Good Order. We will terminate the program once you start Distribution Payments under the GDR. We reserve the right to end the automatic Cash Value rebalancing program by sending you one month’s notification.
You may borrow money from your Policy by taking a loan. A loan reduces the Policy’s Cash Value in the Indexed Accounts, Holding Accounts, and the Fixed Account and may increase your risk of Policy lapse. Policy Proceeds payable will also be reduced by the amount of any Policy Loan Balance. Loans may have tax consequences.
There are two ways to take a loan: (1) a
loan, which is available as long as your Policy has Loan Value and (2) a Distribution Payment or the One-time Payment, which is available through the GDR. After the Policy
has been in force for at least ten years, you are eligible to exercise the GDR. The Policy cannot be a MEC, and you must repay any Policy Loan Balance before starting Distribution Payments.
Loans that are not Distribution Payments under the GDR
Note: The provisions in this sub-section do not apply to Distribution Payments under the GDR. See “GUARANTEED DISTRIBUTION RIDER” for a complete description of the terms, conditions, and limitations associated with Distribution Payments and the GDR.
If your Policy has Loan Value, you may borrow from your
Policy at any time, by submitting a request. Although you can call our Administrative Office at any time to determine what is available for a loan, the maximum amount you
may borrow (defined below as the Loan Value) will be calculated at the end of the Business Day when we process the loan. These amounts may be different. If you request a loan that exceeds the Loan Value, your request will not be considered in Good Order. We will contact you to let you know that your requested amount exceeds the Loan Value. We will not consider your request in Good Order unless you revise the loan request to an amount that is less than or equal to the Loan Value. The Loan Value on the date of the loan equals:
•
The Policy’s Cash Value times 90%, plus
•
Projected interest from the date of the loan request to the next Policy Anniversary
(calculated using the Fixed Account Guaranteed Minimum Interest Rate, Holding Account guaranteed minimum interest rate, and Loan Account guaranteed minimum interest rate); less
•
Any
Policy Loan Balance; less
•
Projected Loan Interest from the date of the loan request to the next Policy Anniversary.
This projection is equal to 90% of the Cash Value plus Fixed Account, Holding Account and Loan Account interest to the next Policy Anniversary,
multiplied by the Annual Maximum Fixed Loan Interest Rate multiplied by the
number of days to the next Policy Anniversary divided by the total number of days in the Policy Year; less
The Fixed Account Guaranteed Minimum Interest Rate, Holding Account guaranteed minimum interest rate for each Holding Account, and Loan Account guaranteed minimum interest rate that apply to your Policy can be found in the Policy specifications pages. The annual maximum fixed loan interest rate is 8%, but we may use a lower interest rate, which will be shown on the annual statement.
We make the loan as of the date when we receive a loan request
in Good Order. You may increase your risk of lapse if you take a loan. You should contact our Administrative Office or your financial representative for information on loan
procedures.
If your Policy has an Excess Loan, we will send a notification
to your last known address and that of any assignee of record. We grant you a Grace Period to pay the excess due. The Grace Period begins on the monthly anniversary
following the date we send you the Excess Loan notification. If the excess due remains unpaid at the end of the Grace Period, the Policy will terminate without value. The Grace Period will end 62 days from the date the notification is sent.
A loan reduces the Policy’s Cash Value in the Indexed Accounts, Holding Accounts, and the Fixed Account by the amount of the loan. We attribute loans to the Indexed Accounts, Holding Accounts, and the Fixed Account in accordance with the Policy Deduction Method. You cannot instruct us to deduct the loan or payment from specific Indexed Accounts or the Fixed Account. When we apply the Policy Deduction Method, the sum of the values in an Indexed Account and its associated Holding Account is considered one proportion. The corresponding proportional amount is subtracted first from the Holding Account until it has been reduced to zero and then any remaining amount is subtracted from the associated Indexed Account. When you take a loan, we transfer Cash Value equal to the amount of the loan from the Indexed Accounts, Holding Accounts, and the Fixed Account to the Loan Account (which is part of our General Account) to serve as collateral for the loan being taken.
If you are allocated to an Indexed Account and take a loan on any day other than a Policy Anniversary, the amount withdrawn for the loan will reduce the current Segment Value for each Segment by the same percentage that the loan reduces the Interim Segment Value of such Segment. Accordingly, when negative Segment Index Performance has caused the Interim Segment Value to be less than the current Segment Value, taking a loan may cause the current Segment Value to be reduced by a greater amount than the Interim Segment Value is reduced. On the other hand, when positive Segment Index Performance has caused the Interim Segment Value to be greater than the current Segment Value, the current Segment Value will be reduced by a lesser amount than the Interim Segment Value is reduced. The remaining Segment Value after the loan will be used as the new Segment Value for the
remainder of the Segment Term or until you take another loan or request an Accelerated Death Benefit payment.
The amount transferred from the Indexed Accounts to the Loan Account does not participate in the Indexed Accounts, which means the Cash Value in the Loan Account is not subject to potential positive Index performance. Therefore, loans can permanently affect the Policy Proceeds and Cash Value of the Policy, even if repaid. In addition, we reduce any Policy Proceeds payable under a Policy by the Policy Loan Balance, which includes interest.
Loan Value is the maximum amount you may borrow from your Policy at any time. Example 4A is intended to show how Loan Value is calculated for loans that are not Distribution Payments. For purposes of calculating Loan Value, we project, to the next Policy Anniversary, the interest that you could earn and that we could charge (the Loan Interest). This is only a projection and is not what will actually be earned or charged if you were to take a loan. See “Interest” below for more information on the maximum Loan Interest rate and the minimum Loan Account interest rate.
Assume an existing Policy Loan Balance of
$10,000 and a Cash Value of $50,000, which has been allocated among the Fixed Account, an Indexed Account, (with a portion in the Holding Account until the next Policy
Anniversary), and the Loan Account. Assume a Surrender charge of $2,000 would apply upon a full Surrender or Lapse. For purposes of these examples, assume the Loan Value is calculated exactly halfway through the Segment Term.
In order to show how we calculate Loan Value in Example 4A
when you already have an existing loan, we have to show both Policy Loan Balance and the Loan Account Cash Value. The Policy Loan Balance is an amount equal to the
outstanding loan amounts plus accrued Loan Interest (interest we charge you for taking a loan, which accrues daily). The Loan Account Cash Value is the amount of Cash Value that was transferred from the Indexed Accounts, Holding Account, and/ or Fixed Account when the loan was taken and also includes the Loan Account interest (interest we credit you daily on the Cash Value in the Loan Account). On the Policy Anniversary, the Loan Account Cash Value will be adjusted to reflect the loan interest
spread (the difference
between the unpaid interest we charge you and the interest we credited you). When the Loan Interest is greater than the Loan Account interest, the Policy Loan Balance will
be greater than the Loan Account Cash Value.
Cash Value Allocations Halfway Through Policy Year
|
| |
|
Indexed Account Cash Value |
|
Holding Account Cash Value |
|
| |
|
| |
|
Loan Value Calculation Halfway Through Policy Year
|
| |
|
Projected Fixed Account interest to the next Policy Anniversary(3) |
|
Projected Holding Account interest to the next Policy Anniversary(4) |
|
Projected Loan Account interest to the next Policy Anniversary(5) |
|
| |
|
Projected Loan Interest to the next Policy Anniversary(6) |
|
| |
|
| |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
Cash Value is equal to the total of the Fixed Account, Indexed Account, Holding
Account and Loan Account cash values. Cash Value is calculated as follows:
$15,000 [Fixed Account Cash Value] + $20,500 [Indexed Account Cash Value]
+ $5,000 [Holding Account Cash Value] + $9,500 [Loan Account Cash Value] = $50,000
(2)
90% of the Cash Value is calculated as follows:
90% x $50,000 [Cash Value]
= $45,000
(3)
Projected Fixed Account interest to the next Policy Anniversary is equal to 90% of
the Fixed Account Cash Value multiplied by the Fixed Account Guaranteed Minimum Interest Rate multiplied by the number of days to the next Policy Anniversary divided by the total number of days in the Policy Year. The projected Fixed Account interest to the next Policy Anniversary is calculated as follows:
90% x $15,000 [Fixed Account Cash Value] x 1% [Fixed Account
Guaranteed Minimum Interest Rate]
x (183 [days to the next Policy Anniversary] ÷ 365) = $67
(4)
Projected Holding Account interest to the next Policy Anniversary is equal to 90%
of the Holding Account Cash Value multiplied by the Holding Account guaranteed minimum interest rate multiplied by the number of days to the next Policy Anniversary divided by the total number of days in the Policy Year. The projected Holding Account interest to the next Policy Anniversary is calculated as follows:
90% x $5,000 [Holding
Account Cash Value] x 1% [Holding Account guaranteed minimum interest rate]
x (183 [days to the next Policy Anniversary] ÷ 365) = $22
(5)
Projected Loan Account interest to the next Policy Anniversary is equal to 90% of
the Loan Account Cash Value multiplied by the Loan Account guaranteed minimum interest rate multiplied by the number of days to the next Policy Anniversary divided by the total number of days in the Policy Year. The projected Loan Account interest to the next Policy Anniversary is calculated as follows:
90% x $9,500 [Loan Account Cash Value] x 1% [Loan Account guaranteed
minimum interest rate]
x (183 [days to the next Policy Anniversary] ÷ 365) = $42
(6)
Projected Loan Interest to the next Policy Anniversary is equal to 90% of the Cash
Value plus Fixed Account, Holding Account and Loan Account interest to the next Policy Anniversary, multiplied by the Annual Maximum Fixed Loan Interest Rate multiplied by the number of days to the next Policy Anniversary divided by the total number of days in the Policy Year. The projected Loan interest to the next Policy Anniversary is calculated as follows:
($45,000 [90% of Cash Value] + $67 [projected Fixed Account interest to the next Policy Anniversary]
+ $22 [projected Holding Account interest to the next Policy Anniversary]
+ $42 [projected Loan Account
interest to the next Policy Anniversary]) x 8% [Annual Maximum Fixed Loan Interest
Rate]
x (183 [days to the next Policy Anniversary] ÷ 365) = $1,810
(7)
The Loan Value is equal to 90% of the Cash Value plus projected Fixed Account,
Holding Account and Loan Account interest to the next Policy Anniversary less Loan Balance less projected Loan Interest to the next Policy Anniversary less Surrender charge. The Loan Value is calculated as follows:
$45,000 [90% of Cash
Value] + $67 [projected Fixed Account interest to the next Policy Anniversary]
+ $22 [projected Holding Account interest to the next Policy Anniversary]
+ $42 [projected Loan Account interest to the next Policy Anniversary] – $10,000 [Loan Balance]
– $1,810 [projected Loan Interest to the next Policy Anniversary] – $2,000 [Surrender charge] = $31,321
(Applies to all loans, including Distribution Payments and the
One-time Payment under the GDR.)
You may repay all or part of your loan at any time while the Insured is still alive. Any loan repayment must be at least $50 unless you are paying the entire Policy Loan Balance. When you make a loan repayment, the portion of the loan repayment that is not Loan Interest will be transferred from the Loan Account to the Fixed Account or the Holding Accounts, according to your latest premium allocation instruction on file with us.
If a loan is outstanding, it may be better to repay the loan than
to pay a premium, because the premium payment is subject to the Percent of Premium Charge, and the loan repayment is not subject to this charge. If you have a loan and we
receive a payment, any payment we receive will be applied as a loan repayment unless it is clearly marked as a premium payment. Loans and Loan Interest also reduce any Policy Proceeds.
A loan that is taken from, or secured by, a Policy may have tax
consequences. Although the issue is not free from doubt, we believe that a loan from or secured by a Policy that is not classified as a MEC should generally not be treated
as a taxable distribution. A tax adviser should be consulted when considering a loan.
(Applies to all loans, including Distribution Payments and the
One-time Payment under the GDR.)
We charge Loan Interest on loans, and you earn interest on the Cash Value in the Loan Account.
The Loan Interest we charge on the loan is subject to the annual maximum fixed loan interest rate (8%), and the interest you earn is subject to the Loan Account guaranteed minimum interest rate (not less than 1%).
Loan Interest accrues daily based on the
Policy Loan Balance and is due and payable annually on each Policy Anniversary. Such interest is calculated using compound interest at the annual maximum fixed loan interest
rate. The annual maximum fixed loan interest rate is 8%, but we may use a lower interest rate, which will be shown on the annual statement. If not paid when due, we add the interest accrued to the loan amount, and we transfer an amount of Cash Value equal to the unpaid interest from the Indexed Accounts and the Fixed Account to the Loan Account in the same manner as a new loan. We may use a lower interest rate, which will be shown on the annual statement.
Cash Value in the Loan Account earns interest daily, and
the earned interest is transferred on each Policy Anniversary to the Indexed Accounts and to the Fixed Account, according to your latest allocation instructions on file with
us. Earned interest is calculated using compound interest, and we can change the interest rate at any time. The current Loan Account guaranteed minimum interest rate for any Policy we offer will not be less than 1%. The Loan Account guaranteed minimum interest rate that applies to your Policy may be higher and can be found in the Policy specifications
pages.
Because Loan Interest accrues daily at an annual rate not more than the annual maximum fixed loan interest rate of 8%, and we credit interest on the Cash Value in Loan Account at a rate not less than the Loan Account guaranteed minimum interest rate of 1%, the loan interest spread will never be more than 7%.
If the Loan Interest causes your Policy
Loan Balance to exceed the Cash Value, less any Surrender charge, you will have an Excess Loan. We will notify you and any assignee of record of an Excess
Loan, and if you do not repay the Excess Loan within the Grace Period, your Policy will lapse.
Example 4B and 4C—How Loans Impact Interim Segment Value and Segment Value on a Segment Maturity Date
Examples 4B and 4C are intended to show how loans that are not Distribution Payments impact Interim Segment Value and subsequently, Segment Value on a Segment Maturity Date. In both examples, assume Owner 1 allocates her $51,000 of Net Premiums to an Indexed Account with a 1-Year Segment Term / Buffer 10 / S&P 500® Index with a Cap Rate of 10%. Her Segment Value on the Segment Start Date is $51,000 (before deducting the Annual Deduction). Example 4B will illustrate one
loan and an Interim
Segment Value calculation with positive Segment Index Performance. Example 4C will illustrate two loans and Interim Segment Value calculations with negative
Segment Index Performance. For purposes of example 4B, assume the loan is taken exactly halfway through the Segment Term and that there have been no other
transactions (such as other loans or an Accelerated Death Benefit payment) as of the date the Interim Segment Value in the example is calculated. For purposes
of Example 4C, assume the first loan is taken exactly halfway through the Segment Term and the second loan is taken 9 months into the Segment Term. Assume there have been no other transactions (such as other loans or an Accelerated Death Benefit payment) as of the date the Interim Segment Value is calculated for the first loan.
Although not shown in the example, when a loan is
taken, an amount equal to the loan is transferred from the Indexed Accounts, Holding Accounts, and the Fixed Account to the Loan Account to serve as collateral for the loan.
The loan amount will be taken from the Indexed Accounts, Holding Accounts, and the Fixed Account in accordance with the Policy Deduction Method.
Example 4B—Positive Segment Index
Performance:
| |
Segment Value (before deducting the Annual Deduction)(1) |
|
Segment Value (after deducting the Annual Deduction)(1) |
|
| |
|
| |
|
Closing Value of the Index |
|
Interim Segment Value Calculation Halfway Through
Term |
Closing Value of the Index |
|
Segment Index Performance(2) |
|
| |
|
Segment Performance Rate(4) |
|
| |
|
| |
|
| |
|
Interim Segment Value adjusted by loan amount(7) |
|
Segment Value adjusted by loan amount(8) |
|
| |
Closing Value of the Index |
|
Segment Index Performance(9) |
|
Segment Performance Rate(10) |
|
| |
|
| |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
On the Policy Start Date and each Policy Anniversary thereafter, we deduct the
charges for the Annual Deduction from your Cash Value. The Annual Deduction for each Policy Year will be taken from any Indexed Account according to the Policy Deduction Method. For purposes of this example, assume the Annual Deduction is $1,000.
(2)
Segment Index Performance is equal to the percentage change in the Index Value measured from the Segment Start Date to the date of the Interim Segment Value calculation. Segment Index Performance is calculated as follows:
(600 [Closing Value of the Index on date of Interim Segment Value calculation]
÷ 500 [Closing Value of the Index at Segment Start Date]) – 1 = 20%
(3)
The Accrued Cap Rate is equal to the Cap Rate multiplied by the number of days elapsed since the Segment Start Date divided by the total number of days in the Term. The Accrued Cap Rate is calculated as
follows:
10% [Cap Rate] x 183 [number of days elapsed since Segment Start Date]
÷ 365 [total number of days in the Term] = 5%
(4)
The Segment Performance Rate is equal to the Accrued Cap Rate because it cannot exceed the Accrued Cap Rate even
though Segment Index Performance was at 20%.
(5)
The Accrued Index Return is equal to the product of the current Segment Value (Segment Value at the Segment Start Date adjusted for any loans or Accelerated Death Benefit payment; no adjustments so far) multiplied by the Segment
Performance Rate. The Accrued Index Return is calculated as follows:
$50,000 [current Segment Value] x 5% [Segment Performance Rate] = $2,500
(6)
The Interim Segment Value is equal to the current Segment Value (Segment Value at
the Segment Start Date adjusted for any loans or Accelerated Death Benefit payment; no adjustments so far) plus the Accrued Index Return. The Interim Segment Value is calculated as follows:
$50,000 [current Segment
Value] + $2,500 [Accrued Index Return] = $52,500
(7)
Interim Segment Value adjusted for the loan amount is equal to Interim Segment
Value ($52,500) minus the amount of the loan ($20,000).
(8)
The Segment Value is reduced proportionally by the loan taken based on the reduction in Interim Segment Value.
Therefore, the Segment Value adjusted by the loan taken is calculated as
follows:
$50,000 [Segment Value on date of Interim Segment Value calculation]
x
(1-($20,000 [loan taken halfway through the Term] ÷ $52,500 [Interim Segment Value on date of loan])) = $30,952
The proportionally reduced Segment Value is used as the new Segment
Value for the remainder of the Segment Term or until you take another loan or request an Accelerated Death Benefit payment.
(9)
Segment Index Performance at Segment Maturity is equal to the percentage change in
the Index Value measured from the Segment Start Date to the Segment Maturity Date. Segment Index Performance is calculated as follows:
(700 [Closing Value of the Index at Segment Maturity Date]
÷ 500
[Closing Value of the Index at Segment Start Date]) – 1 = 40%
(10)
Segment Index Performance at Segment Maturity exceeds the Cap Rate and therefore
the Segment Performance Rate at Segment Maturity is equal to the Cap Rate.
(11)
The Segment Credit on the Segment Maturity Date is equal to the product of the current Segment Value (Segment Value at the Segment Start Date adjusted for the loan that was taken halfway through the Segment Term) multiplied by the Segment Performance Rate at Segment Maturity. The Segment Credit on the Segment Maturity Date is calculated as
follows:
$30,952 [current Segment Value] x 10% [Segment Performance Rate at Segment
Maturity Date] = $3,095
(12)
The Segment Value on the Segment Maturity Date is equal to the current Segment
Value (Segment Value at the Segment Start Date adjusted for the loan that was taken halfway through the Segment Term) plus the Segment Credit at Segment Maturity. The Segment Value on the Segment Maturity Date is calculated as follows:
$30,952 [current Segment Value] + $3,095 [Segment Credit] = $34,047
Example
4C—Negative Segment Index Performance:
| |
Segment Value (before deducting the Annual Deduction)(1) |
|
Segment Value (after deducting the Annual Deduction)(1) |
|
| |
|
| |
|
Closing Value of the Index |
|
Interim Segment Value Calculation Halfway Through
Term |
Closing Value of the Index |
|
Segment Index Performance(2) |
|
| |
|
Segment Performance Rate(4) |
|
| |
|
| |
|
| |
|
Interim Segment Value adjusted by loan amount(7) |
|
Segment Value adjusted by loan amount(8) |
|
Interim Segment Value Calculation 9 Months Through
Term |
Closing Value of the Index |
|
Segment Index Performance(9) |
|
| |
|
Segment Performance Rate(11) |
|
| |
|
Interim Segment Value(13) |
|
| |
|
Interim Segment Value adjusted by loan amount(14) |
|
Segment Value adjusted by loan amount(15) |
|
| |
Closing Value of the Index |
|
Segment Index Performance(16) |
|
Segment Performance Rate(17) |
|
| |
|
| |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
On the Policy Start Date and each Policy Anniversary thereafter, we deduct the
charges for the Annual Deduction from your Cash Value. The Annual Deduction for each Policy Year will be taken from any Indexed Account according to the Policy Deduction Method. For purposes of this example, assume the Annual Deduction is $1,000.
(2)
Segment Index Performance is equal to the percentage change in the Index Value measured from the Segment Start Date to the date of the Interim Segment Value calculation. Segment Index Performance is calculated as follows:
(400 [Closing Value of the Index on date of Interim Segment Value calculation]
÷ 500 [Closing Value of the Index at Segment Start Date]) – 1 = –20%
(3)
The Accrued Buffer Rate is equal to the Buffer Rate multiplied by the number of days elapsed since the Segment Start Date divided by the total number of days in the Term. The Accrued Buffer Rate is calculated as follows:
10% [Buffer Rate] x 183 [number of days elapsed since Segment Start Date]
÷ 365 [total number of days in the Term] = 5%
(4)
The Segment Performance Rate is –15% because the Segment Index Performance
is –20% and the Accrued Buffer Rate of 5% absorbs up to 5% of the negative Segment Index Performance.
(5)
The Accrued Index Return is equal to the product of the current Segment Value
(Segment Value at the Segment Start Date adjusted for any loans or Accelerated Death Benefit payment; no adjustments so far) multiplied by the Segment Performance Rate. The Accrued Index Return is calculated as follows:
$50,000 [current Segment
Value] x -15% [Segment Performance Rate] = –$7,500
(6)
The Interim Segment Value is equal to the current Segment Value (Segment Value at
the Segment Start Date adjusted for any loans or Accelerated Death Benefit payment; no adjustments so far) plus the Accrued Index Return. The Interim Segment Value is calculated as follows:
$50,000 [current Segment
Value] + –$7,500 [Accrued Index Return] = $42,500
(7)
Interim Segment Value adjusted for the loan amount is equal to Interim Segment
Value ($42,500) minus the amount of the loan ($20,000).
(8)
The Segment Value is reduced proportionally by the loan taken based on the reduction in Interim Segment Value.
Therefore, the Segment Value adjusted by the loan taken is calculated as
follows:
$50,000 [Segment Value on date of Interim Segment Value calculation]
x
(1-($20,000 [loan taken halfway through the Term] ÷ $42,500 [Interim Segment Value on date of loan])) = $26,471
The proportionally reduced Segment Value is used as the new Segment
Value for the remainder of the Segment Term or until you take another loan or request an Accelerated Death Benefit payment.
(9)
Segment Index Performance is equal to the percentage change in the Index Value
measured from the Segment Start Date to the date of the Interim Segment Value calculation. Segment Index Performance is calculated as follows:
(350 [Closing Value of the Index on date of Interim Segment Value calculation]
÷ 500 [Closing Value of the Index at Segment Start Date]) – 1 = –30%
(10)
The Accrued Buffer Rate is equal to the Buffer Rate multiplied by the number of days elapsed since the Segment Start Date divided by the total number of days in the Term. The Accrued Buffer Rate is calculated as follows:
10% [Buffer Rate] x 273 [number of days elapsed since Segment Start Date]
÷ 365 [total number of days in the Term] = 7.5%
(11)
The Segment Performance Rate is –22.5% because the Segment Index Performance
is –30% and the Accrued Buffer Rate of 7.5% absorbs up to 7.5% of the negative Segment Index Performance.
(12)
The Accrued Index Return is equal to the product of the current Segment Value
(Segment Value at the Segment Start Date adjusted for the loan that was taken halfway through the Segment Term) multiplied by the Segment Performance Rate. The Accrued Index Return is calculated as follows:
$26,471 [current Segment
Value] x -22.5% [Segment Performance Rate] = –$5,956
(13)
The Interim Segment Value is equal to the current Segment Value (Segment Value at
the Segment Start Date adjusted for the loan that was taken halfway through the Segment Term) plus the Accrued Index Return. The Interim Segment Value is calculated as follows:
$26,471 [current Segment Value] + –$5,956 [Accrued Index Return]
= $20,515
(14)
Interim Segment Value adjusted for the loan amount is equal to Interim Segment
Value ($20,515) minus the amount of the loan ($10,000).
(15)
The Segment Value is reduced proportionally by the loan taken based on the reduction in Interim Segment Value.
Therefore, the Segment Value adjusted by the loan taken is calculated as
follows:
$26,471 [Segment Value on date of Interim Segment Value calculation]
x
(1-($10,000 [loan taken halfway through the Term] ÷ $20,515 [Interim Segment Value on date of loan])) = $13,568
The proportionally reduced Segment Value is used as the new Segment
Value for the remainder of the Segment Term or until you take another loan or request an Accelerated Death Benefit payment.
(16)
Segment Index Performance at Segment Maturity is equal to the percentage change in
the Index Value measured from the Segment Start Date to the Segment Maturity Date. Segment Index Performance is calculated as follows:
(450 [Closing Value of the Index at Segment Maturity Date]
÷ 500
[Closing Value of the Index at Segment Start Date]) – 1 = –10%
(17)
The Segment Performance Rate at Segment Maturity is 0% because the Segment Index
Performance at Segment Maturity is –10% and the Buffer 10 absorbs up to 10% of the negative Segment Index Performance.
(18)
The Segment Credit on the Segment Maturity Date is equal to the product of the current Segment Value (Segment Value at the Segment Start Date adjusted for the loans that were taken during the Segment Term) multiplied by the Segment Performance Rate at Segment Maturity. The Segment Credit on the Segment Maturity Date is calculated as follows:
$13,568 [current Segment Value] x 0% [Segment Performance Rate at Segment Maturity Date] = $0
(19)
The Segment Value on the Segment Maturity Date is equal to the current Segment
Value (Segment Value at the Segment Start Date adjusted for the loans that were taken during the Segment Term) plus the Segment Credit at Segment Maturity. The Segment Value on the Segment Maturity Date is calculated as follows:
$13,568 [current Segment
Value] + $0 [Segment Credit] = $13,568
Your Policy’s total Cash Value includes any Cash Value in
the Fixed Account, Holding Accounts, Indexed Accounts, and the Loan Account.
Fixed Account Cash
Value. The Cash Value in the Fixed Account on the Policy Start Date equals the portion of the Net Premium received and allocated to the Fixed Account, less the portion of the
Annual Deduction charged to the Fixed Account.
The Cash Value in the Fixed Account on
a Policy Anniversary equals:
•
The Cash Value in the Fixed Account on the prior day; plus
•
Any Fixed Account interest credited on such amount since the prior day; plus
•
Any Net Premium paid on that date and allocated to the Fixed Account; plus
•
Any amount transferred from the Loan Account or an Indexed Account to the Fixed Account
on that date; less
•
Any amount transferred from the Fixed Account to an Indexed Account or the Loan Account
on that date; less
•
Any Cash Value reduction resulting from a payment under the Accelerated Death Benefit, on
that date; less
•
Any part of the Annual Deduction charged to the Fixed Account to cover the Policy Year
that starts on that day.
On any other day, the Cash Value in the Fixed Account equals:
•
The Cash Value in the Fixed Account on the prior day; plus
•
Any Fixed Account interest credited on such amount since the prior day; plus
•
Any Net Premium paid on that day and allocated to the Fixed Account; plus
•
Any amount transferred from the Loan Account to the Fixed Account on that day;
less
•
Any amount transferred from the Fixed Account to the Loan Account on that day;
less
•
Any Cash Value reduction resulting from a payment under the Accelerated Death
Benefit.
Holding Account Cash Value. The Cash Value in any Holding Account on the Policy Start Date equals zero.
The Cash Value in any Holding Account on a Policy Anniversary equals:
•
The Cash Value in the Holding Account on the prior day; plus
•
Any Holding Account interest credited on such amount since the prior day; plus
•
Any amount transferred from the Loan Account to the Holding Account on that date;
less
•
Any Cash Value reduction resulting from a payment under the Accelerated Death Benefit on
that date; less
•
Any part of the Annual Deduction charged to the Holding Account to cover the Policy Year
that starts on that day; less
•
Any amount transferred from the Holding Account to an Indexed Account or the Loan Account
on that date.
Note: Before the end of the day on a Policy
Anniversary, the Cash Value in any Holding Account could be greater than zero because of the first three bullets above. However, the Cash Value in any
Holding Account at the end of a Policy Anniversary will always equal zero.
On any other day, the Holding Account Cash Value equals:
•
The Cash Value in the Holding Account on the prior day; plus
•
Any Holding Account interest credited on such amount since the prior day; plus
•
Any
Net Premium paid on that date and allocated to the Holding Account; plus
•
Any amount transferred from the Loan Account to the Holding Account on that date;
less
•
Any amount transferred from the Holding Account to the Loan Account on that date;
less
•
Any Cash Value reduction resulting from a payment under the Accelerated Death
Benefit.
Loan Account Cash Value. The Cash Value in the Loan Account on the Policy Start Date equals zero.
The Cash Value in the Loan Account on any other day
equals:
•
The Cash Value in the Loan Account as of the prior day; plus
•
Any Loan Account interest credited on such amount since the prior day; plus
•
Any amount transferred from the Fixed Account, Holding Accounts, and Indexed Accounts to
the Loan Account on that day because a new loan was taken and/or, if on a Policy Anniversary, to cover any unpaid Loan Interest; less
•
Any amount transferred to the Fixed Account or to a Holding Account from the Loan Account
on that day.
Indexed Account Cash Value. The Cash Value of each Indexed Account is as follows:
•
On the Segment Start Date and Segment Maturity Date, it equals the Segment Value in that
Indexed Account.
•
On any other day, it equals the Interim Segment Value in that Indexed Account.
Cash Value of Your Policy on and after Attained Age 121. If the Policy continued beyond Attained Age 121, the Cash Value on and after Attained Age 121 will be
determined in the same way described above, except:
•
There will be no Annual Deductions taken; and
•
Premium payments cannot be made on or after Attained Age 121, except for payments
required under a Grace Period.
Minimum
Cash Values and Guaranteed Cost of Insurance Rates
The minimum cash values and guaranteed cost of insurance rates
are based on the mortality table and the guaranteed interest rates. All values are at least equal to those required by the law of the state that governs the Policy. We have
filed a detailed statement, if required, showing the method of calculating cash values and reserves with the insurance supervisory official of that state.
If the Insured dies while the Policy is in force, we will pay a
death benefit to your beneficiary. The amount we pay to your beneficiary (or beneficiaries) is the Policy Proceeds, which may be decreased due to outstanding loans. (See
“LOANS” and “GUARANTEED DISTRIBUTION RIDER”). The death benefit amount is the major component of the Policy Proceeds. We describe how we calculate the death benefit and the Policy Proceeds below.
Our obligations are subject to all payments made and actions
taken by us before our receipt of Notice of due proof of death. Any Policy Proceeds will be paid in accordance with applicable law or regulations governing death benefit
payments. (See “General Death Benefit Provisions” below.)
The death benefit is equal to the greater of:
•
The Cash Value plus any Annual Deduction refund; times the applicable minimum death
benefit factor (as identified below).
The
Annual Deduction refund is the amount of the Annual Deduction that may be returned to you if you Surrender the Policy or we calculate the death benefit and pay Policy
Proceeds to your beneficiary. The Annual Deduction refund equals the Annual Deduction at the beginning of the Policy Year; times the number of days to the next Policy
Anniversary divided by 365.
In your Policy, we provide a table of minimum death benefit factors that are set by the Code and are based on age (at the time of the calculation) and smoking status and sex (if not unisex) of the Insured. The applicable minimum death benefit factor is used in the cash value accumulation test described below.
Cash
Value Accumulation Test. The Code requires the Policy’s death benefit to be not less than an amount defined in the Code. As a result, if the Cash Value grows to certain levels, the death benefit increases to satisfy tax law requirements.
For your Policy, the cash value accumulation test will apply to the death benefit. Under the cash value accumulation test, the death benefit will not be less than the Cash Value times the applicable minimum death benefit factor set by the Code as described above. We will apply the applicable minimum death benefit factor based on the Attained Age of the Insured (as provided in the table in your Policy) at the time of the calculation. Sample minimum death benefit factors appear in Appendix E.
Policy Proceeds. We will pay the Policy Proceeds to the beneficiary, or to the person who is legally entitled to them, upon
receipt of due proof of the Insured’s death. Payment will be made in a lump sum. If the Insured dies while this Policy is in force, the Policy Proceeds are equal
to:
•
The death benefit as of the date of the Insured’s death; plus
•
Any Annual Deduction refund; plus
•
Any premium received after the date of the Insured’s death; less
•
Any unpaid Annual Deduction due under a Grace Period as of the date of the
Insured’s death; less
•
Any Policy Loan Balance.
Note: If the Insured dies after the Distribution Start Date and while the GDR remains in force, the Policy Proceeds calculation will be different than the Policy Proceeds calculation above. In addition, the GDR guarantees a minimum amount of Policy Proceeds ($10,000). For a description of how we calculate the Policy Proceeds under the GDR, see “Impact of Distribution Payments on Your Policy” under “GUARANTEED DISTRIBUTION RIDER.”
Age 121. On or after Attained Age 121, the death benefit will be calculated
using the applicable minimum death benefit factor for Attained Age 121. The tax consequences of keeping the Policy in force beyond the Insured’s Attained Age 121 are
unclear.
Suicide Exclusion. If the Insured dies by suicide, while sane or insane, within two years from the Policy Issue Date, the amount
payable will be limited to: the amount of premiums paid (without interest); less any Policy Loan Balance on the date of death. If the Insured dies by suicide, while sane or
insane, within two years from the date the Policy was reinstated, the amount payable will be limited to: the amount paid to reinstate the Policy; less any Policy Loan
Balance on the date of death. If the Policy was issued as the result of the exercise of an option given in another policy and proof of insurability was not required, the suicide period applicable to the coverage resulting from the option exercise will end at the same time as it would have under the original policy.
General Death Benefit Provisions
If we are presented with notification of your death before any requested transaction is completed, we will cancel the request. The death benefit and Policy Proceeds will be determined when we receive due proof of death. We will pay interest on any delayed death benefit payments in accordance with the laws and regulations in effect under the applicable state law.
Example 5—Calculating Your Death Benefit
Example 5 is intended to show how the death benefit is calculated. Assume the Policy’s Face Amount is $100,000 and Owner 1 with an Attained Age of 50 has allocated all Cash Value to an Indexed Account with a 1-Year Segment Term / Buffer 10 / S&P 500® Index with a Cap Rate of 10%. Her Segment Value on the Segment Start Date is $51,000 (before deducting the Annual Deduction). For purposes of this example, assume the Death Benefit is being calculated exactly halfway through the Segment Term and that there have been no other transactions that triggered an Interim Segment Value as of the date the Interim Segment Value is calculated.
Example
5—Calculating your Death Benefit
| |
Segment Value (before deducting the Annual Deduction)(1) |
|
Segment Value (after deducting the Annual Deduction)(1) |
|
| |
|
| |
|
Closing Value of the Index |
|
Interim Segment Value Calculation Halfway Through
Term |
Closing Value of the Index |
|
Segment Index Performance(2) |
|
| |
|
Segment Performance Rate(4) |
|
| |
|
| |
|
Death Benefit Calculation Halfway Through Term
|
| |
|
| |
|
Annual Deduction refund(8) |
|
Applicable minimum death benefit factor(9) |
|
| |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
On the Policy Start Date and each Policy Anniversary thereafter, we deduct the
charges for the Annual Deduction from your Cash Value. The Annual Deduction for each Policy Year will be taken from any Indexed Account according to the Policy Deduction Method. The Annual Deduction is taken out of the Cash Value on the Policy Start Date and each Policy Anniversary thereafter. For purposes of this example, assume the Annual Deduction is $1,000.
(2)
Segment Index Performance is equal to the percentage change in the Closing Value of the Index measured from the
Segment Start Date to the date of the Interim Segment Value calculation. Segment Index Performance is calculated as follows:
(600 [Closing Value of the Index on date of Interim Segment Value
calculation]
÷ 500 [Closing Value of the Index at Segment Start Date]) – 1 = 20%
(3)
The Accrued Cap Rate is equal to the Cap Rate multiplied by the number of days
elapsed since the Segment Start Date divided by the total number of days in the Segment Term. The Accrued Cap Rate is calculated as follows:
10% [Cap Rate] x 183 [number of days elapsed since the Segment Start Date]
÷ 365 [total number of days in the Segment Term] = 5%
(4)
The Segment Performance Rate is equal to the Accrued Cap Rate because it cannot
exceed the Accrued Cap Rate even though the Segment Index Performance was at 20% and the Cap Rate is 10%.
(5)
The Accrued Index Return is equal to the product of the current Segment Value
(Segment Value at the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) multiplied by the Segment Performance Rate. The Accrued Index Return is calculated as follows:
$50,000 [current Segment Value] x 5% [Segment Performance Rate] = $2,500
(6)
The Interim Segment Value is equal to the current Segment Value (Segment Value at
the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) plus the Accrued Index Return. The Interim Segment Value is calculated as follows:
$50,000 [current Segment
Value] + $2,500 [Accrued Index Return] = $52,500
(7)
The Cash Value is equal to the Interim Segment Value since all cash value has been
allocated to one Indexed Account.
(8)
The Annual Deduction refund is equal to the Annual Deduction at the beginning of the Policy Year times the number of days to the next Policy Anniversary divided by 365. Assuming there are 183 days to the next Policy Anniversary, the Annual Deduction refund is calculated as follows:
$1,000 [Annual Deduction
at the beginning of the Policy Year]
x (183 [days to the next Policy Anniversary] ÷ 365) = $501
(9)
The applicable minimum death benefit factors varies by Attained Age. This factor
applies to a female insured with an Attained Age of 50.
(10)
The Death Benefit is equal to the greater of the Face Amount or the Cash Value, plus any Annual Deduction refund, times the applicable minimum death benefit factor. The Death Benefit is calculated as follows:
$100,000 [Face Amount] or (($52,500 [Cash Value] + $501 [Annual Deduction
refund])
x 1.982 [applicable minimum death benefit factor]) = $105,048
You may Surrender the Policy for its Cash Surrender Value at any time while the Insured is living. Partial withdrawals of the Policy’s Cash Value are not permitted. We determine the Cash Surrender Value as of the date when we receive your request for Surrender. See “REQUESTS AND ELECTIONS.” The Cash Surrender Value equals the Cash Value plus any Annual Deduction refund less any Policy Loan Balance and any applicable Surrender charge. (See “Surrender charge” under “CHARGES.”) If you Surrender the Policy within thirty-one (31) days after the Policy Anniversary date, we will pay you the greater of (1) your Cash Surrender Value on the most recent Policy Anniversary date, reduced by any loans taken and any Loan Interest accrued since the Policy Anniversary Date, or (2) your Cash Surrender Value as of the date when we receive your request for Surrender. Coverage will terminate on the date you Surrender the Policy.
If you Surrender your Policy on any day other than a Policy Anniversary date
(including to exercise your Free Look Right), any available Cash Surrender Value that is invested in Indexed Accounts will be based on Interim Segment Value.
The Cash Surrender Value will be paid to you in a lump sum. Once
a Policy is Surrendered, all coverage and benefits cease and cannot be reinstated. A Surrender may result in adverse tax consequences. (See “FEDERAL TAX CONSIDERATIONS” below.)
If the GDR is not in force, the Policy will stay in effect after
Attained Age 121 as long as the Cash Value (after deducting any Policy Loan Balance, Annual Deduction, and Surrender charge) remains greater than or equal to zero. If the
GDR is in force, the Lifetime Lapse Prevention Benefit guarantees that your Policy will not lapse, subject to certain conditions. See “Operation of the Lifetime Lapse Prevention Benefit” under “GUARANTEED DISTRIBUTION RIDER.”
The Policies are designed to be long-term investments. If you Surrender your Policy on any day other than a Policy Anniversary (including to exercise your right to cancel), any
available Cash Surrender Value that is invested in Indexed Accounts will be based on Interim Segment Value. In extreme circumstances, you could lose all or a significant portion of the value of an Indexed Account if
you Surrender from the Indexed Account before the Segment Maturity Date.
GUARANTEED DISTRIBUTION RIDER
The Guaranteed Distribution Rider
(“GDR”) is automatically issued with the Policy at an additional charge and guarantees you will receive distribution payments in the form of loans over a certain
period of time. The Distribution Payments will reduce the Policy’s unloaned Cash Value and the Policy Proceeds payable to your beneficiary. However, the GDR also
includes a Lifetime Lapse Prevention Benefit and guarantees a minimum amount of Policy Proceeds ($10,000) upon the Insured’s death. The GDR, including the Lifetime Lapse Prevention Benefit, for your Policy is described below. The GDR can be cancelled or terminated at any time as stated below (see “Termination of the GDR” below).
Distribution Payments are loans. However, Distribution Payments and loans that are not Distribution Payments do not function in the same way, and it is important to understand the differences. The provisions described in “Loans that are not Distribution Payments” under the “LOANS” section do not apply to Distribution Payments.
The GDR Charge, which is assessed based on the Cash Value or the
Face Amount, will be deducted from your Policy’s Cash Value in accordance with the Policy Deduction Method. Distribution Payments do not reduce the Face Amount, which means the GDR
charge could continue to be based on the full Face Amount even though the Policy Proceeds
payable
to your beneficiary are reduced because of the Distribution Payments. The GDR Charge compensates us generally for the risks associated with guaranteeing distribution payments. If Distribution Payments terminate or the GDR terminates, we will no longer deduct the GDR Charge (see “Termination of the GDR” below).
Before the Distribution Start Date, the GDR Charge is equal to the GDR Charge rate (described below) multiplied by the greater of:
1.
The Policy’s Cash Value as of the Policy Anniversary; or
2.
The Policy’s Face Amount multiplied by the GDR Charge percentage.
On or after the Distribution Start Date, the GDR Charge is equal to the GDR Charge rate (described below) multiplied by the greater of:
1.
The Policy’s Cash Value that was used to determine the Maximum Distribution
Payment; or
2.
The Policy’s Face Amount multiplied by the GDR Charge percentage.
The GDR Charge rate and GDR Charge percentage vary based on individual characteristics, including the Insured’s Issue Age and (except for unisex Policies) sex, and, for the GDR Charge percentage, the Distribution Payment Duration. The GDR Charge rate ranges from $6.08 (minimum) to $19.40 (maximum) per $1,000.
The GDR Charge percentage ranges from 48% (minimum) to 67%
(maximum).
GDR Charge Examples. On any Policy Anniversary prior to the Distribution
Start Date, assume your GDR Charge rate is $12.50 per $1,000, and your GDR Charge percentage is 55%. This is the GDR Charge rate and GDR Charge percentage for a Representative Insured (male, age 50, in the nonsmoker class, under a Policy with a Face Amount of $200,000). Further assume that your Policy’s Cash Value is $125,000, and your Policy Face Amount is $200,000. Your GDR Charge would be $1,563, based on the greater of:
1.
$12.50 ÷ 1,000 [GDR Charge rate] x $125,000 [Cash Value] = $1,563, or
2.
$12.50 ÷ 1,000 [GDR Charge rate] x $200,000 [Policy Face Amount] x 55% [GDR Charge
Percentage] = $1,375.
Based on the same assumptions above, on any Policy Anniversary
on and after your Distribution Start Date, your GDR Charge would be $1,375, based on the greater of:
1.
$12.50 ÷ 1,000 [GDR Charge rate] x $100,000 [Cash Value that was used to
determine the Maximum Distribution Payment] = $1,250, or
2.
$12.50
÷ 1,000 [GDR Charge rate] x $200,000 [Policy Face Amount] x 55% [GDR Charge Percentage] = $1,375.
In the
Policy, we refer to the GDR Charge Rate as the Guaranteed Rider Charge Rate and the GDR Charge percentage as the Guaranteed Rider Charge Percentage. The GDR Charge rates and
the actual GDR Charge percentage applicable to your Policy are shown in your Policy specifications page. The dollar amount of your GDR Charge will appear on your Annual
Statement.
If your Policy has been in force for at least ten years, you are eligible to exercise the GDR. The Policy cannot be a MEC, and you must repay any Policy Loan Balance before starting Distribution Payments. Your Policy may become a MEC, for example, due to the payment of excess premiums or due to a reduction in your death benefit. Please be aware that the Loan Value calculation described under “Loans that are not Distribution Payments under the GDR” in the “LOANS” section does not apply to Distribution Payments. The Maximum Distribution Payment is the maximum amount available to you for each
Distribution Payment, if you were to start Distribution Payments that Policy Year. While Distribution Payments are being made, if necessary, we will increase your Policy’s Cash Value to allow for that Distribution Payment to be made in the form of a loan.
The Maximum Distribution Payment is calculated for each Policy Anniversary starting in Policy Year 11 until the Policy Owner starts receiving Distribution Payments. If you select an annual Distribution Payment Frequency, the Maximum Distribution Payment is an annual amount and is the maximum that you may receive as a Distribution Payment on the Distribution Start Date and on each Distribution Start Date anniversary. If you select a Distribution Payment Frequency other than annual (monthly, quarterly, or semi-annual), the Maximum Distribution Payment is not an annual amount but is the maximum amount you can receive for each Distribution Payment based on your selected frequency. It is equal to the Cash Value at that time, multiplied by a guaranteed payment rate (the Distribution Payment rate). The Maximum Distribution Payment, as calculated on each Policy Anniversary, will never be less than the Guaranteed Minimum Distribution Payment. The Guaranteed Minimum Distribution Payments are dollar amounts contractually declared at the time we issue the Policy. We
declare these amounts
based on the Face Amount, and your Issue Age, (except for unisex Policies) sex, and chosen Distribution Payment Duration. The amounts generally increase
depending upon when you begin Distribution Payments, as shown in the Rider specifications page. Please see the first bullet under “Minimum and Maximum
Limits for Distribution Payments” below for sample Guaranteed Minimum Distribution Payments based on Representative Insured. Distribution Payments may be paid past the selected Distribution Payment Duration if you chose a Distribution Payment amount that was less than the Maximum Distribution Payment, and the cumulative Distribution Payments you have received are less than the cumulative Maximum Distribution Payment amounts available to you.
Once the Policy Owner starts receiving Distribution Payments,
they may receive up to the calculated Maximum Distribution Payment as of that date. The Maximum Distribution Payment amount will not change after the Distribution Start
Date and will not be recalculated at subsequent Policy Anniversaries. Distribution Payments can also be voluntarily suspended at any time. They may be restarted but any suspension must be in effect for at least one year from the last Distribution Payment received.
The GDR also has a Lifetime Lapse Prevention Benefit that
guarantees the Policy will not lapse while the GDR is in force, provided Annual Lapse Prevention Premiums are paid when due and there is no Excess Loan.
Distribution Payments will terminate under certain circumstances. See “Termination of Distribution Payments” below. If Distribution Payments terminate, the other provisions of the GDR, such as the Lifetime Lapse Prevention Benefit will remain in effect. In addition, the GDR will terminate under certain circumstances. See “Termination of the GDR” below. If the GDR terminates, all benefits and protections offered by the GDR will terminate, including Distribution Payments and the Lifetime Lapse Prevention Benefit.
Distribution Payments start on the Distribution Start Date, and you specify the amount of each Distribution Payment, subject to the Maximum Distribution Payment and Distribution Payment minimum. The Maximum Distribution Payment, the Distribution Payment Frequency, and the Distribution Payment Duration are locked in on the Distribution Start Date; however, you may request to change the amount of the Distribution Payment at any time. We will change your Distribution Payment on the next monthly anniversary that is at least 15 calendar days after we receive your Notice of your request to change the Distribution Payment amount. You can increase the amount of future Distribution Payments up to the Maximum Distribution Payment. See Appendix D for Distribution Payment examples.
When thinking about Distribution Payments, consider the
following:
| |
|
|
Impact to Distribution Payment
amounts |
Distribution Payment
Duration |
At the time you purchase
the Policy, although you can
make a change when you
send us Notice to start
Distribution Payments |
The available durations are
10-year, 20-year, and
lifetime (up to Attained Age
121).
If you choose to receive the
Maximum Distribution
Payment, Distribution
Payments will be made for
the length of the
Distribution Payment
Duration associated with
the applicable Maximum
Distribution Payment.
If you do not select a
duration, we will not issue
the Policy. |
In general, a shorter
Distribution Payment
Duration means a higher
Maximum Distribution
Payment. |
Distribution Payment
Frequency |
At the time you purchase
the Policy, although you can
make a change when you
send us Notice to start
Distribution Payments |
The available frequencies
are annual, semi- annual,
quarterly, or monthly basis.
If you do not select a
frequency, we will not issue
the Policy. |
If you choose to receive Distribution Payments on a basis other than annual, the cumulative Distribution Payments for each year may be higher than if you chose an annual
Distribution Payment
because of the Distribution
Frequency Factor. See the
table under “Distribution
Payment Frequency” to see
how the Distribution
Frequency Factor impacts
the Maximum Distribution
Payment. |
Distribution Start Date. The Distribution Start Date is the date you start taking Distribution Payments as provided by the GDR. In
order to begin taking Distribution Payments under the GDR, the Policy needs to be in force for at least 10 years, you cannot have any outstanding Policy Loan Balance, and
your Policy cannot be a MEC as defined under Section 7702A of the Code. Distribution Payments must begin before Attained Age 121; however, Distribution Payments will
terminate once the Insured reaches Attained Age 121.
The Distribution Payment amount you select must be provided in a
Notice to us, along with any changes to the Distribution Payment Duration or Distribution Payment Frequency. Once we receive your Notice to begin Distribution Payments,
we will set your Distribution Start Date as the next monthly anniversary, that is at least 15 calendar days after we receive your notification. The Distribution Start Date is the date the first Distribution Payment will be made. On the Distribution Start Date, the Maximum Distribution Payment, the Distribution Payment Frequency, and the Distribution Payment Duration are locked in and will not change with respect to your specific Policy.
On your Distribution Start Date, we will transfer any Cash Value
in the Indexed Accounts and Holding Accounts to the Fixed Account. If your Distribution Start Date is any date other than a Segment Maturity Date, we will calculate the
Interim Segment Value of each Segment to determine the Indexed Account Cash Value that will be transferred to the Fixed Account. See “INTERIM SEGMENT VALUE.” While you are receiving Distribution Payments, you cannot transfer or allocate Cash Value to the Indexed Accounts. This means you will not have the opportunity to participate in any market investment performance.
You will not receive a refund of a portion of the Annual Indexed Account Charge when we transfer the Cash Value to the Fixed Account.
We will not accept
additional premium payments on and after the Distribution Start Date, unless the GDR terminates. See “Termination of the GDR” below. If the GDR terminates, we
may accept additional premium payments subject to the premium limits described in the “PREMIUMS” section.
Minimum and Maximum Limits for Distribution Payments. The GDR has certain
minimum and maximum amounts related to the Distribution Payments: (i)The Guaranteed Minimum Distribution Payment, (ii) the Distribution Payment minimum, and (iii) the Maximum Distribution Payment. See Appendix D for examples showing Guaranteed Minimum Distribution Payment and Maximum Distribution Payment.
•
The Guaranteed Minimum Distribution Payment is the minimum amount that we guarantee will
be available to you as an annual Distribution Payment. The Guaranteed Minimum Distribution Payment varies by Attained Age. The Guaranteed Minimum Distribution Payments that apply to your Policy are shown on your Rider specifications page,
and the amounts are guaranteed at issue. For a distribution frequency other than annual, the Guaranteed Minimum Distribution Payment is multiplied by the applicable distribution frequency factor (shown below in the “Distribution Payment Frequency” subsection). You may take less than Guaranteed Minimum Distribution Payment when you start Distribution Payments. The annual Guaranteed Minimum Distribution Payments for a Representative Insured (male,
age 50, in the nonsmoker risk class, under a Policy with a Face Amount of $200,000) would be as follows:
Distribution Payments Start Age |
Annual Guaranteed Minimum
Distribution Payment |
| |
|
| |
|
| |
|
•
The Distribution Payment minimum ($250) is the minimum amount you can receive as a
Distribution Payment.
•
The Maximum Distribution Payment is the maximum amount available to you for each
Distribution Payment, if you were to start Distribution Payments that Policy Year. The Maximum Distribution Payment is calculated at each Policy Anniversary prior to the Distribution Start Date and is equal to the Policy’s Cash Value on that date multiplied by the Distribution Payment rate. The Distribution Payment rate varies based on individual characteristics, including the Insured’s Issue Age, (except for unisex Policies) sex, Policy duration, and Distribution Payment Duration (including any changes in Distribution Payment Duration). The Distribution Payment rates that apply to your Policy can be found in the GDR, and the rates are guaranteed at issue. If you select an annual Distribution Payment Frequency, the Maximum Distribution Payment is an annual amount and is the maximum that you may receive as a Distribution Payment on the Distribution Start Date and on each Distribution Start Date anniversary. If you select a Distribution Payment Frequency other than annual (monthly, quarterly, or semi-annual), the Maximum Distribution Payment is not an annual amount
but is the maximum amount you can receive for each Distribution Payment based on your selected frequency. For a frequency other than annual, the Maximum Distribution Payment is multiplied by the applicable distribution frequency factor (shown below in the “Distribution Payment Frequency” subsection).
The Maximum Distribution Payment will never be less than the Guaranteed Minimum Distribution Payment effective on that Policy Anniversary. The Maximum Distribution Payment takes effect on the Distribution Start Date and cannot be changed.
Distribution Payment Duration. You choose how long to receive Distribution
Payments. The available durations are 10-year, 20-year, and lifetime (up to Attained Age 121). If you choose to receive the Maximum Distribution Payment, Distribution Payments will be made for the length of the Distribution Payment Duration associated with the applicable Maximum Distribution Payment. Provided Distribution Payments have not been terminated, Distribution Payments may be paid past your chosen Distribution Payment Duration if you chose a Distribution Payment amount that was less than the Maximum Distribution Payment, and the cumulative Distribution Payments you have received are less than the cumulative Maximum Distribution Payment amounts available to you. You have the option to continue receiving Distribution Payments beyond the Distribution Payment Duration period, as long as you have not exhausted the cumulative Maximum Distribution Payment amounts available to you. See Appendix D for an example showing when you could receive Distribution Payments beyond your chosen Distribution Payment Duration. However, if Distribution Payments are terminated or you have received the entire amount of Distribution Payments provided by the GDR, Distribution Payments will cease and no further Distribution Payments will be paid to you. See “Termination of Distribution Payments” below.
You select your Distribution Payment
Duration at the time your purchase the Policy. A change to your Distribution Payment Duration, which is only available before you start payments, will affect your Guaranteed
Minimum Distribution Payment, Maximum Distribution Payment, and Distribution Payment rate. If you change your Distribution Payment Duration, we will recalculate the Guaranteed Minimum Distribution Payment and Maximum Distribution Payment. We will use the Face Amount to recalculate the Guaranteed Minimum Distribution Payment, and the Cash Value on your most recent Policy Anniversary to
recalculate the Maximum
Distribution Payment. These payments and this rate may be less than they would have been if you had chosen the new Distribution Payment Duration on the date
we issued the Policy. If you decide to change your Distribution Payment Duration from what was chosen at the time of purchase, you must provide Notice to us.
The change to the Distribution Payment Duration must be included in the Notice you provide in order to start your Distribution Payments. Your Distribution
Payment Duration cannot be changed after the Distribution Start Date.
Distribution Payment Frequency.
You can receive Distribution Payments on an annual, semi- annual, quarterly, or monthly basis. A
distribution frequency factor is applied to determine your Guaranteed Minimum Distribution Payment and Maximum Distribution Payment for any frequency other than annual. If
you choose to receive Distribution Payments on a basis other than annual, the cumulative Distribution Payments for each year may be higher than if you chose an annual
Distribution Payment.
You select your Distribution Payment Duration at the time your
purchase the Policy. If you decide to change your Distribution Payment Frequency from what was chosen at Policy issue, you must provide Notice to us. The change to the
Distribution Payment Frequency must be included in the Notice you provide in order to start your Distribution Payments. Your Distribution Payment Frequency cannot be changed after the Distribution Start Date.
The Distribution Frequency Factor is always
applied to the annual Guaranteed Minimum Distribution Payment and annual Maximum Distribution Payment amount to determine the semiannual, quarterly, or monthly payments. In
this example, you can see how the Distribution Frequency Factor impacts the amount of each Guaranteed Minimum Distribution Payment and Maximum Distribution Payment and also the total amount of all Distribution Payments received in a
year.
| |
|
|
|
|
Distribution
Frequency Factor |
|
|
|
|
Guaranteed
Minimum
Distribution
Payment |
|
$7,599
($15,000 x 0.5066) |
$3,825
($15,000 x 0.2550) |
$1,281
($15,000 x 0.0854) |
Maximum
Distribution
Payment |
|
$10,132
($20,000 x 0.5066) |
$5,100
($20,000 x 0.2550) |
$1,708
($20,000 x 0.0854) |
Number of
Distribution
Payments in 1 Year |
|
|
|
|
Total of Distribution
Payments Received
in 1 Year (if
receiving
Guaranteed
Minimum
Distribution
Payment) |
|
|
|
|
Total of Distribution
Payments Received
in 1 Year (if
receiving Maximum
Distribution
Payment) |
|
|
|
|
One-time Payment. After the Distribution Start Date, if you have received
less than your Maximum Distribution Payment available to you, you may choose to receive a One-time Payment. The One-time Payment amount that is separate from your scheduled Distribution Payments. You may only make this election once, provided your Distribution Payments have not been terminated.
On the day we receive
your request in Good Order for a One-time Payment, the maximum One-time Payment is the lesser of:
1.
The difference between the cumulative Maximum Distribution Payments available to you
(from the Distribution Start Date to the calculation date, regardless of whether you suspended Distribution Payments at any time during that period) based on your chosen Distribution Payment Duration and Distribution Payment Frequency and the total
Distribution Payments you have received since the Distribution Start Date; or,
2.
The
lesser of: three times the Maximum Distribution Payment or $150,000 (which is referred to as the One-time Payment Limit and is shown in the GDR).
The One-time Payment, if taken, will be made in the form of a loan, the same as the Distribution Payments. If you take a loan after the Distribution Start Date that is not a Distribution Payment, we will treat this loan as your One-time Payment. If you request an amount that exceeds the One-time Payment, your request will not be considered in Good Order. We will contact you to ask if you want to change the One-time Payment amount to an amount that does not exceed the maximum One-time
Payment or confirm that you want to process the request using the original amount, which will terminate the GDR. Your request will not be in Good Order until we confirm your instructions or receive new ones.
Please be aware that the Loan Value
calculation under “Loans that are not Distribution Payments under the GDR” in the “LOANS” section does not apply to the One-time Payment. The maximum
One-time Payment is the lesser of 1 or 2 above. However, if your unloaned Cash Value is less than the maximum One-time Payment, the GDR will increase your Policy’s
Cash Value to allow for the One-time Payment to be made in the form of a loan.
See Appendix D for an example of the
One-time Payment.
Voluntarily Suspending Distribution Payments. Distribution Payments may be
voluntarily suspended at any time by providing Notice to us. Distribution Payments will be suspended on the next monthly anniversary that is at least 15 calendar days after we receive your Notice. If you choose to resume your Distribution Payments, you may not do so until the suspension has been in effect at least one year from the date of your last Distribution Payment.
While you are receiving Distribution
Payments, your unloaned Cash Value must be 100% allocated to the Fixed Account, and you cannot transfer to the Indexed Accounts. If you suspend Distribution Payments, you
may reallocate any Cash Value in the Fixed Account to any of the available Indexed Accounts subject to any transfer restrictions (see “TRANSFERS”).
Voluntarily Suspending
Distribution Payments |
|
|
If you direct us to suspend Distribution
Payments on a Policy Anniversary |
and you have provided us instructions
to reallocate Cash Value to the
Indexed Accounts |
On that Policy Anniversary, we will
transfer, in accordance with your
instructions, all or a portion of the
Fixed Account Cash Value to the
Indexed Accounts. The Segment Start
Date for the new Segments will be the
Policy Anniversary. |
If you direct us to suspend Distribution
Payments on any day other than a
Policy Anniversary |
and you have provided us instructions
to reallocate Cash Value to the
Indexed Accounts |
Your Cash Value will remain in the
Fixed Account until the next Policy
Anniversary, at which time we will
reallocate according to your
instructions. |
and you have not provided us
instructions to reallocate Cash Value
to the Indexed Accounts |
Your Cash Value will remain in the Fixed Account until you provide us instructions to reallocate, which will take effect on the Policy Anniversary after we receive your instructions. |
Restarting Distribution Payments. After Distribution Payments have been
voluntarily suspended for a year, you may restart Distribution Payments by providing Notice to us. The restarted Distribution Payments will begin on a monthly anniversary at least 15 calendar days after we receive your Notice. Distribution Payment amounts upon restarting are subject to the minimum and maximum limits described above in the “Minimum and Maximum Limits for Distribution Payments” section. If the GDR terminates before you resume Distribution Payments, you will not be eligible to receive any further Distribution Payments or the One-time Payment, if otherwise available to you. Upon restarting Distribution Payments, you cannot select a different Distribution Payment Frequency or Distribution Payment Duration.
On the day you restart
your Distribution Payments, we will transfer any Cash Value in the Indexed Accounts and Holding Accounts to the Fixed Account. If the day you restart your Distribution
Payments is any day other than a Segment Maturity Date, we will calculate the Interim Segment Value of each Segment to determine the Indexed Account Cash Value that will be
transferred to the Fixed Account. This means if the Segment Index Performance is positive, any gains we credit could be less than you would have received if you had held the investment until Segment Maturity Date. If the Segment Index Performance is negative, any losses we credit could be greater, possibly significantly greater, than if you waited until the Segment Index Performance was positive or until the Segment Maturity Date.
Additional Loans. While you are receiving Distribution Payments, you can change the amount of future Distribution Payments, as
long as you do not exceed the Maximum Distribution Payment. If you request a loan while you are receiving Distribution Payments (i.e., a loan outside of your scheduled Distribution Payments), we will treat this loan as
your One-time Payment, as long as you have not already received your One-time Payment. If the One-time Payment has not been taken and the loan amount taken exceeds the One-time Payment amount available at the time of your request, this GDR will terminate.
If Distribution Payments are voluntarily suspended, and it has been less than one year since you have received your last Distribution Payment and you request a loan, we will treat this loan as your One-time Payment, as long as you have not already received your One-time Payment.
If Distribution Payments are suspended, and it has been more
than one year since you have received your last Distribution Payment, and you request a loan, we will restart Distribution Payments at an amount up to the Maximum
Distribution Payment. Any amount above this will be treated as your One-time Payment, if available, whether or not the amount of the loan is the full amount available as the One-time Payment. If you request an amount that exceeds the One-time Payment, your request will not be considered in Good Order. We will contact you to ask if you want to change the One-time Payment amount to an amount that does not exceed the maximum One-time Payment or confirm that you want to process the request using the original amount, which will terminate the GDR. Your request will not be in Good Order until we confirm your instructions or receive new ones.
For purposes of calculating the One-time Payment after a
restart, the cumulative Maximum Distribution Payments available to you are from the Distribution Start Date to the One-time Payment calculation date, regardless of whether
you suspended Distribution Payments at any time during that period. See “One-time Payment” above.
Impact of Distribution Payments on Your Policy
Loans. Distribution Payments and the One-time Payment will be made in the form of loans. When you receive a
Distribution Payment or the One-time Payment, we will reduce the Fixed Account Cash Value by the amount of the loan and transfer that amount to the Loan Account.
Policy Proceeds. While the GDR is in force and after the Distribution Start Date, the following is substituted for the Policy
Proceeds calculation that is described in the “DEATH BENEFIT”
section.
Policy Proceeds will equal the greater of the result of items 1-5 below; or $10,000. The Policy Proceeds as of the date of the Insured’s death, calculated as follows:
1.
The death benefit as of the date of the Insured’s death. For the sole purpose
of calculating Policy Proceeds while the GDR is in force and after the Distribution Start Date, the death benefit is calculated as the greater of:
b.
The Cash Value plus any Annual Deduction refund plus any available One-time
Payment amount; times the applicable minimum death benefit factor; plus
2.
Any
Annual Deduction refund; plus
3.
Any premium received after the date of the Insured’s death; less
4.
Any amount due under a Grace Period as of the date of the Insured’s death;
less
5.
Any Policy Loan Balance.
Note: Distribution Payments will reduce the Policy Proceeds payable to your beneficiary as those payments increase the Policy Loan Balance. However, the GDR guarantees a minimum amount of Policy Proceeds ($10,000).
Policy’s Cash Value. While you are receiving Distribution Payments,
you cannot transfer or allocate Cash Value to the Indexed Accounts. If Distribution Payments are voluntarily suspended or terminated, you may transfer any Cash Value from
the Fixed Account to any of the available Indexed Accounts on the next Policy Anniversary.
When a Distribution
Payment is made, if necessary, the GDR will increase your Policy’s Cash Value to allow for Distribution Payments and the One-time Payment to be made in the form of a
loan.
Operation of the Lifetime Lapse Prevention Benefit
Under the Lifetime Lapse Prevention Benefit,
we guarantee the Policy will not lapse while the GDR is in force, provided Annual Lapse Prevention Premiums are paid when due and there is no Excess Loan. Annual Lapse
Prevention Premiums are calculated at issue and payable for 10 years.
Prior to the Distribution Start Date, if the
Policy’s unloaned Cash Value is insufficient to cover any Surrender charge and any Annual Deduction due on a monthly anniversary date, the Policy will not lapse as
long as:
•
The sum of all premiums paid to date is equal to or greater than the accumulated Annual
Lapse Prevention Premiums due since the Policy Issue Date, shown on your Policy Specifications page; and
•
There is no Excess Loan.
If premiums paid to date are less than the accumulated Annual Lapse Prevention Premiums due since the Policy Issue Date, you will have a Grace Period to pay the difference. If this payment is not made within the Grace Period, the GDR will terminate.
If necessary, we will increase your Policy’s Cash Value to
cover any Annual Deductions due if the GDR is in effect and the Policy’s Cash Value is insufficient to cover the Annual Deduction.
Beginning on the Distribution Start Date, the Lifetime Lapse Prevention Benefit guarantees that your Policy will not lapse while the GDR is in force. If Distribution Payments terminate and the GDR remains in force, the lapse protection will continue, even if you do not make any further premium payments.
Termination of Distribution Payments. While the GDR is in force, any
available Distribution Payments will terminate upon the earliest of:
1.
The
date your Policy becomes a MEC;
2.
The date an Accelerated Death benefit Payment has been paid;
3.
The date the cumulative Maximum Distribution Payment amounts available under this GDR
have been paid;
4.
The date the GDR terminates;
5.
The date the Insured reaches Attained Age 121; or
6.
The date the Insured dies.
Once Distribution Payments terminate, no further amounts will be available to you under the GDR, and the GDR Charge will terminate. You will not receive a refund of any portion of the GDR Charge.
Termination of the GDR. Your GDR will terminate upon the earliest of:
1.
The monthly anniversary following the date we receive your request to terminate this
GDR (See “REQUESTS AND ELECTIONS”);
2.
The
date a loan is taken for an amount that exceeds the available Distribution Payments and the One-time Payment;
3.
The date the GDR terminates due to premiums paid being less than the accumulated
Annual Lapse Prevention Premiums due since the Policy Issue Date;
4.
The
date you Surrender the Policy for its Cash Surrender Value; or
5.
The date your Policy terminates.
After the GDR terminates, it cannot be reinstated. If your Policy lapses, the GDR will not be reinstated if your Policy is reinstated. The GDR Charge will also terminate if the GDR is terminated; however, you will not receive a refund of any portion of the GDR Charge upon termination.
Modified Endowment Contract Within the First Policy Year. If your Policy is determined to be a MEC during the first Policy Year for any reason, you have the option to
terminate the GDR. Your request to terminate the GDR must also be made during the first Policy Year. Any GDR Charges paid at issue will be refunded back to the
Policy’s Cash Value.
ACCELERATION OF DEATH BENEFIT FOR TERMINAL ILLNESS
An Acceleration of Death Benefit for Terminal Illness (as defined in the SUMMARY section above as “Accelerated Death Benefit”) comes standard with the Policy. This benefit allows the Policy Owner to accelerate a one-time payment of part of the Policy’s death benefit if the Insured is terminally ill. The one-time payment for the Accelerated Death Benefit is different than the One-time Payment under the GDR.
In calculating the Accelerated Death Benefit, we assume that
death occurs one year from the date of the claim. If the Accelerated Death Benefit is exercised, the Policy’s Face Amount and Cash Value will decrease by a
proportional percentage. This means the amount withdrawn for the Accelerated Death Benefit payment will reduce the Face Amount and the Cash Value (according to the Policy Deduction Method) by the same percentage that the payment reduces the death benefit (calculated using the Face Amount and Cash Value before either of those has been reduced for the Accelerated Death Benefit), which will never be more than the dollar amount of the payment. Requests to accelerate the death benefit must be received at our Administrative Office. See “REQUESTS AND ELECTIONS.”
For example, assume the Policy’s death benefit was $100,000
(before the Accelerated Death Benefit), the Face Amount was $80,000 (before the Accelerated Death Benefit), and the Cash Value was $25,000 (before the Accelerated Death
Benefit), and you elect to accelerate $20,000 (20% of the death benefit). The Policy’s death benefit would reduce by 20% to $80,000, the Policy’s Face Amount and Cash Value would reduce in the same proportion as the death benefit (20%) to $64,000 and $20,000, respectively. The Face Amount, the Cash Value, and the amount we pay out as the death benefit amount (the Policy Proceeds) are different. To see how we calculate Policy Proceeds, see “Policy Proceeds” under “DEATH BENEFIT” and “Policy Proceeds” under “GUARANTEED DISTRIBUTION RIDER.”
There are certain limitations associated with this benefit,
which include the following:
•
The Policy Owner must accelerate at least $20,000, but not more than the lesser of
$250,000 and 50% of the Face Amount.
•
The
request for the Accelerated Death Benefit may only occur once and is subject to eligibility conditions, described below.
•
Your Policy is not eligible for the Accelerated Death Benefit if you are required by law
to use the Policy to meet the claims of creditors, whether in bankruptcy or otherwise, or you are required by a government agency to use the Policy to apply for, obtain, or keep a government benefit or entitlement.
Your right to an Accelerated Death Benefit payment is subject to the following eligibility conditions:
•
You must provide Notice to us that the Insured has a medical condition, certified by a
physician within the last 12 months, as being reasonably expected to result in the death of the Insured within 12 months from the date of certification (a “Terminal Illness”). The physician who provides the Terminal Illness certification may not be you, the Insured, or a member of the Insured’s or Owner’s family. We have the right to have the Insured examined at our expense by a physician we choose.
•
Any
irrevocable beneficiary must give consent in writing for the Accelerated Death Benefit payment.
•
Any
assignee must give consent in writing for the Accelerated Death Benefit payment.
The Accelerated Death Benefit payment is equal to the
Accelerated Death Benefit amount less any amount we apply to repay any Policy Loan Balance. However, we will only apply an amount up to the Policy Loan Balance multiplied by
the percentage of the death benefit that has been accelerated. An Accelerated Death Benefit payment will be paid upon receipt of due written proof that all eligibility conditions are met. The Accelerated Death Benefit payment will be paid to you in one lump sum. We will provide to you and any irrevocable beneficiary a disclosure statement showing the effect of the acceleration of the Policy’s values both when you first request, and upon payment of the Accelerated Death Benefit payment. If the Insured dies after the Owner elects to receive an Accelerated Death Benefit payment but before any such payment is made, the election shall be cancelled, and the Policy Proceeds will be paid.
If you accelerate the death benefit, we will calculate your
Accelerated Death Benefit amount and your Accelerated Death Benefit payment. We will apply the Policy Deduction Method and reduce the Fixed Account Cash Value and each
Indexed Account Cash Value and Holding Account Cash Value by the portion of the Accelerated Death Benefit payment attributable to each account.
On the Policy
Anniversary after acceleration of the death benefit, the Annual Deduction will be based on the reduced Cash Value and Face Amount.
If you are allocated to an Indexed Account and accelerate the death benefit on any day other than a Policy Anniversary, the amount withdrawn for the Accelerated Death Benefit payment will reduce the current Segment Value for each Segment by the same percentage that the payment reduces the Interim Segment Value of such Segment. Accordingly, when negative Segment Index Performance has caused the Interim Segment Value to be less than the current Segment Value, the Accelerated Death Benefit payment may cause the current Segment Value to be reduced by a greater amount than the Interim Segment Value is reduced (i.e., more than dollar for dollar). On the other hand, when positive Segment Index Performance has caused the Interim Segment Value to be greater than the current Segment Value, the current Segment Value will be reduced by a lesser amount than the Interim Segment Value is reduced (i.e., less than dollar for dollar).
For example, assume the Policy’s death benefit was $100,000 and the Cash Value was $25,000 at the time you elect to accelerate $20,000 (20% of the death benefit). The Policy’s death benefit would reduce by 20% to $80,000, and the Policy’s Cash Value would reduce in the same proportion as the death benefit (20%) to $20,000.
Note: If you exercise the
Accelerated Death Benefit, Distribution Payments under the GDR will terminate.
GRACE PERIOD AND REINSTATEMENT
If, on a monthly anniversary date, the Cash Value is less than the outstanding Policy Loan Balance, plus any Annual Deduction due, plus any Surrender charge, we will give you a 62-day period called the “Grace Period” to allow you to pay an amount sufficient to keep your Policy from lapsing. The required amount is called the “Amount Due”. At the start of the Grace Period, we will send you a notification of the Amount Due. We will send this notification to your last known address, to the address of any other person you have designated to receive notification as a protection against unintentional lapse, and to that of any assignee on record. If we do not receive the Amount Due by the end of the Grace Period, the Policy will lapse, and it will terminate without value.
If the Insured dies during the Grace Period, any unpaid Annual
Deduction due to the date of death will be deducted from the Policy Proceeds.
Reinstating Your Policy after a Lapse
If the Policy has lapsed, you may reinstate your Policy within three years from the date of lapse and prior to Attained Age. This is called a “Reinstatement”. To reinstate, you must submit a request and the following:
1.
Proof that the Insured is insurable by our standards.
2.
Payment of any Policy Loan Balance that was outstanding on the date of lapse.
3.
Payment of any Annual Deduction due and not paid at the time of lapse.
4.
Payment of any Surrender charge imposed at the time of lapse and not paid.
5.
If Reinstatement occurs on a date other than a Policy Anniversary, payment of a
portion of the Annual Deduction for the year of Reinstatement.
If the Insured is alive on the date we approve the request for Reinstatement, the Policy will be in force from the monthly anniversary date following the date all Reinstatement requirements are met. If the Insured is not alive on the date we approve the request for Reinstatement, such approval is void and the Policy will remain lapsed.
Any Cash Value at the time of Reinstatement
will be allocated to the Fixed Account and it will include any Surrender charge taken at the time of lapse. If you provide us new instructions to allocate your Cash Value to
the Indexed Accounts, the Cash Value will remain in the Fixed Account until the next Policy Anniversary when we transfer the Fixed Account Cash Value to the Indexed Accounts according to your allocation instructions.
Continuation of Insurance after Premium Payments Stop
If the GDR not in force and you stop making premium payments, the insurance provided under the Policy will continue in accordance with the provisions of the Policy for as long as the Cash Value is large enough to cover any Policy Loan Balance, the Annual Deduction, and any Surrender charge.
If the GDR is in force
and you stop paying the Annual Lapse Prevention Premiums when due, the GDR will terminate; however, the Policy may continue as long as the Cash Value is large enough to
cover any Policy Loan Balance, the Annual Deduction, and any Surrender charge.
We make certain charges and deductions under the Policy.
Percent of Premium Charge
We deduct a 10% Percent of Premium Charge from each premium payment. We impose this charge to reimburse us generally for policy sale expenses, distribution expenses, and administrative expenses (such as those related to premium tax and certain other state filings), and to cover federal income tax liability related to
premiums.
On the Policy Start Date and each Policy Anniversary
thereafter, we deduct charges from your Policy’s Cash Value. Policy Deduction are taken proportionally from the Fixed Account, Holding Accounts, and Indexed Accounts.
The sum of these charges is called the “Annual Deduction” and
equals:
2.
The Annual Administrative Charge; plus
3.
The Annual Indexed Account Charge; plus
4.
The Annual Cost of Insurance Charge.
The Annual Deduction for a Policy Year will be taken according to the Policy Deduction Method. We will not take any Annual Deductions from your Policy’s Cash Value on or after Attained Age 121. However, Loan Interest will be charged on any loan.
GDR Charge. See the “GDR Charge” section under the “GUARANTEED DISTRIBUTION RIDER section for a detailed
explanation of the GDR Charge.
Annual Administrative Charge. An Annual Administrative Charge will be assessed on your Policy. This charge compensates us generally for the
costs of underwriting, issuing (including sales commissions), and administering the Policy. The charge equals: the Face Amount at the beginning of the Policy Year; times the
applicable Annual Administrative Charge rate for that Policy Year divided by 1,000. The maximum Annual Administrative Charge rate is shown on the Policy specifications pages and ranges from $0.31 to $0.65 per $1,000 of Face Amount. The actual Annual Administrative Charge rate we use may be lower than the maximum Annual Administrative Charge rate shown on the Policy Specifications pages.
The Annual Administrative Charge varies based on individual characteristics, including the Insured’s age, risk class, and (except for unisex Policies) sex. You can obtain more information about the Administrative Charge that would apply to a particular Insured by contacting your registered representative.
Annual Indexed Account Charge. An Annual Indexed Account Charge will be assessed on your Policy if you allocate to one or more Indexed
Accounts. This charge compensates us generally for the costs associated with offering the Indexed Accounts. The charge equals: the sum of your Policy’s Cash Value in
each Indexed Account; times the applicable Annual Indexed Account Charge rate for the Policy Year. The Annual Indexed Account Charge rate will never exceed the maximum
Annual Indexed Account Charge rate. The current Annual Indexed Account Charge rate is 0.2%, and the maximum Annual Indexed Account Charge rate is 0.5%. If you start receiving Distribution Payments and we transfer all your Cash Value from the Indexed Accounts and/or Holding Accounts to the Fixed Account, you will not be refunded any portion of the Annual Indexed Account Charge for that Policy Year.
Annual Cost of Insurance Charge. An Annual Administrative Charge will be assessed on your Policy. This charge compensates us generally for the
costs of providing insurance coverage for the next Policy Year. The cost of insurance charge for a Policy Year is equal to the “net amount at risk” under the
Policy, multiplied by the annual cost of insurance rate for that Policy Year, divided by 1,000. We determine the net amount at risk on the first day of the Policy Year. The
net amount at risk is the difference between the death benefit (generally discounted at 1%) and the Policy’s Cash Value. The net amount at risk is affected by Segment Index Performance, loans, premium payments and charges.
The guaranteed cost of insurance rates for a Policy
depend on the Insured’s
•
sex (if the Policy is sex-based).
The current cost of insurance rates will depend on the above factors, plus
•
the Insured’s Issue Age
We guarantee that the rates for underwritten Policies will not be higher than rates based on the 2017 Commissioners Standard Ordinary Mortality Tables (the “2017 CSO Tables”) with smoker/ nonsmoker modifications.
The maximum Annual Cost of Insurance Charge rate is $0.74 to $1,000 per $1,000 net amount at risk, and the current Annual Cost of Insurance Charge rate is $0.20 to $489.60 per $1,000 of net amount at risk. The minimum charge rate shown, for both the maximum and current rates, is based on the most favorable risk class, youngest issue age and earliest Policy Year. The maximum charge rate shown is based on the least favorable risk class, oldest issue age and latest Policy Year. The actual rates we use may be lower than the maximum rates, depending on our expectations about our future mortality and expense experience, lapse rates, taxes and investment earnings. We review the adequacy of our cost of insurance rates and other non-guaranteed charges periodically and may adjust them. Any change will apply prospectively. The risk classes we use are nonsmoker and smoker.
Cost of insurance rates are generally lower for nonsmokers than
for smokers and generally lower for females than for males. Within a given risk class, cost of insurance rates are generally lower for Insureds with lower issue ages. Where
required by state law, cost of insurance rates (and Policy values and benefits) do not vary based on the sex of the Insured.
If, during the first ten Policy Years, you Surrender or lapse
your Policy, then we will deduct a Surrender charge from the Cash Value. The maximum Surrender charge is shown in your Policy. We impose a Surrender charge to reimburse us
generally for Policy sale expenses including commissions and other distribution, promotion and acquisition expenses. The maximum Surrender charge per $1,000 of Face Amount that could apply under any Policy is $45 (in Policy
Year 1), which reduces to $0 in Policy Year 11 and later.
The Surrender charge reduces the Policy’s Cash Value in the Indexed Accounts, Holding Accounts, and the Fixed Account in proportion to the amount of the Policy’s Cash Value in each.
Partial withdrawals are not permitted under the Policy.
Illustration of Benefits Charge
We reserve the right to impose a $25 charge for each illustration
of Policy benefits that you request in excess of one per year. If imposed, this charge would compensate us generally for the cost of preparing and delivering the
illustration to you. We are currently waiving this charge.
FEDERAL TAX CONSIDERATIONS
The following information on taxes is a general discussion of the subject. It is not intended as tax advice. The provisions of the Code that govern the Policy are complex and subject to change. This discussion is based upon our understanding of the present Federal income tax laws. No representation is made as to the likelihood of continuation of the present Federal income tax laws or as to how they may be interpreted by the Internal Revenue Service (“IRS”). The applicability of Federal income tax rules may vary with your particular circumstances. This discussion does not include all the Federal income tax rules that may affect you and your Policy and does not purport to be complete or to cover all tax situations. Nor does this discussion fully address other Federal tax consequences (such as estate and gift taxes, sales to foreign individuals or entities) and does not address state, local, or foreign tax consequences, which may affect your investment in the Policy. As a result, you should always consult a tax adviser for complete information and advice applicable to your individual situation.
In order to qualify as a life insurance policy for Federal income
tax purposes and to receive the tax treatment normally accorded life insurance policies under Federal tax law, a policy must satisfy certain requirements which are set forth
in the Internal Revenue Code of 1986, as amended (the “Code”). Specifically, the Policy must meet the applicable requirements
under Section 7702 of the
Code. Guidance as to how these requirements are to be applied is limited. Nevertheless, we anticipate that the Policy should be deemed to be a life insurance
policy under Federal tax law. We may take appropriate steps to bring the Policy into compliance with applicable requirements, and we reserve the right to
restrict Policy transactions in order to do so. The insurance proceeds payable on the death of the Insured will never be less than the minimum amount required for the Policy to be treated as life insurance under Section 7702 of the Code, as in effect on the date the Policy was issued.
The following discussion
assumes that the Policy will qualify as a life insurance policy for Federal income tax purposes.
Tax Treatment of Policy Benefits
In General. The amount received under the Policy by reason of the death of
the Insured (see “DEATH BENEFIT” section above) is referred to in this section as the death benefit and should generally be excludible from the gross income of
the beneficiary for Federal income tax purposes.
In the case of employer-owned life insurance as defined in
Section 101(j) of the Code, the amount of the death benefit excludable from gross income is limited to premiums paid unless the Policy falls within certain specified
exceptions and a notice and consent requirement is satisfied before the Policy is issued. Certain specified exceptions are based on the status of an employee as highly compensated, a director, or recently employed. There are also exceptions for Policy Proceeds paid to an employee’s heirs. These exceptions only apply if proper notice is given to the insured employee and consent is received from the insured employee before the issuance of the Policy. These rules apply to Policies issued August 18, 2006 and later and also apply to policies issued before August 18, 2006 after a material increase in the death benefit or other material change. An IRS reporting requirement applies to employer-owned life insurance subject to these rules. Because these rules are complex and will affect the tax treatment of death benefits, it is advisable to consult tax counsel.
The death benefit will also be taxable in the case of a transfer-for-value unless certain exceptions apply.
Federal, state and local estate, inheritance and other tax consequences of ownership, or receipt of Policy Proceeds, depend on the circumstances of each Policy Owner or beneficiary. A tax adviser should be consulted on these circumstances.
Generally, the Policy Owner will not be deemed to be in constructive receipt of the Cash Value until there is a distribution or a deemed distribution, including upon Surrender or lapse of the Policy. When distributions from a Policy occur, or when loans are taken from or secured by a Policy, the tax consequences depend on whether the Policy is classified as a MEC.
Modified Endowment Contracts (“MEC”). Under section 7702A of
the Code, certain life insurance policies are classified as modified endowment contracts (“MEC”), with less favorable income tax treatment than other life
insurance contracts. Due to the Policy’s flexibility, such as with respect to premium payments, each Policy’s circumstances will determine whether the Policy is a MEC. In general, a Policy will be classified as a MEC if the amount of premiums paid into the Policy causes the Policy to fail the “7-pay test.” A Policy will fail the 7-pay test if at any time in the first seven Policy years, or seven years after a material change, the amount paid into the Policy exceeds the sum of the level premiums that would have been paid at that point under a Policy that provided for paid-up future benefits after the payment of seven level annual payments.
If there is a reduction in the benefits under the Policy during
a 7-pay testing period, the 7-pay test will have to be reapplied as if the Policy had originally been issued at the reduced Face Amount. If there is a “material
change” in the Policy’s benefits or other terms, even after the first seven Policy years, the Policy may have to be retested as if it were a newly issued Policy. To prevent your Policy from becoming a modified endowment contract, it may be necessary to limit premium payments or to limit reductions in benefits. A current or prospective Policy Owner should consult a tax adviser to determine whether a Policy transaction will cause the Policy to be classified as a MEC.
Distributions Other Than Death Benefits from
Modified Endowment Contracts. Policies classified as MEC are subject to the following tax
rules:
(1)
All distributions other than death benefits, including distributions upon
Surrender, will be treated first as distributions of gain taxable as ordinary income and as tax-free recovery of the Policy Owner’s investment in the Policy only after all gain has been distributed.
(2)
Loans
taken from or secured by a Policy classified as a MEC are treated as distributions and taxed accordingly.
(3)
A
10 percent additional income tax is imposed on the amount subject to tax unless an exception applies under the tax law, for example, where the distribution or loan is made
when the Policy Owner has attained age 59½ or is disabled. The foregoing exceptions generally do not apply to a Policy Owner which is a non-natural person, such as
a corporation.
If a Policy becomes a
modified endowment contract, distributions will be taxed as distributions from a MEC. In addition, distributions from a Policy within two years before it becomes a modified
endowment contract will be taxed in this manner. This means that a distribution made from a Policy that is not a modified endowment contract could later become taxable as a
distribution from a MEC.
Distributions Other Than Death Benefits from
Policies that are not Modified Endowment Contracts. Distributions other than death
benefits from a Policy that is not classified as a MEC are generally treated first as a non-taxable recovery of the Policy Owner’s investment in the Policy, and only
after the recovery of all investment in the Policy as gain taxable as ordinary income. However, distributions during the first 15 Policy Years accompanied by a reduction in
Policy benefits, including distributions which must be made in order to enable the Policy to continue to qualify as a life insurance policy for Federal income tax purposes, are subject to different tax rules and may be treated in whole or in part as taxable income.
Loans from or secured by a Policy that is not a MEC are
generally not treated as distributions. A tax adviser should be consulted when considering a loan.
Finally, neither distributions from nor loans from or secured by a Policy that is not a MEC are subject to the 10 percent additional income tax.
Loans. In general, interest on a loan will not be deductible. If a loan is outstanding when a Policy is canceled or lapses, the amount of the outstanding indebtedness will be added to the amount distributed and will be taxed accordingly. A loan may also be taxed when a Policy is exchanged. Before taking out a loan, you should consult a tax adviser as to the tax consequences.
Guaranteed Distribution Rider. Distribution Payments under the GDR are made in the form of loans. A loan is generally not treated as a
taxable distribution if the Policy is not a MEC and the Policy remains in force during the lifetime of the Insured. As a result, the Company generally does not intend to
report the benefits payable under the GDR to the IRS as taxable income based upon the Company’s current understanding of applicable tax law. Taxation and tax reporting
may apply if the Policy lapses, is Surrendered, or the Policy becomes a MEC. The tax law is complex and subject to change. Our tax reporting position may change in the future due to future IRS guidance, as well as any clarifications or changes to applicable tax law. The Company cannot guarantee particular tax results. You should consult with your attorney or qualified tax advisor to determine the tax consequences of the GDR and the Policy.
Multiple Policies. All modified endowment contracts that are issued by BLIC (or its affiliates) to the same Policy Owner during
any calendar year are treated as one MEC for purposes of determining the amount includible in the Policy Owner’s income when a taxable distribution occurs.
Withholding. To the extent that Policy distributions are taxable, they are
generally subject to withholding for the recipient’s Federal income tax liability. Recipients can generally elect, however, not to have tax withheld from
distributions.
Life Insurance Purchases by Residents of Puerto Rico. In Rev. Rul. 2004-75,
2004-31 I.R.B. 109, the Internal Revenue Service announced that income received by residents of Puerto Rico under life insurance policies issued by a Puerto Rico branch of a United States life insurance company is U.S.-source income that is generally subject to United States Federal income tax.
Life Insurance Purchases by Nonresident Aliens
and Foreign Corporations. Policy Owners that are not U.S. citizens or residents will generally be
subject to U.S. Federal withholding tax on taxable distributions from life insurance policies at a 30% rate, unless a lower treaty rate applies. In addition, Policy Owners
may be subject to state and/or municipal taxes and taxes that may be imposed by the Policy Owner’s country of citizenship or residence. Prospective purchasers are
advised to consult with a qualified tax adviser regarding taxation with respect to a purchase of the Policy.
Acceleration of Death Benefit for Terminal Illness. Payments received under
the Accelerated Death Benefit should generally be excludable from the gross income of the Policy Owner except in certain circumstances, such as certain business-related contexts described in Section 101(g) of the Code. You should consult a qualified tax adviser about the consequences of exercising a payment under this provision.
Estate, Gift and Generation-Skipping Transfer
Taxes. The transfer of the Policy or the designation of a beneficiary may have Federal, state,
and/or local transfer and inheritance tax consequences, including the imposition of gift, estate, and generation-skipping transfer taxes. When the Insured dies, the death
proceeds will generally be includable in the Policy Owner’s estate for purposes of the Federal estate tax if the Policy Owner was the Insured, if the Insured possessed
incidents of ownership in the Policy at the time of death, or if the Insured made a gift transfer of the Policy within three years of death. If the Policy Owner was not the Insured, the fair market value of the Policy would be included in the Policy Owner’s estate upon the Policy Owner’s death.
Moreover, under
certain circumstances, the Code may impose a “generation-skipping transfer tax” when all or part of a life insurance policy is transferred to, or a death benefit
is paid to, an individual two or more generations younger than the Policy Owner. Regulations issued under the Internal Revenue Code may require us to deduct the tax from
your Policy, or from any applicable payment, and pay it directly to the IRS.
The particular situation of each Policy Owner,
Insured or beneficiary will determine how Policy ownership or receipt of Policy Proceeds will be treated for purposes of federal estate, gift and generation-skipping
transfer taxes, as well as state and local estate, inheritance and other taxes. Because these rules are complex, you should consult with a qualified tax adviser for specific information. For example, qualified tax advisers should be consulted concerning the estate and gift tax consequences of Policy ownership and distributions under Federal, state and local law. You and your tax adviser should also review the individual situation of each Policy Owner, Insured, or beneficiary to determine the extent, if any, to which Federal, state, and local transfer and inheritance taxes may be imposed and how ownership or receipt of Policy Proceeds will be treated for purposes of Federal, state and local estate, inheritance, generation-skipping and other
taxes.
In 2026, federal
tax law provides for a $15,000,000 gift, estate and generation-skipping transfer tax exemption,
which will be indexed for inflation in subsequent years.
The complexity of the tax law, along with
uncertainty as to how it might be modified in coming years, underscores the importance of seeking guidance from a qualified adviser to help ensure that your estate plan
adequately addresses your needs and those of your beneficiaries under all possible scenarios.
Transfer of Issued Life Insurance Policies to Third Parties. If you
transfer the Policy to a third party, including a sale of the Policy to a life settlement company, such transfer may be taxable. As noted above, the death benefit will also
be taxable in the case of a transfer for value unless certain exceptions apply. We may be required to report certain information to the IRS, as required under Section 6050Y and applicable tax regulations. You should consult with a qualified tax adviser for additional information prior to transferring the Policy.
Other Policy Owner Tax Matters. The application of certain tax rules after age 100 is not entirely clear. The tax consequences of continuing
the Policy beyond the Insured’s Attained Age 121 are also unclear. You should consult a tax adviser if you intend to keep the Policy in force beyond the
Insured’s Attained Age 100.
The Policy is not specifically designed to be issued in connection with a plan governed under the Employee Retirement Income Security Act of 1974, as amended, or in connection with a pension or profit-sharing plan, or other similar arrangement. As a result, purchase of the Policy in connection with such plans may result in adverse tax consequences. You should seek advice from a qualified tax adviser if you intend to use the Policy in connection with such plans.
Ownership of the Policy by a corporation, trust or other non-natural person could jeopardize some (or all) of such entity’s interest deduction under Code Section 264, even where such entity’s indebtedness is in no way connected to the Policy. In addition, under Section 264(f)(5), if a business (other than a sole proprietorship) is directly or indirectly a beneficiary of the Policy, the Policy could be treated as held by the business for purposes of the Section 264(f) entity-holder rules. Therefore, it would be advisable to consult with a qualified tax adviser before any non-natural person is made an owner or holder of the Policy, or before a business (other than a sole proprietorship) is made a beneficiary of the Policy.
Business Uses of Policy. Subject to our administrative rules, businesses
can own the Policy and may use the Policy in various arrangements, including split dollar insurance plans. The tax consequences of such plans may vary depending on the
particular facts and circumstances. In the case of a business owned Policy, the provisions of Code Section 101(j) may limit the amount of the death benefit excludable from gross income unless a specified exception applies and a notice and consent requirement is satisfied, as discussed above. In addition, Policy premium payments generally may not be deductible, and you should consult with a tax adviser concerning the tax impact of any purchase of the Policy or in connection with any business uses of the Policy. If you are contemplating a change to an existing Policy or purchasing the Policy for any arrangement the value of which depends in part on its tax consequences, you should consult a qualified tax adviser.
Guidance on Split Dollar Plans. The IRS has issued guidance on split dollar
insurance plans. A tax adviser should be consulted with respect to this guidance if you have purchased or are considering the purchase of a Policy for a split dollar insurance plan. If your Policy is part of an equity split dollar arrangement taxed under the economic benefit regime, there is a risk that some portion of the Policy’s Cash Value may be taxed prior to any Policy distribution. If your split dollar plan provides deferred compensation, specific tax rules governing deferred compensation arrangements may apply. Failure to adhere to these rules will result in adverse tax consequences.
In addition, the Sarbanes-Oxley Act of 2002 (the
“Act”), which was signed into law on July 30, 2002, prohibits, with limited exceptions, publicly traded companies, including non-U.S. companies that have
securities listed on U.S. exchanges, from extending, directly or indirectly or through a subsidiary, many types of personal loans to their directors or executive
officers. It is possible
that this prohibition may be interpreted to apply to split-dollar life insurance arrangements for directors and executive officers of such companies, since
such arrangements can arguably be viewed as involving a loan from the employer for at least some purposes.
Any affected business contemplating the payment of a premium on an existing Policy or the purchase of a new Policy in connection with a split-dollar life insurance arrangement should consult legal counsel.
Possible Tax Law Changes.
Although the likelihood of legislative changes is uncertain, there is always the possibility that
the tax treatment of the Policy could change by legislation or otherwise. Consult a tax adviser with respect to legislative developments and their effect on the
Policy.
Tax Credits and Deductions. BLIC may be entitled to certain tax benefits
related to the assets of the Separate Account. These tax benefits, which may include foreign tax credits and corporate dividend received deductions, are not passed back to
the Separate Account or to Policy Owners since BLIC is the owner of the assets from which the tax benefits are derived.
You may cancel the Policy within ten days (more in some states) after you receive it. See
Appendix F for state variations. This is known as the “Right to Examine” or “Free Look.” You may return the Policy to our Administrative Office or your financial representative. Insurance coverage ends as soon as you return the Policy (determined by postmark, if the Policy is mailed). When you cancel the Policy within this Right to Examine period, we will not assess a Surrender charge.
If you cancel the Policy, depending on state law, we refund either: (a) premiums paid, less any loan amount; or (b) the Policy’s Cash Value as of the date we receive the returned Policy, plus any charges we deducted (the Percent of Premium Charge and the Annual Deduction), less any Policy Loan Balance. The amount you receive for a cancellation request submitted to your financial representative will depend on the day that such request is, in turn, provided to us. In states where we return your Cash Value, the amount you receive may be more or less than your premium payments depending upon the Indexed Accounts you allocated your Net Premiums to during the Right to Examine period. It is important to note that we will use an Interim Segment Value calculation to determine the Indexed Account Cash Value. This means that you bear the risk of any decline in the Cash Value of your Policy during the Right to Examine period.
You, as the Owner, have all the interest and rights under the
Policy. Subject to our administrative procedures, we may also permit ownership by a corporation (a type of non-natural person) or other legal entity.
These rights include the right to:
(b)
change the beneficiary.
(c)
assign the Policy (subject to limitation).
(d)
exercise all other rights, benefits, options, and privileges permitted by the Policy
or us.
The Owner is as designated at the time the Policy is issued, unless changed. After the date we issue the Policy but before the death of the Insured, you may change the Owner at any time. Any change of Owner is subject to our underwriting requirements in effect at the time of the request. A change of Owner will automatically revoke any prior designation of the Owner unless there is an irrevocable beneficiary. Irrevocable beneficiaries must consent to any change of beneficiary. The new Owner will have all of the rights of the Owner, including the right to make further change of Owner.
The Policy can be owned by more than one Owner. All Owners must
exercise the rights of ownership by joint action. Upon the death of an Owner that Owner’s estate will be the Owner, unless a successor Owner or contingent Owner has
been named. The rights of the Owner will end at the death of the Insured, except as provided in the beneficiary of Your Policy provision.
Beneficiary
The person(s) or entity(ies) you name to receive the Policy Proceeds upon the death of the Insured. The beneficiary is named at the time the Policy is issued unless changed at a later date. Unless an irrevocable beneficiary has been named, you can change the beneficiary at any time after the date we issue the Policy but before the death of the Insured. The beneficiary has no interest in the Policy until the death of the Insured. A person must survive the Insured to qualify as beneficiary. If no beneficiary survives, the proceeds will be paid to the Owner, if alive, otherwise the Owner’s estate.
If you want the change the Owner or beneficiary, you must make a request by submitting a Notice to us during the Insured’s lifetime. Once the request is received, unless you tell us otherwise, the change will take effect as of the date you signed the Notice, whether or not the Insured is living when we receive your request. The change will be subject to any legal restrictions. It will also be subject to any payment we made or action we took before we received the change.
A numbered sequence can be used to name successive Owners or beneficiaries. Co-beneficiaries will receive equal shares unless otherwise stated. In naming (designating) Owners or beneficiaries, unless you tell us otherwise, if you use the terms below, they will be interpreted as stated in this provision:
A general designation of unnamed children as a group of
beneficiaries includes all future children born to or adopted by the Insured after the date of the designation, including a posthumous child.
“Provision for issue” means that if a named beneficiary does not survive the Insured, the share of the Policy Proceeds for that beneficiary will go to that beneficiary’s living issue by right of representation.
A designation that specifies a family
relationship such as “wife,” “husband,” “spouse,” or “child” refers to their relationship to the Insured.
At the time of payment of Policy Proceeds, we can rely on an affidavit of any Owner or other responsible person to determine family relations or members of a class.
The Policy may be assigned with our prior approval. You must send a Notice to us at our Administrative Office. To the extent allowed by state law, we reserve the right to refuse our consent to any assignment at any time on a nondiscriminatory basis. If you make an absolute assignment of the Policy, there is no change of Owner or beneficiary. However, the rights of the Owner and beneficiary will be subject to the terms of the collateral assignment. We will not be party to a collateral assignment, nor will we be responsible for verifying any information provided to us in connection with any assignment or determining whether or not an assignment is valid. An assignment, unless you tell us otherwise, will be effective on the date signed by you, subject to any payments made or actions taken by us prior to receipt of such Notice. We assume no
responsibility for the validity or effect of any assignment. We will not be liable for any payment or other action we take in accordance with the Policy before we record the assignment. Assignments will be effective as of the date the written Notice of assignment was signed, subject to all payments made and actions taken by us before a copy of the signed assignment form is received by us at our Administrative Office. You should consult your tax adviser regarding the tax consequences of an assignment. An assignment may be a taxable event.
SUSPENSION OF PAYMENT OR TRANSFERS
We may be required to suspend or delay the
payment of the Policy Proceeds, the calculation of Distribution Payments, and transfers when we cannot obtain a Closing Value on the Index under the following
circumstances:
(i)
the NYSE, or any other relevant stock exchange, is closed (other than customary
weekend and holiday closings);
(ii)
trading on the NYSE, or any other relevant stock exchange, is restricted;
(iii)
an emergency exists such that we cannot obtain a Closing Value of the Index; or
(iv)
during any other period when a regulator by order, so permits.
We have the right to defer payment of the part of any amount paid from the Fixed Account or the Holding Accounts on Surrender for no more than six months.
THE INSURANCE COMPANY
Brighthouse Life Insurance Company (“BLIC”)
BLIC is a Delaware stock insurance company originally incorporated in Connecticut in
1863. BLIC is
licensed to conduct business in all states of the United States (except New York), the District of Columbia, the Bahamas, Guam, Puerto Rico, the British Virgin Islands and the U.S. Virgin
Islands. BLIC is an indirect wholly-owned subsidiary of, and ultimately controlled by, Brighthouse Financial, Inc. (“BHF”), a publicly-traded company. BHF,
through its subsidiaries and affiliates, is one of the largest providers of annuities and life insurance in the U.S. BLIC’s executive offices are located at 11225
North Community House Road, Charlotte, NC 28277.
On November 6, 2025, BHF and Aquarian Capital LLC
(“Aquarian”) announced that they had entered into a definitive agreement under which an affiliate of Aquarian will acquire BHF. This transaction is subject to
the satisfaction or waiver of customary closing conditions, including receipt of applicable regulatory approvals. Subject to such approvals and the satisfaction or waiver of the other conditions, the transaction is expected to be consummated in 2026.
Upon the consummation of the transaction, Aquarian will become the ultimate parent of BHF and BLIC will remain an indirect wholly-owned subsidiary of BHF. Although Aquarian will replace BHF as BLIC’s ultimate parent, BLIC will continue in its present role as the issuer of your Policy. All of your rights and benefits under your Policy and BLIC’s obligations under the Policy will remain unchanged.
Founded in 2017, Aquarian is a diversified global holding company
with a strategic portfolio of insurance and asset management solutions. Aquarian is headquartered in New York, NY.
The assets of the Separate Account are held in our name on behalf of the Separate Account and legally belong to us. These assets are subject to the claims of the creditors of BLIC. We are obligated to pay all money we owe under the Policies—such as Death Benefits, Policy Proceeds, and Distribution
Payments— and these obligations are subject to our claims-paying ability. These amounts are
not guaranteed by any other party. If the obligation exceeds the assets of the Separate Account, amounts
will be transferred to the Separate Account from the General Account. We guarantee all benefits
relating to your value in the Indexed Account, regardless of
whether assets supporting the Indexed Account are held in a separate account or our General
Account. An owner should look to the claims paying ability of BLIC. We issue other annuity contracts and life insurance policies where we pay all money we owe under those
contracts and policies from our General Account. The Separate Account is non-insulated, meaning
that all of the assets of the Separate Account are chargeable with the claims of any of our policy owners and are subject to the liabilities arising from any of our other
business. BLIC is regulated as an insurance company under state law, which includes, generally,
limits on the amount and type of investments in its General Account. However, there is no guarantee that we will be able to meet our claims paying obligations; there are
risks to purchasing any insurance product.
When you make a premium payment to the Indexed Accounts of the Policy, the Net Premium applied to an Indexed Account is held in the Separate Account. It is a non-insulated, non-unitized separate account established under Delaware law. We have exclusive and absolute ownership and control of the assets of the Separate Account. You do not share in the investment performance of assets allocated to the Separate Account. All investment income, gains and losses, whether or not realized, from assets allocated to the Separate Account are borne by BLIC. The obligations under the Policy are independent of the investment performance of the Separate Account and are our obligations. We are not obligated to invest according to specific guidelines or strategies except as may be required by Delaware and other state insurance laws.
We will maintain in the Separate Account assets with an aggregate value at least equal to the Policy reserves associated with the Indexed Accounts of the Separate Account.
We must invest our assets, including those
in the Separate Account, according to applicable state laws regarding the nature, quality and
diversification of investments that may be made by life insurance companies. In general, these laws permit investments, within specified limits and subject to certain
qualifications, in Federal, state and municipal obligations, corporate bonds, preferred and common stocks, real estate mortgages, real estate and certain other
investments.
ANNUAL STATEMENT
Each year, or more often if required by law or regulation, we will send you a statement that shows current information, as of a date not more than four months prior to the date of the mailing. The statement will show:
(i)
The beginning and end dates of the current report period;
(ii)
The Cash Value at the beginning and the end of the current report period;
(iii)
The amounts that have been credited or debited during the current report period,
(defined by type);
(iv)
The Policy Loan Balance, if any, at the end of the current report period;
(v)
The death benefit at the end of the current report period; and
(vi)
The Cash Surrender Value, if any, at the end of the current report period.
If assuming guaranteed interest, mortality and expense charges, and continued Planned Premium Payments, the Cash Surrender Value will not be sufficient to maintain the Policy in force until the end of the next reporting period, a notification to this effect will be included in the report.
Such statements will be sent to your last known address on our
records. You will have sixty (60) days from the date you receive such statement to inform us of any errors, otherwise such statement will be deemed final and
correct.
DISTRIBUTION OF THE POLICIES
Brighthouse Securities, LLC (“Brighthouse Securities”) is the principal underwriter and distributor of the securities offered through this prospectus. Brighthouse Securities is our affiliate and its principal executive offices are located at 11225 North Community House Road, Charlotte, NC 28277. Both we and Brighthouse Securities are indirect, wholly owned
subsidiaries of BHF. Brighthouse Securities is a member of the Financial Industry Regulatory Authority (FINRA). FINRA provides background information about broker-dealers and their registered representatives through FINRA BrokerCheck. You may contact the FINRA BrokerCheck Hotline at 1-800-289-9999 or log on to www.finra.org. An
investor brochure that includes information describing FINRA BrokerCheck is available through the Hotline or on-line.
Brighthouse Securities is not obligated to take and pay for, and is not required to sell, any specific number or dollar amount of Policies. Brighthouse Securities, and in certain cases, we, have entered into selling agreements with unaffiliated selling firms for the sale of the Policies. No selling firms are affiliated with us or Brighthouse Securities. We pay compensation to Brighthouse Securities for sales of the Policies by selling firms. We also pay amounts to Brighthouse Securities that may be used for its operating and other expenses, including the following sales expenses: compensation and bonuses for Brighthouse Securities’ management team, advertising expenses and other expenses of distributing the Policies. Brighthouse Securities’ management team and registered representatives also may be eligible for non-cash compensation items that we may provide jointly with Brighthouse Securities. Non-cash items include conferences, seminars and trips (including travel, lodging and meals in connection therewith), entertainment, merchandise and other similar items.
As noted above, Brighthouse Securities, and in certain cases, we, have entered into selling agreements with selling firms for the sale of the Policies. Selling firms receive commissions, and may receive some form of non-cash compensation. Certain selected selling firms receive additional compensation (described below under “Additional Compensation for Selected Selling Firms”). These commissions and other incentives or payments are not charged directly to Owners. We intend to recoup commissions and other sales expenses through the charges and deductions under the Policy. A portion of the payments made to selling firms may be passed on to their financial representatives in accordance with the selling firms’ internal compensation programs. Those programs may also include other types of cash and non-cash compensation and other
benefits. Financial representatives of the selling firms may also receive non-cash compensation, pursuant to their firm’s guidelines, directly from us or Brighthouse Securities.
Compensation Paid to Selling Firms. Brighthouse Securities pays compensation to all selling firms in the form of commissions and may also provide
certain types of non-cash compensation. The maximum commissions paid for sale of the Policies are as follows: 120% of premiums paid up to the commissionable target premium,
and 2% of premiums paid in excess of commissionable target premium in Policy year 1; and 2% of all premiums paid in Policy year 2 thereafter. Brighthouse Securities may also provide non-cash compensation items that we may provide jointly with Brighthouse
Securities. Non-cash items may include expenses for conference or seminar trips, certain gifts, prizes and awards.
Ask your financial
representative for further information about what payments your financial representative and the selling firm for which he or she works may receive in connection with your
purchase of a Policy.
Additional Compensation for Selected Selling Firms. Brighthouse Securities
has entered into distribution arrangements with certain selected unaffiliated selling firms. Under these arrangements Brighthouse Securities may pay additional compensation to selected selling firms, including marketing allowances, introduction fees, persistency payments, preferred status fees and industry conference fees. Marketing allowances are periodic payments to certain selling firms, the amount of which may be an annual flat fee, or in some cases, depends on cumulative periodic (usually quarterly) sales of our insurance contracts (including the Policies) and may also depend on meeting thresholds in the sale of certain of our insurance contracts (other than the Policies). They may also include payments we make to cover the cost of marketing or other support services provided for or by registered representatives who may sell our products. Introduction fees are payments to selling firms in connection with the addition of our products to the selling firm’s line of investment products, including expenses relating to establishing the data communications systems necessary for the selling firm to offer, sell and administer our products. Persistency payments are periodic payments based on account values of our insurance contracts (including Cash Values of the Policies) or other persistency standards. Preferred status fees are paid to obtain preferred treatment in selling firms’ marketing programs, which may include marketing services, participation in marketing meetings, listings in data resources and increased access to their financial representatives. Industry conference fees are amounts paid to cover in part the costs associated with sales conferences and educational seminars for selling firms’ financial representatives.
The additional types of compensation discussed above are not offered to all selling firms. The terms of any particular agreement governing compensation may vary among selling firms and the amounts may be significant. The prospect of receiving, or the receipt of, additional compensation as described above may provide selling firms and/or their financial representatives with an incentive to favor sales of the Policies over other life insurance contracts (or other investments) with respect to which selling firm does not receive additional compensation, or lower levels of additional compensation. You may wish to take such payment arrangements into account when considering and evaluating any recommendation relating to the Policies. For more information about any such additional compensation arrangements, ask your financial representative.
In addition to the distribution arrangements discussed above,
Brighthouse Securities has entered into wholesaling agreements with wholesaling firms to provide marketing and training support services to selling firms and the registered
representatives of selling firms. These services may include, but not be limited to, training and promotional support for the solicitation, sale and on-going servicing of the Policies by the selling firms. Brighthouse Securities pays compensation to wholesaling firms in connection with these services.
We offer a Fixed Account. Please
refer to your Policy and Appendix C for more information.
RESTRICTIONS ON FINANCIAL TRANSACTIONS
Federal laws designed to counter terrorism and prevent money laundering might, in certain circumstances, require us to block an Owner’s ability to make certain transactions and thereby refuse to accept any request for transfers Surrenders, or death benefits, until instructions are received from the appropriate regulator. We may also be required to provide additional information about you and your Policy to government regulators.
We will treat your request for a
Policy transaction, or your submission of the premium payment, as received by us if we receive a request conforming to our administrative procedures or the premium payment
at our Administrative Office on any Business Day before 4:00 PM Eastern Standard Time. We will treat your submission of the premium payment as received by us if we receive it at our Administrative Office on any Business Day before 4:00 PM Eastern Standard Time or
when the NYSE closes, whichever is earlier. If we receive the request, or if we (or our designee)
receive the premium payment, on any Business Day on or after 4:00 PM Eastern Standard Time or
when the NYSE closes, whichever is earlier, then the request or payment will be treated as received on the next day. If you send your premium payment or
transaction requests to an address other than the one we have designated for receipt of such premium payment or requests, as indicated in the chart below, we
may return the premium payment to you, or there may be a delay in applying the premium payment or processing the transaction.
The Administrative Office for various
Policy transactions is as follows:
Applications when purchasing the
Policy, including initial Premium
Payments |
Brighthouse Life Insurance Company
P.O. Box 4365
Clinton, IA 52733-4365 Fax: (877) 245-2964 Or through your financial representative |
Subsequent Premium Payments or
Loan Repayments |
Brighthouse Life Insurance Company
P.O. Box 956067
St. Louis, MO 63195-6067 Fax: (877) 246-8424 |
| |
Brighthouse Life Insurance Company
P.O. Box 4330
Clinton, IA 52733-4330 Fax: (877) 245-8163 |
All Other Policy Transactions and
Inquiries, including Surrenders, Loans,
Transfers, Beneficiary and Ownership
Changes, and Cancellations (Right to
Examine Policy Period) |
Brighthouse Life Insurance Company P.O. Box 4301 Clinton, IA 52733-4301
Phone: (800) 882-1292 Monday through Friday, 8:30AM to 6:30PM Eastern Time Or Fax to: Policyholder Services (877) 246-8424 |
Some of the requests for service that may be made by telephone
include transfers of your Cash Value into Indexed Account(s) or the Fixed Account. We may from time to time permit requests for other types of transactions to be made by
telephone. All transaction requests must be in a form satisfactory to us. Contact us for further information. Some selling firms may restrict the ability of their financial representatives to convey transaction requests by telephone on your behalf.
We are not a fiduciary and do not provide investment advice or make recommendations regarding insurance or investment products. Ask your financial representative for guidance regarding any requests or elections and for information about your particular investment needs. Please bear in mind that your financial representative, or any financial firm or financial professional with whom you consult for advice, acts on your behalf, not ours. We are not party to any agreement between you and your financial representative. We do not recommend and are not responsible for any securities transactions or investment strategies involving securities.
A request or transaction generally is considered in Good Order if
it complies with our administrative procedures and the required information is complete and accurate. A request or transaction may be rejected or delayed if not in Good
Order. If you have any questions, you should contact us or your financial representative before submitting the form or request. We will use reasonable procedures such as requiring certain identifying information, tape recording the telephone instructions, and providing written confirmation of the transaction, in order to confirm that instructions communicated by telephone or other means are genuine. Any telephone instructions reasonably believed by us to be genuine will be your responsibility, including losses arising from any errors in the communication of instructions. As a result of this policy, you will bear the risk of loss. If we do not employ reasonable procedures to confirm that instructions communicated by telephone are genuine, we may be liable for any losses due to unauthorized or fraudulent transactions. All other requests and
elections under your Policy must be in writing, signed by the proper party, and include any necessary documentation to be effective. In writing means in a
form satisfactory to us and received at our Administrative Office at the addresses specified above or by fax at the numbers specified above. If acceptable to us, requests or elections relating to Beneficiaries
and Ownership will take effect as of the date signed unless we have already acted in reliance on the prior status. We are not responsible for the validity of any written request or action.
Telephone and computer systems may not always be available. Any
telephone or computer system, whether it is yours, your service provider’s, your financial representatives, or ours, can experience outages or slowdowns for a variety
of reasons. These outages or slowdowns may delay or prevent our processing of your request. Although we have taken precautions to help our systems handle heavy use, we cannot promise complete reliability under all circumstances. If you experience technical difficulties or problems, you should make your transaction request in writing to our Administrative Office.
Good Order
A request or transaction generally is considered in “Good Order” if it complies with our administrative procedures and the required information is complete and accurate. A request or transaction may be rejected or delayed if not in Good Order. Good Order generally means the actual receipt by us of the instructions relating to the requested transaction in writing (or, when permitted, by telephone) along with all forms, information and supporting legal documentation necessary to affect the transaction. This information and documentation generally includes to the extent applicable to the transaction: your completed application; your policy number; the transaction amount (in dollars or percentage terms); the names and allocations to and/or from the Buffer Options, or the Fixed Account if applicable, affected by the requested transaction; the signatures of all Policy Owners (exactly as indicated on the policy), if necessary; Social Security Number or Tax I.D.; and any other information or supporting documentation that we may require, including any spousal or Joint Owner’s consents. With respect to premium payments, Good Order also generally includes receipt by us of sufficient funds to effect the purchase. We may, in our sole discretion, determine whether any particular transaction request is in Good Order, and we reserve the right to change or waive any Good Order requirement at any time. If you have any questions, you should contact us or your financial representative before submitting the form or request.
We will send out written statements confirming that a transaction was recently completed. Unless you inform us of any errors within 60 days of receipt, we will consider these communications to be accurate and complete.
In the ordinary course of business, BLIC, similar to other
life insurance companies, is involved in lawsuits (including class action lawsuits), arbitrations and other legal proceedings. Also, from time to time, state and Federal
regulators or other officials conduct formal and informal examinations or undertake other actions dealing with various aspects of the financial services and insurance industries. In some legal proceedings involving insurers, substantial damages have been sought and/ or material settlement payments have been made.
It is not possible to predict with certainty the ultimate outcome
of any pending legal proceeding or regulatory action. However, BLIC does not believe any such action or proceeding will have a material adverse effect upon the ability of Brighthouse Securities to perform its contract with BLIC or of BLIC to meet its obligations under the contracts.
Legal matters in connection with Federal laws and regulations
affecting the issue and sale of the Policies described in this prospectus and the organization of BLIC, its authority to issue such Policies under Delaware law and the
validity of the forms of the Policies under Delaware law have been passed on by legal counsel for BLIC.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING
FIRM
The financial statements of Brighthouse Life Insurance Company incorporated by reference in this Prospectus have been audited by Deloitte & Touche LLP, an independent registered public accounting firm, as stated
in their report. Such financial statements are incorporated by reference in reliance upon the report of such firm, given their authority as experts in accounting and auditing.
Policies issued in your state may provide different
features and benefits from, and impose different costs than, those described in this prospectus because of state law variations. These differences include, among other
things, Free Look rights, age issuance limitations, transfer rights and limitations, the right to reject a premium payment, the requirements for unisex life insurance rates and the general availability of certain features. This prospectus describes all the material features of the Policy. Please refer to Appendix F
for a summary of the states where certain Policy features and/or benefits are either not available as of the date of this prospectus or vary from the Policy’s features
and benefits as described in this prospectus. If you would like to review a copy of the Policy
and any endorsements, contact our Administrative Office.
ELECTRONIC DELIVERY
As Owner, you may elect to receive electronic delivery of current prospectuses related to the Policy and other Policy related documents. Contact us at our website at www.brighthousefinancial.com for more information and to enroll.
We reserve the right to amend the Policies to comply with applicable Federal or state laws or regulations. We will notify you in writing of any such amendments.
INFORMATION INCORPORATED BY
REFERENCE
Under the Securities Act of 1933, BLIC has filed with the SEC a registration statement (the “Registration Statement”) relating to the Policies offered by this prospectus. This prospectus has been filed as a part of the Registration Statement and does not contain all of the information set forth in the Registration Statement and the exhibits and reference is hereby made to such Registration Statement and exhibits for further information relating to BLIC and the Policies.
We incorporate by reference BLIC’s Annual Report on Form 10-K for the year ended December 31, 2025 as filed with the
SEC on February 27, 2026 via Edgar File No. 033-03094
, Quarterly Report on Form 10-Q for the period ending March 31, 2026 as filed with the SEC on May 11, 2026 via Edgar File No.
033-03094, and
Quarterly Report on Form 10-Q for the period ending June 30, 2026 as filed with the SEC on August 10, 2026 via Edgar File No.
033-03094. The Annual
Report contains additional information about BLIC, including audited financial statements for BLIC’s latest fiscal year. In addition, all documents subsequently filed by BLIC pursuant to Sections 13(a), 13(c), 14 or 15(d) of the Securities Exchange Act of 1934, as amended (the “Exchange Act”) prior to the termination of the offering, are also incorporated by reference into this prospectus. We are not incorporating by reference any documents or information deemed to have been furnished instead of filed under SEC rules, such as current reports on Form 8-K furnished under Item 2.02 or Item 7.01.
If requested, BLIC will furnish, without charge, a
copy of any and all of the reports or documents that have been incorporated by reference into this prospectus. You may direct your requests to BLIC Administrative Office at
100 Centerview Drive, Suite 100 Charlotte, NC 37214. The telephone number is
1-800-882-1292. You may also access the incorporated reports and other documents at www.brighthousefinancial.com.
BLIC files periodic reports as required under the Exchange Act
(including Form 10-K, 10-Q and 8-K). You may also read and copy any materials that BLIC files with the SEC at the SEC’s Public Reference Room at 100 F Street, N.E.,
Washington, DC 20549. The public may obtain information on the operation of the Public Reference Room by calling the SEC at 1-800-SEC-0330. The SEC maintains
an Internet site that contains reports, proxy and information statements, and other information regarding issuers that file electronically with the SEC at http://www.sec.gov.
DISCLOSURE OF
COMMISSION POSITION ON INDEMNIFICATION
FOR SECURITIES ACT LIABILITIES
Pursuant to applicable provisions of BLIC’s by-laws or internal corporate policies adopted by BLIC or BHF, the directors, officers and
other controlling persons of BLIC and of BLIC’s affiliate and principal underwriter, Brighthouse Securities, who are made or threatened to be made a party to an action
or proceeding, may be eligible to obtain indemnification against judgments, fines, amounts paid in settlement and reasonable expenses, including attorneys’ fees,
incurred as a result of such action or proceeding. Under the principal underwriting agreement between BLIC and Brighthouse Securities, the parties have agreed to indemnify each other against certain liabilities and expenses from legal proceedings arising out of Brighthouse Securities’ distribution of the Policies.
Insofar as indemnification for liabilities arising under the
Securities Act of 1933 may be permitted to directors, officers or persons controlling BLIC pursuant to the foregoing provisions, BLIC has been informed that in the opinion
of the Securities and Exchange Commission such indemnification is against public policy as expressed in the Securities Act of 1933 and is therefore unenforceable.
(THIS PAGE INTENTIONALLY LEFT BLANK.)
Appendix A
BLIC uses the Indices under license from the
Indices’ respective publishers. The following information about the Indices is included in this prospectus in accordance with BLIC’s license agreements with the
publishers of the Indices:
S&P Opco, LLC requires that the following disclaimer be included in this prospectus:
The S&P 500® is a product of S&P Dow Jones Indices LLC or its affiliates (“SPDJI”) and has been licensed for use by affiliates of Brighthouse Financial, Inc., including Brighthouse Services, LLC and Brighthouse Life Insurance Company (collectively, “Brighthouse Financial”). S&P®, S&P 500®, US 500, The 500®, iBoxx®, iTraxx® and CDX® are trademarks of S&P Global, Inc. or its affiliates (“S&P”); Dow Jones® is a registered trademark of Dow Jones Trademark Holdings LLC
(“Dow Jones”); and these trademarks have been licensed for use by SPDJI and sublicensed for certain purposes by Brighthouse Financial. It is not possible to invest directly in an index. Brighthouse SmartGuard Plus® is not sponsored, endorsed, sold or promoted by SPDJI, Dow Jones, S&P, any of their respective affiliates (collectively, “S&P Dow Jones Indices”). S&P Dow Jones Indices makes no representation or warranty, express or implied, to the owners of Brighthouse SmartGuard Plus® or any member of the public regarding the advisability of investing in securities generally or in Brighthouse SmartGuard Plus® particularly or the ability of the S&P 500® to track general market performance. Past performance of an index is not an indication or guarantee of future
results. S&P Dow Jones Indices’ only relationship to Brighthouse Financial with respect to the S&P 500® is the licensing of the Index and certain trademarks, service marks
and/or trade names of S&P Dow Jones Indices and/or its licensors. The 500® is determined, composed and calculated by S&P Dow Jones Indices
without regard to Brighthouse Financial or Brighthouse SmartGuard Plus®. S&P Dow Jones Indices has no obligation to take the needs of
Brighthouse Financial or the owners of Brighthouse SmartGuard
Plus® into consideration in determining, composing or calculating the 500®. S&P Dow Jones Indices has no obligation or liability in connection with the administration, marketing or
trading of Brighthouse SmartGuard Plus®. There is no assurance that investment products based on the S&P 500®
will accurately track index performance or provide positive investment returns. S&P Dow Jones
Indices LLC is not an investment adviser, commodity trading advisory, commodity pool operator, broker dealer, fiduciary, promoter” (as defined in the Investment Company Act of 1940, as amended), “expert” as enumerated within 15 U.S.C. § 77k(a) or tax advisor. Inclusion of a security, commodity, crypto currency or other asset within an index is not a recommendation by S&P Dow Jones Indices to buy, sell, or hold such security, commodity, crypto currency or other asset, nor is it considered to be investment advice or commodity trading advice.
NEITHER S&P DOW JONES INDICES NOR THIRD PARTY LICENSOR
GUARANTEES THE ADEQUACY, ACCURACY, TIMELINESS AND/OR THE COMPLETENESS OF THE S&P 500® INDEX OR ANY DATA RELATED THERETO OR ANY COMMUNICATION, INCLUDING BUT NOT LIMITED TO, ORAL OR WRITTEN COMMUNICATION (INCLUDING ELECTRONIC COMMUNICATIONS) WITH RESPECT
THERETO. S&P DOW JONES INDICES SHALL NOT BE SUBJECT TO ANY DAMAGES OR LIABILITY FOR ANY ERRORS, OMISSIONS, OR DELAYS THEREIN. S&P DOW JONES INDICES MAKES
NO EXPRESS OR IMPLIED WARRANTIES, AND EXPRESSLY DISCLAIMS ALL WARRANTIES, OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE OR AS TO RESULTS TO BE OBTAINED BY BRIGHTHOUSE FINANCIAL, OWNERS OF BRIGHTHOUSE SMARTGUARD PLUS®, OR ANY OTHER PERSON OR ENTITY FROM THE USE OF THE S&P 500® INDEX OR WITH RESPECT TO ANY DATA RELATED THERETO. WITHOUT LIMITING ANY OF THE FOREGOING, IN NO EVENT
WHATSOEVER SHALL S&P DOW JONES INDICES BE LIABLE FOR ANY INDIRECT, SPECIAL, INCIDENTAL, PUNITIVE, OR CONSEQUENTIAL DAMAGES INCLUDING BUT NOT LIMITED TO, LOSS OF PROFITS, TRADING LOSSES, LOST TIME OR GOODWILL, EVEN IF THEY HAVE BEEN ADVISED OF THE
POSSIBILITY OF SUCH DAMAGES, WHETHER IN CONTRACT, TORT, STRICT LIABILITY, OR OTHERWISE. S&P DOW JONES INDICES HAS NOT
REVIEWED, PREPARED AND/OR CERTIFIED ANY PORTION OF, NOR DOES S&P DOW JONES INDICES HAVE ANY CONTROL OVER, THE LICENSEE BRIGHTHOUSE SMARTGUARD PLUS® REGISTRATION STATEMENT, PROSPECTUS OR OTHER OFFERING MATERIALS. THERE ARE NO THIRD-PARTY BENEFICIARIES OF ANY
AGREEMENTS OR ARRANGEMENTS BETWEEN S&P DOW JONES INDICES AND BRIGHTHOUSE FINANCIAL, OTHER THAN THE LICENSORS OF S&P DOW JONES INDICES.
Frank Russell Company requires that the following disclaimer be included in this prospectus:
Brighthouse SmartGuard Plus® is not sponsored, endorsed, sold or promoted by Frank Russell Company
(“Russell”). Russell makes no representation or warranty, express or implied, to the owners of Brighthouse SmartGuard Plus® or any member of the public regarding the advisability of investing in securities generally or in Brighthouse SmartGuard Plus® particularly or the ability of the Russell 2000® Index to track general stock market performance or a segment of the same. Russell’s publication of the
Russell 2000® Index in no way suggests or implies an opinion
by Russell as to the advisability of investment in any or all of the securities upon which the Russell 2000® Index is based. Russell’s only relationship to
affiliates of Brighthouse Financial, Inc., including Brighthouse Services, LLC and Brighthouse Life Insurance Company (collectively, “Brighthouse Financial”) is the licensing of certain trademarks and trade names of Russell and of the Russell 2000® Index which is determined, composed and calculated by Russell without regard to Brighthouse Financial or Brighthouse SmartGuard
Plus®. Russell is not responsible for and has not reviewed Brighthouse
SmartGuard Plus® nor any associated literature or publications and Russell makes no representation or warranty express or implied as to their accuracy or completeness, or otherwise. Russell reserves the right, at any time and without notice, to alter, amend, terminate or in any way change the Russell 2000® Index. Russell has no obligation or liability in connection with the administration, marketing or trading of
Brighthouse SmartGuard Plus®.
RUSSELL DOES NOT GUARANTEE THE ACCURACY AND/OR THE COMPLETENESS OF THE RUSSELL 2000® INDEX OR ANY DATA INCLUDED THEREIN AND RUSSELL SHALL HAVE NO LIABILITY FOR ANY ERRORS, OMISSIONS, OR INTERRUPTIONS THEREIN.
RUSSELL MAKES NO WARRANTY, EXPRESS OR IMPLIED, AS TO RESULTS TO BE OBTAINED BY BRIGHTHOUSE FINANCIAL, INVESTORS, OWNERS OF BRIGHTHOUSE SMARTGUARD PLUS® OR ANY OTHER PERSON OR ENTITY FROM THE USE OF THE RUSSELL 2000® INDEX OR ANY DATA INCLUDED THEREIN. RUSSELL MAKES NO EXPRESS OR IMPLIED WARRANTIES, AND EXPRESSLY DISCLAIMS
ALL WARRANTIES OF MERCHANTABILITY OR FITNESS FOR A PARTICULAR PURPOSE OR USE WITH RESPECT TO THE RUSSELL 2000® INDEX OR ANY DATA INCLUDED THEREIN. WITHOUT LIMITING ANY OF THE FOREGOING, IN NO EVENT SHALL RUSSELL HAVE ANY LIABILITY FOR ANY SPECIAL, PUNITIVE, INDIRECT, OR
CONSEQUENTIAL DAMAGES (INCLUDING LOST PROFITS), EVEN IF NOTIFIED OF THE POSSIBILITY OF SUCH DAMAGES.
MSCI Inc. requires that the following disclaimer be included in this prospectus:
BRIGHTHOUSE SMARTGUARD PLUS® IS NOT SPONSORED, ENDORSED, SOLD OR PROMOTED BY MSCI INC.
(“MSCI”), ANY OF ITS AFFILIATES, ANY OF ITS INFORMATION PROVIDERS OR ANY OTHER THIRD PARTY INVOLVED IN, OR RELATED TO, COMPILING, COMPUTING OR CREATING ANY MSCI INDEX (COLLECTIVELY, THE “MSCI PARTIES”). THE MSCI INDEXES ARE THE EXCLUSIVE PROPERTY OF MSCI. MSCI AND THE MSCI INDEX NAMES ARE SERVICE MARK(S) OF MSCI OR ITS AFFILIATES AND
HAVE BEEN LICENSED FOR USE FOR CERTAIN PURPOSES BY AFFILIATES OF BRIGHTHOUSE FINANCIAL, INC. INCLUDING BRIGHTHOUSE SERVICES, LLC, BRIGHTHOUSE LIFE INSURANCE COMPANY, AND BRIGHTHOUSE LIFE INSURANCE COMPANY OF NY
(COLLECTIVELY, “BRIGHTHOUSE FINANCIAL”). NONE OF THE MSCI PARTIES MAKES ANY REPRESENTATION OR WARRANTY, EXPRESS OR IMPLIED, TO THE ISSUER OR OWNERS OF THIS
PRODUCT OR ANY OTHER PERSON OR ENTITY REGARDING THE ADVISABILITY OF INVESTING IN PRODUCTS GENERALLY OR IN THIS PRODUCT PARTICULARLY OR THE ABILITY OF ANY MSCI INDEX TO TRACK CORRESPONDING STOCK MARKET PERFORMANCE. MSCI OR ITS AFFILIATES ARE THE LICENSORS OF CERTAIN
TRADEMARKS, SERVICE MARKS AND TRADE NAMES AND OF THE MSCI INDEXES WHICH ARE DETERMINED, COMPOSED AND CALCULATED BY MSCI WITHOUT REGARD TO THIS PRODUCT OR THE ISSUER OR
OWNERS OF THIS PRODUCT OR ANY OTHER PERSON OR ENTITY. NONE OF THE MSCI PARTIES HAS ANY OBLIGATION TO TAKE THE NEEDS OF THE ISSUER OR OWNERS OF THIS PRODUCT OR ANY OTHER PERSON OR ENTITY INTO CONSIDERATION IN DETERMINING, COMPOSING OR
CALCULATING THE MSCI INDEXES. NONE OF THE MSCI PARTIES IS RESPONSIBLE FOR OR HAS PARTICIPATED IN THE DETERMINATION OF THE TIMING OF, PRICES AT, OR QUANTITIES OF THIS PRODUCT TO BE ISSUED OR IN THE DETERMINATION
OR CALCULATION OF THE EQUATION BY OR THE CONSIDERATION INTO WHICH THIS PRODUCT IS REDEEMABLE. FURTHER, NONE OF THE MSCI PARTIES HAS ANY OBLIGATION OR LIABILITY TO THE ISSUER OR OWNERS OF THIS PRODUCT OR ANY OTHER
PERSON OR ENTITY IN CONNECTION WITH THE ADMINISTRATION, MARKETING OR OFFERING OF THIS PRODUCT.
ALTHOUGH MSCI SHALL OBTAIN INFORMATION FOR INCLUSION IN OR FOR
USE IN THE CALCULATION OF THE MSCI INDEXES FROM SOURCES THAT MSCI CONSIDERS RELIABLE, NONE OF THE MSCI PARTIES WARRANTS OR GUARANTEES THE ORIGINALITY, ACCURACY AND/OR THE COMPLETENESS OF ANY MSCI INDEX OR ANY DATA INCLUDED THEREIN. NONE OF THE MSCI
PARTIES MAKES ANY WARRANTY, EXPRESS OR IMPLIED, AS TO RESULTS TO BE OBTAINED BY THE ISSUER OF THE PRODUCT, OWNERS OF THE PRODUCT, OR ANY OTHER PERSON OR ENTITY, FROM THE USE
OF ANY MSCI INDEX OR ANY DATA INCLUDED THEREIN. NONE OF THE MSCI PARTIES SHALL HAVE ANY LIABILITY FOR ANY ERRORS, OMISSIONS OR INTERRUPTIONS OF OR IN CONNECTION WITH ANY MSCI INDEX OR ANY DATA INCLUDED THEREIN. FURTHER, NONE OF THE MSCI
PARTIES MAKES ANY EXPRESS OR IMPLIED WARRANTIES OF ANY KIND, AND THE MSCI PARTIES HEREBY EXPRESSLY DISCLAIM ALL WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR
PURPOSE, WITH RESPECT TO EACH MSCI INDEX AND ANY DATA INCLUDED THEREIN. WITHOUT LIMITING ANY OF THE FOREGOING, IN NO EVENT SHALL ANY OF THE MSCI PARTIES HAVE ANY LIABILITY FOR ANY DIRECT, INDIRECT, SPECIAL, PUNITIVE, CONSEQUENTIAL OR ANY OTHER
DAMAGES (INCLUDING LOST PROFITS) EVEN IF NOTIFIED OF THE POSSIBILITY OF SUCH DAMAGES.
No purchaser, seller or holder of Brighthouse SmartGuard
Plus®, or any other person or entity, should use or refer to
any MSCI trade name, trademark or service mark to sponsor, endorse, market or promote this security without first contacting MSCI to determine whether MSCI’s permission is required. Under no circumstances may any person or entity claim any affiliation with MSCI without the prior written permission of MSCI.
Appendix B
Index Substitution Segment Value Example
The following example illustrates how we would calculate your Segment Value on a Segment Maturity Date when there is an Index substitution. We assume no loans are taken and there is no payment of the Accelerated Death Benefit, and a $100,000 payment into an Indexed Account with a 1-Year Term / Buffer 10 / S&P 500® Index with a Cap Rate of 10%. The Annual Deduction for each Policy Year will be taken from any Indexed Account according to the Policy Deduction Method. This example assumes no Annual Deduction.
Segment Value at Segment Start Date |
|
| |
|
| |
|
S&P 500® Closing Value of the Index on
Segment Start Date |
|
| |
|
| |
|
On date of Index Substitution halfway through the Segment
Term:
| |
|
Number of days since Segment Start Date |
|
Closing Value for S&P 500® Index |
|
Segment Index Performance for S&P 500® Index(1) |
|
| |
|
Closing Value for Russell 2000® Index on substitution
date |
|
Calculation of Segment Value at Segment Maturity Date:
Closing Value for Russell 2000® Index |
|
Segment Index Performance for S&P 500® Index(1) |
|
Segment Index Performance for Russell 2000® Index(2) |
|
Total Segment Index Performance for the Segment Term(3) |
|
| |
|
| |
|
Segment Performance Rate(4) |
|
| |
|
Segment Value at Segment Maturity Date(6) |
|
The following notes to the table above provide important calculations showing how certain values are determined.
(1)
Segment Index Performance is equal to the percentage change in the Closing Value
of the Index measured from the Segment Start Date to the date of the Index substitution. Segment Index Performance is calculated as follows:
(1330 [Value of Index at date of substitution] — 1400 [Value of Index at Segment Start Date])
÷ 1400 [Value of Index at Segment Start Date]) = –5%
(2)
Segment Index Performance is equal to the percentage change in the Closing Value
of the Index measured from the date of the Index substitution to the Segment Maturity Date. Segment Index Performance is calculated as follows:
(1375 [Value of Index at Segment Maturity Date] — 1250 [Value of Index at date of the substitution])
÷ 1250 [Value of Index at date of substitution]) = 10%
(3)
Since there was an Index substitution from the S&P 500® Index (initial Index) to the Russell 2000® Index (substituted Index), the total Segment Index Performance for the Segment Term is equal to the S&P 500® Index Value at Index substitution date divided by the S&P 500® Index Value at Segment Start Date multiplied by the Russell 2000® Index
Value
at Segment Maturity Date divided by the Russell 2000® Index
Value at the Index substitution date –1. Total Segment Index Performance for the Segment Term is calculated as follows:
(1330 [initial Index Value at Index substitution date] ÷ 1400 [initial Index Value at Segment Start Date])
x (1375 [substituted Index Value at Segment Maturity Date] ÷ 1250 [substituted Index at substitution date]) –1 = 4.5%
(4)
The Segment Performance Rate is equal to the Segment Index Performance (4.50%)
because the total Segment Index Performance for the Segment Term is greater than zero and less than the Cap Rate.
(5)
The Segment Credit is equal to the product of the current Segment Value (Segment
Value at the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) multiplied by the Segment Performance Rate. The Segment Credit is calculated as follows:
$100,000 [current
Segment Value] x 4.5% [Segment Performance Rate] = $4,500
(6)
The Segment Value at Segment Maturity Date is equal to the current Segment Value
(Segment Value at the Segment Start Date adjusted for any loans and Accelerated Death Benefit payment; there are no adjustments in the example) plus the Segment Credit. The Segment Value at Segment Maturity Date is calculated as follows:
$100,000 [current Segment Value] + $4,500 [Segment Credit] = $104,500
Appendix C
The Fixed Account is a funding option and is part of BLIC’s General Account assets. These General Account assets include all assets of BLIC
other than those held in the Separate Accounts sponsored by BLIC or its affiliates.
Any interest in the Fixed Account is not a security under the
Securities Act of 1933 and the Fixed Account is not registered under or regulated by the Investment Company Act of 1940. Accordingly, the Fixed Account is not offered by
virtue of the prospectus. Disclosure regarding the Fixed Account and the General Account is, however, subject to certain
provisions of the Federal securities laws relating to the accuracy and completeness of statements made in the prospectus.
Under the Fixed Account, BLIC assumes the risk of investment gain or loss and guarantees a specified interest rate. We guarantee that, at any time, the Fixed Account Cash Value will not be less than the amount of the premium payments allocated to the Fixed Account, plus interest credited as described below, less any applicable premium taxes.
Cash Value allocated to the Fixed Account and any transfers made to the Fixed Account become part of BLIC’s General Account, which supports insurance obligations. The General Account and any interest therein is not registered under, or subject to the provisions of, the Securities Act of 1933 or Investment Company Act of 1940. We will invest the assets of the Fixed Account at our discretion. Investment income from such Fixed Account assets will be allocated to us and to the Policies participating in the Fixed Account.
Investment income from the Fixed Account allocated to us includes
compensation for risks borne by us in connection with Fixed Account Policies. The amount of such investment income allocated to the Policies will vary from year to year in
our sole discretion at such rate or rates as we prospectively declare from time to time.
We guarantee that for the life of the Policy interest credited to your Fixed Account Cash Value beginning on the date we issue the Policy will not be accumulated at less than the Fixed Account Guaranteed Minimum Interest Rate allowed by state law. The current Fixed Account Guaranteed Minimum Interest Rate for any Policy we offer will not be less than 1%. We reserve the right to change the rate, at any time, subject to applicable state law. We will determine any interest we credit to amounts allocated to the Fixed Account in excess of the Fixed Account Guaranteed Minimum Interest Rate at our sole discretion. You assume the risk that interest credited to the Fixed Account may not exceed the Fixed Account Guaranteed Minimum Interest Rate for any given year. We have no specific formula for determining the interest rate. Some factors we may consider are regulatory and tax requirements, general economic trends and competitive factors.
Fixed Account Cash Value.
We credit interest to the portion of the Cash Value allocated to the Fixed Account. (See
“Interest Crediting” below.) The Fixed Account is part of our General Account. We guarantee that the interest credited to your initial allocation to the Fixed Account beginning on the date we issue the Policy will not be accumulated at less than the Fixed Account Guaranteed Minimum Interest Rate. However, we can change the interest rate at any time and such rate will not be less than the Fixed Account Guaranteed Minimum Interest Rate.
The initial Fixed Account Cash Value is the portion of the Net
Premium received and allocated to the Fixed Account, less the portion of the Annual Deduction charged to the Fixed Account.
On a Policy Anniversary, the Fixed Account Cash Value equals:
•
The Cash Value in the Fixed Account on the prior day; plus
•
Any Fixed Account interest credited on such amount since the prior day; plus
•
Any Net Premium paid on that date and allocated to the Fixed Account; plus
•
Any amount transferred from the Loan Account or an Indexed Account to the Fixed Account
on that date; less
•
Any amount transferred from the Fixed Account to an Indexed Account or the Loan Account
on that date; less
•
Any Cash Value reduction resulting from a payment under the Accelerated Death Benefit, on
that date; less
•
Any part of the Annual Deduction charged to the Fixed Account to cover the Policy Year
that starts on that day.
On any other day, the Fixed Account Cash Value equals:
•
The Cash Value in the Fixed Account on the prior day; plus
•
Any Fixed Account interest credited on such amount since the prior day; plus
•
Any Net Premium paid on that day and allocated to the Fixed Account; plus
•
Any amount transferred from the Loan Account to the Fixed Account on that day;
less
•
Any
amount transferred from the Fixed Account to the Loan Account on that day; less
•
Any Cash Value reduction resulting from a payment under the Accelerated Death
Benefit.
Interest Crediting. Interest will be
compounded and credited to the Fixed Account at an annual effective interest rate declared by us and not less than the Fixed Account Guaranteed Minimum Interest Rate.
Interest will be credited on amounts allocated to the Fixed Account through the effective date such amounts are Surrendered or transferred from the Fixed Account.
Appendix D
Guaranteed Distribution Rider Examples
The purpose of these examples is to illustrate how payments work under the GDR. The investment results shown are hypothetical and are not representative of past or future performance. Actual investment results may be more or less than those shown and will depend upon several factors, including the allocation made by an Owner and the Index Performance for the Indexed Account(s) chosen. Values are rounded for display purposes only.
Once eligible, Distribution Payments may be taken as loans from the Cash Value at the beginning of Policy Year 11. The amount available to be taken as Distribution Payments is described below.
A. Guaranteed Minimum Distribution Payment
The Guaranteed Minimum Distribution Payments are dollar amounts that are contractually declared at issue. They are shown in the Rider specifications page and generally increase depending upon when you begin Distribution Payments.
Assume you are a 50-year-old male, and your annual Planned Premium Payment is $10,000 a year for 10 years. You select an annual Distribution Payment Frequency for a lifetime Distribution Payment Duration. At issue, your contractually declared annual lifetime Guaranteed Minimum Distribution Payment at age 60 is $6,386.
Given the same scenario, your contractually
declared annual lifetime Guaranteed Minimum Distribution Payment at age 65 is $7,343 and at age 70 is $8,074.
B. Maximum Distribution Payment
The Maximum Distribution Payment is the greater of the Guaranteed
Minimum Distribution Payment (Example I) or the Cash Value multiplied by the Distribution Payment Rate (Example II). It is calculated at each Policy Anniversary prior to
exercising Distribution Payments.
The Maximum Distribution Payment will never be less than the
Guaranteed Minimum Distribution Payment. The Distribution Payment Rate is contractually declared at issue. They are shown in the Rider specifications page and generally
increase depending upon when you begin Distribution Payments.
Assume you are a 50-year-old male, and your annual Planned Premium Payment is $10,000 a year for 10 years. You select an annual Distribution Payment Frequency for a lifetime Distribution Payment Duration. At the beginning of Policy Year 11, your Cash Value is $90,000.
Your Distribution Payment Rate is 6.81%. Since the Cash Value
multiplied by the Distribution Payment Rate is $6,129 and is less than the Guaranteed Minimum Distribution Payment of $6,386, your Maximum Distribution Payment is
$6,386.
Assume you are a 50-year-old male, and your annual Planned Premium Payment is $10,000 a year for 10 years. You select an annual Distribution Payment Frequency for a lifetime Distribution Payment Duration. At the beginning of Policy Year 11, your Cash Value has grown to $110,233 assuming a 7% interest credited each year.
Your Distribution Payment Rate is 6.81%.
Since the Cash Value multiplied by the Distribution Payment Rate is $7,507 and is greater than the Guaranteed Minimum Distribution Payment of $6,386, your Maximum
Distribution Payment is $7,507.
C. Distribution Payment Duration
The Distribution Payment Duration is selected at issue and
determines how long Distribution Payments will be paid for. The available durations are 10-year, 20-year, or lifetime (up to Attained Age 121). After 10 Policy Years and at
the time of GDR exercise, a one-time change is allowed to the Distribution Payment Duration. The Distribution Payment Duration will last for the selected period assuming the Maximum Distribution Payment amount is being taken (Example I). However, the period Distribution Payments are paid for could extend beyond the selected Distribution Payment Duration if an amount less than the Maximum Distribution Payment is taken (Example II).
Example
I:
Assume you are a 50-year-old male, and your annual Planned
Premium Payment is $10,000 a year for 10 years. You select an annual Distribution Payment Frequency for a Distribution Payment Duration of 10 years. You elect to begin
taking Distribution Payments in Policy Year 11.
Your assumed Maximum Distribution Payment is $7,507, and you
elect to receive the maximum amount. Beginning in Policy Year 11, you will receive $7,507 each year for 10 years, with the last payment in Policy Year 20. The cumulative
amount received totals $75,070.
Assume you are a 50-year-old male, and your annual Planned Premium Payment is $10,000 a year for 10 years. You select an annual Distribution Payment Frequency for a Distribution Payment Duration of 10 years. You elect to begin taking Distribution Payments in Policy Year 11.
Your assumed Maximum Distribution Payment is $7,507; however, you
elect to receive only $6,000 a year. Beginning in Policy Year 11, you will receive $6,000 for 12 years until Policy Year 22, and $3,070 in the 13th year, or Policy Year 23. This is when the cumulative amount received totals $75,070, which equals the Maximum Distribution Payment multiplied by the Distribution Payment Duration.
A One-time Payment is available once Distribution Payments begin and if an amount less than the Maximum Distribution Payment amount is taken. This amount is only available once, provided your Distribution Payments have not been terminated.
The maximum One-time Payment is the lesser of:
1.
The difference between the cumulative Maximum Distribution Payments available to you
based on your chosen Distribution Payment Duration and Distribution Payment Frequency and the total Distribution Payments you have received since the Distribution Start Date; or,
2.
The
lesser of: three times the Maximum Distribution Payment or $150,000 (which is referred to as the One-time Payment Limit and is shown in the GDR).
For purposes of calculating the One-time Payment after a restart, the cumulative Maximum Distribution Payments available to you are from the Distribution Start Date to the One-time Payment calculation date, regardless of whether you suspended Distribution Payments at any time during that period.
Assume you are a 50-year-old male, and your annual Planned Premium Payment is $10,000 a year for 10 years. You select an annual Distribution Payment Frequency for a Distribution Payment Duration of 10 years. You elect to begin taking Distribution Payments in Policy Year 11.
Your assumed Maximum Distribution Payment is $7,507; however, you
elect to receive only
$6,000 a year. Beginning in Policy Year 11, you begin taking $6,000 each year. At any point after you begin taking Distribution Payments, a One-time Payment amount is available for the difference of the cumulative Maximum Distribution Payment at that time and the cumulative amount taken, up to a limit, which is the lesser of: three times the Maximum Distribution Payment or $150,000.
In Policy Year 11, your cumulative amount taken as Distribution
Payments is $6,000, and your available One-time Payment is $1,507, or the cumulative Maximum Distribution Payment minus the cumulative Distribution Payments taken. If
you elect to take the One-time Payment of $1,507, you will continue to receive $6,000 a year until the cumulative amount of the Maximum Distribution Payment multiplied by the Distribution Payment Duration of $75,070 has been reached.
In Policy Year 12, if you have not already taken the One-time Payment, your cumulative amount taken as Distribution Payments is $12,000, and your One-time Payment is $3,014, or the cumulative Maximum Distribution Payment minus the cumulative Distribution Payments taken. If you elect to take the One-time Payment of $3,014, you will continue to receive $6,000 a year until the cumulative amount of the Maximum Distribution Payment multiplied by the Distribution Payment Duration of $75,070 has been reached.
In Policy Year 13, if
you have not already taken the One-time Payment, your cumulative amount taken as Distribution Payments is $18,000, and your One-time Payment is $4,521, or the cumulative
Maximum Distribution Payment minus the cumulative Distribution Payments taken. If you elect to take the One-time Payment of $4,521, you will continue to receive $6,000 a year until the cumulative amount of the Maximum Distribution Payment multiplied by the Distribution Payment Duration of $75,070 has been reached.
In Policy Year 18, you are still receiving Distribution Payments
of $6,000. Your unloaned Cash Value prior to your next Distribution Payment is $4,000. The amount available for Distribution Payments is equal to your unloaned Cash Value of
$4,000. In order to receive your next Distribution Payment, we will increase your unloaned Cash Value to $6,000 so that the Distribution Payment can be made in the form of a loan.
Assume you are a 50-year-old male, and your annual Planned Premium Payment is $10,000 a year for 10 years. You select an annual Distribution Payment Frequency for a Distribution Payment Duration of 10 years. You elect to begin taking Distribution Payments in Policy Year 11.
Your assumed Maximum Distribution Payment is $7,507; however, you
elect to receive only $2,000 a year starting in year 11. In Policy Year 15, your cumulative amount taken as Distribution Payments is $10,000. Your cumulative Maximum Distribution Payment is $37,535. The difference between the two is $27,535. If you have not already taken the One-time Payment and you elect to take it, the maximum amount available would be limited to $22,521, which is the minimum of 3 times the Maximum Distribution Amount (3 x $7,507 = $22,521) or $150,000. You will continue to receive $2,000 a year until the cumulative amount of the Maximum Distribution Payment multiplied by the Distribution Payment Duration of $75,070 has been reached.
The One-time Payment is available once, at any time after
Distribution Payments begin, if the cumulative amounts taken as Distribution Payments is less than the cumulative Maximum Distribution Payment amount.
(THIS PAGE INTENTIONALLY LEFT BLANK.)
Appendix E
CASH VALUE ACCUMULATION TEST
In order to meet the Internal Revenue
Code’s definition of life insurance, your policy provides that the death benefit will not be less than what is required by the “cash value accumulation
test” under Section 7702(a)(1) of the Internal Revenue Code. This test will be used for the life of the Policy. (See “Death Benefit.”)
Sample minimum death benefit factors for selected ages of male and female insureds, in a nonsmoker risk class, are listed below.
| |
Minimum Death Benefit Factor |
| |
|
|
| |
|
|
| |
|
|
| |
|
|
| |
|
|
| |
|
|
| |
|
|
| |
|
|
| |
|
|
(THIS PAGE INTENTIONALLY LEFT BLANK.)
APPENDIX F
Certain Policy features and/or benefits described in this prospectus may vary or may not be available in your state, or may have been approved in your state after your Policy was issued and cannot be added. These variations are reflected in your Policy and in riders to your Policy. The following information is a summary of the states where certain Policy features and/or benefits are either not available as of the date of this prospectus or vary from the Policy’s features and benefits as described in this prospectus. See your financial representative or contact us for specific information that may be applicable to your state.
| |
|
|
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
If the Owner is age 60 or older, the
Free Look period is 30 days. For the
replacement of an existing policy, the
Free Look period is 30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
20 days. |
| |
|
You may return the policy for a refund
within 10 days after you receive it or
within 45 days of the date the
application was signed, whichever is
later. |
| |
|
The Free Look period is 14 days. For
the replacement of an existing policy,
the Free Look period is 30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
The Free Look period is 20 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
20 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
20 days. |
| |
|
For the replacement of an existing policy, the Free Look period is 30 days. |
| |
|
|
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
You may return the policy for a refund
within 10 days after you receive it or
within 45 days of the date the
application was signed, whichever is
later. For the replacement of an
existing policy, the Free Look period is
30 days. |
| |
|
You may return the policy for a refund
within 10 days after you receive it or
within 45 days of the date the
application was signed, whichever is
later. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
You may return the policy for a refund
within 10 days after you receive it or
within 45 days of the date the
application was signed, whichever is
later. For the replacement of an
existing policy, the Free Look period is
30 days. |
| |
|
The Free Look period is 20 days. For
the replacement of an existing policy,
the Free Look period is 20 days. |
| |
|
For the replacement of an existing policy, the Free Look period is 30 days. |
| |
|
|
| |
|
For the replacement of an existing
policy, the Free Look period is
20 days. |
| |
|
For the replacement of an existing
policy that was not issued to you by
BLIC, your right to cancel period is
20 days. For the replacement of an
existing policy that was issued to you
by BLIC, your right to cancel period is
45 days. |
| |
|
The Free Look period is 20 days. For
the replacement of an existing policy,
the Free Look period is 30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing
policy, the Free Look period is
30 days. |
| |
|
For the replacement of an existing policy, the Free Look period is 30 days. |
Part II
INFORMATION NOT REQUIRED IN PROSPECTUS
Item 14. Other Expenses of Issuance and Distribution
The following is an itemized list of the fees and expenses incurred in connection with the securities being offered. All of such fees and expenses, except for the Registration Fee, are estimated.
Accountant’s Fees and Expenses: $7,950
Legal Fees and Expenses: $9,000
Printing Expenses: $5,764
Item 15. Indemnification of Directors and Officers
Pursuant to applicable provisions of the Registrant’s
by-laws or internal corporate policies adopted by the Registrant or BHF, the directors, officers and other
controlling persons of the Registrant who are made or threatened to be made a party to an action or proceeding, may be eligible to obtain indemnification against judgments, fines,
amounts paid in settlement and reasonable expenses, including attorneys’ fees, incurred as a result of such action or proceeding. Under the principal underwriting agreement between the Registrant and the Underwriter, the parties have agreed to indemnify each
other against certain liabilities and expenses from legal proceedings arising out of the Underwriter’s distribution of the Contracts. BLIC also maintains insurance policies
insuring its directors and officers against certain liabilities they may incur in their capacity as such.
Exhibit
Number
Description
The undersigned registrant hereby undertakes as follows, pursuant to Item 512 of Regulation
S-K:
1.
To file, during any period in which offers or sales of the registered securities are being made, a post-effective amendment
to this registration statement:
i.
to include any prospectus required by Section 10(a)(3) of the Securities Act of 1933;
ii.
to reflect in the prospectus any facts or events arising after the effective date of the
registration statement (or the most recent post-effective amendment thereof) which, individually or in the aggregate, represent a fundamental change in the information set forth in the registration statement; Notwithstanding the foregoing, any increase
or decrease in volume of securities offered (if the total dollar value of securities offered would not exceed that which was registered) and any deviation from the low or high end
of the estimated maximum offering range may be reflected in the form of prospectus filed with the Commission
pursuant to Rule 424(b) if, in the aggregate, the changes in volume and price set represent no more than 20
percent change in the maximum aggregate offering price set forth in the “Calculation of Registration Fee” table in the effective registration statement, and
iii.
to include any material information with respect to the plan of distribution not previously
disclosed in the registration statement or any material change to such information in the registration statement.
Provided, however, that Paragraphs 1.i, 1.ii, and 1.iii do not apply if the information required to be included in a post-effective amendment by those paragraphs is contained in reports filed with or furnished to the Commission by the
registrant pursuant to section 13 or section 15(d) of the Securities Exchange Act of 1934 that are incorporated by reference in the registration statement, or is contained in a
form of prospectus filed pursuant to Rule 424(b) that is part of the registration statement.
2.
That, for the purpose of determining any liability under the Securities Act of 1933, each
such post-effective amendment shall be deemed to be a new registration statement relating to the securities offered therein, and the offering of such securities at that time shall be deemed to be the initial bona fide offering thereof.
3.
To remove from
registration by means of a post-effective amendment any of the securities being registered which remain unsold at the termination of the offering.
4.
That, for the purpose of determining liability under the Securities Act of 1933 to any purchaser, each prospectus filed
pursuant to Rule 424(b) as part of a registration statement relating to an offering, other than registration statements relying on Rule 430B or other than prospectuses filed in
reliance on Rule 430A, shall be deemed to be part of and included in the registration statement as of the date it is first used after effectiveness. Provided, however, that no statement made in a registration statement or prospectus that is part of the registration statement or made
in a document incorporated or deemed incorporated by reference into the registration statement or prospectus that is part of the registration statement will, as to a purchaser with
a time of contract of sale prior to such first use, supersede or modify any statement that was made in the registration statement or prospectus that was part of the registration statement or made in any such document immediately prior to such date of first use.
5.
That, for the purpose of determining liability of the registrant under the Securities Act of 1933 to any purchaser in the
initial distribution of the securities: The undersigned registrant undertakes that in a primary offering of securities of the undersigned registrant pursuant to this registration
statement, regardless of the underwriting method used to sell the securities to the purchaser, if the securities are offered or sold to such purchaser by means of any of the following communications, the undersigned registrant will be a seller to the purchaser and will be considered
to offer or sell such securities to such purchaser:
i.
Any preliminary
prospectus or prospectus of the undersigned registrant relating to the offering required to be filed pursuant to Rule 424;
ii.
Any free writing prospectus relating to the offering prepared by or on behalf of the
undersigned registrant or used or referred to by the undersigned registrant;
iii.
The portion of any
other free writing prospectus relating to the offering containing material information about the undersigned registrant or its securities provided by or on behalf of the
undersigned registrant; and
iv.
Any other communication that is an offer in the offering made by the undersigned registrant to
the purchaser.
6.
The undersigned registrant hereby undertakes that, for purposes of determining any
liability under the Securities Act of 1933, each filing of the registrant’s annual report pursuant to Section 13(a) or 15(d) of the Securities Exchange Act of 1934 that is incorporated by reference in the registration statement shall be deemed to be a new
registration statement relating to the securities offered therein, and the offering of such securities at that time shall be deemed to be the initial bona fide offering thereof.
7.
Insofar as
indemnification for liabilities arising under the Securities Act of 1933 may be permitted to directors, officers and controlling persons of the registrant pursuant to the foregoing
provisions, or otherwise, the registrant has been advised that in the opinion of the Securities and Exchange Commission such indemnification is against public policy as expressed in the Act and is, therefore, unenforceable. In the event that a claim for indemnification
against such liabilities (other than the payment by the registrant of expenses incurred or paid by a director, officer or controlling person of the registrant in the successful defense of any action, suit or proceeding) is asserted by such
director, officer or controlling person in connection with the securities being registered, the registrant will, unless in the opinion of its counsel the matter has been settled by
controlling precedent, submit to a court of appropriate jurisdiction the question whether such indemnification by it is against public policy as expressed in the Act and will be governed by the final adjudication of such issue.
INDEX TO
EXHIBITS
5.
Opinion and Consent of Counsel
23.
Consent of Independent Registered Public Accounting Firm
SIGNATURES
Pursuant to the requirements of the Securities Act of 1933, the registrant certifies that it has reasonable grounds to believe that it meets all of the requirements for filing on Form S-3 and has duly caused this registration statement to be
signed on its behalf by the undersigned, thereunto duly authorized, in the City of Charlotte, State of North Carolina, on October 19, 2026.
BRIGHTHOUSE LIFE INSURANCE COMPANY
(Registrant)
Kevin G. Finneran
Vice President
Pursuant to the requirements of the Securities Act of 1933, this registration statement has been signed by the following persons in the capacities indicated on October 19, 2026.
| |
Chairman of the Board, President, Chief Executive Officer and a Director |
| |
|
| |
Director and Vice President |
| |
|
| |
Director, Vice President and Chief Financial Officer |
| |
Vice President and Chief Accounting Officer |
/s/ Gianna H. Figaro-Sterling*
Gianna H. Figaro-Sterling |
Vice President and Controller |
*By: /s/ Michele H. Abate
Michele H. Abate, Attorney-In-Fact
October 19, 2026 |
|
* Brighthouse Life Insurance Company. Executed by Michele H. Abate,
Esquire on behalf of those indicated pursuant to powers of attorney filed herewith.
Opinion and Consent of Counsel
Nancy H. Badeer
Head of Insurance Products Law
Associate General
Counsel
285 Madison Avenue
New York, NY 10017
T: 980-949-3600
October 19, 2026
Board of Directors
Brighthouse Life Insurance Company
1209 Orange
Street
Wilmington, DE 19801
| |
|
Pre-Effective Amendment No. 1 to the Registration Statement on Form S-3 |
| |
|
Brighthouse Life Insurance Company |
| |
|
Brighthouse SmartGuard Plus® |
Ladies and Gentlemen:
I am Head of Insurance
Products Law and an Associate General Counsel in the Legal and Compliance
Department and provide legal counsel to the Brighthouse Life Insurance
Company. This opinion is furnished in
connection with the proposed offering of a certain flexible premium adjusted index-linked life insurance
policy (the
“Policy”) issued by Brighthouse Life Insurance Company (“Company”) under
Pre-Effective Amendment No. 1 to
Registration Statement on Form
S-3, File No. 333-297104, filed on or about October 19, 2026 (the “Registration
Statement”) and described therein, filed by the Company under the Securities Act of 1933, as amended.
I have made such examination of law and examined such records of the Company and other documents as in my
judgment are necessary or appropriate to render the opinion expressed below.
I am of the following opinions:
1. The Company is duly organized and exists under the laws of the State of Delaware and has been duly
authorized to do business and to issue life insurance policies by the Insurance Commissioner of the State of
Delaware.
2. The Policy covered by
the above Registration Statement, and all amendments relating thereto, when
delivered and when the first premium payment made by an owner all in
accordance with the prospectus (the
“Prospectus”) included in the Registration Statement and in compliance with the applicable local
law, will be a
legal and binding obligation of the Company in accordance with its terms. Owners of the Policy, as such, will not
be subject to any deductions and charges by the Company other than those described in the Policy and as
referred to in the Prospectus.
I hereby consent to
the use of this opinion letter, or a copy thereof, as an exhibit to the Registration Statement.
Sincerely,
/s/ Nancy H. Badeer
Nancy H. Badeer
Head of Insurance Products Law
Associate General
Counsel
Consent of Independent Registered Public Accounting Firm
CONSENT OF INDEPENDENT
REGISTERED PUBLIC ACCOUNTING FIRM
We consent to the incorporation by reference
in this Pre-Effective Amendment to Registration Statement File No. 333-297104 on Form S-3 of our report dated February 27, 2026, relating to the financial statements of Brighthouse
Life Insurance Company, appearing in the Annual Report on Form 10-K of Brighthouse Life Insurance Company for the
year ended December 31, 2025. We also consent to the reference to us under the heading “Independent Registered Public Accounting Firm” in the Prospectus, which is part of such Registration Statement.
/s/ DELOITTE & TOUCHE LLP
Charlotte, North Carolina
October 19, 2026
Powers of Attorney
Brighthouse Life Insurance Company
POWER OF ATTORNEY
Eric Steigerwalt
Chairman of the Board, President, Chief Executive Officer and a Director
KNOW ALL MEN BY THESE PRESENTS, that I, Eric Steigerwalt, Chairman of the Board, President and Chief Executive Officer and a Director of Brighthouse Life Insurance
Company, a Delaware company (the “Company”), do hereby constitute and appoint Michele H. Abate, Allie Lin, and Alexander Ulianov, as my
attorney-in-fact and agent, each of whom may act individually and none of whom is required to act jointly with any of the others, to sign and file on my behalf and to
execute and file any instrument or document required to be filed as part of or in connection with or in any way related to, the Registration Statements and any and all amendments thereto filed by the Company under the Securities Act of 1933 and/or
the Investment Company Act of 1940, pertaining to:
| • |
|
Brighthouse Fund UL for Variable Life Insurance (811-03927) |
File No. 002-88637 MarketLifeSM and
Invest
File No. 333-152219
MarketLifeSM
File No. 333-56952
Brighthouse Variable Survivorship Life II
File No. 333-69771 Brighthouse Variable
Survivorship Life
File No. 333-96515 and
333-96616 Brighthouse Variable Life Accumulator and Brighthouse Variable Life Accumulator - Series 2
File No. 333-96519 Brighthouse Variable Life
File No. 333-113109 Brighthouse Variable Life Accumulator - Series 3
File No. 333-152216 Portfolio Architect Life
File No. 333-152217 VintageLife
File No. 333-152219 MarketLife,
| • |
|
Brighthouse Fund UL III for Variable Life Insurance (811-09215)
|
File No. 333-71349 Corporate Owned VUL Series 1
File No. 333-94779 Corporate Owned VUL 2000 and Corporate Owned VUL III
File No. 333-105335 Corporate Select Policy
File No. 333-113533 Corporate Owned VUL IV,
| • |
|
Brighthouse Separate Account A (811-03365) |
File No. 333-200231 Series VA (offered between October 7, 2011 and May 1, 2016)
File No. 333-200232 Series S (offered between October 7, 2011 and May 1, 2016) and
Series S-L Share Option (offered between October 7, 2011 and May 1, 2016)
File No. 333-200233 Series VA-4 (offered between October 7, 2011 and May 1, 2016)
File No. 333-200234 Series O (offered between April 30, 2012 and July 19, 2015)
File No. 333-200236 Series L - 4 Year (offered on and after April 29, 2013)
File No. 333-200237 PrimElite IV
File No. 333-200238 Marquis Portfolios (offered on and after April 30, 2012)
File No. 333-200239 Brighthouse Growth and Income
File No. 333-200240 Group Flexible Payment Variable Annuity (Flexible Bonus/Retirement
Companion/Smart Choice)
File No. 333-200243 PrimElite III
File No. 333-200246 Brighthouse Simple SolutionsSM
File No. 333-200250 Marquis
Portfolios (offered between November 7, 2005 and April 30, 2012)
File
No. 333-200253 Series XC
File
No. 333-200256 Series VA (offered between March 22, 2001 and October 7, 2011)
File No. 333-200259 Series L and Series L - 4 Year (offered between November 22, 2004 and October 7, 2011)
File No. 333-200261 Series C (offered between September 4, 2001 and October 7,
2011)
File No. 333-200263 Series XTRA
File No. 333-200265 Series S and Series S-L Share
Option (offered between April 30, 2007 and October 7, 2011)
File No. 333-200268
Series L - 4 Year (offered between October 7, 2011 and April 28, 2013)
File
No. 333-200270 Group Annuity SF 101
File
No. 333-200272 Ultimate Annuity FSL 224
File
No. 333-200275 Foresight SF 137
File
No. 333-200277 SecurAnnuity (CLICO) 224/ SF 1700
File
No. 333-200278 Group VA SF 234 (Texas)
File
No. 333-200280 Sunshine SF 236 FL
File
No. 333-200281 Flexible Value SF 230
File No. 333-200282 Investors Choice
Annuity, Capital Strategist Annuity, Imprint Annuity and Strive Annuity
File
No. 333-200283 Protected Equity Portfolio (PEP)
File
No. 333-200284 Vintage L and Vintage XC
File
No. 333-200285 Series XTRA 6
File
No. 333-200286 Series VA - 4 (offered between May 1, 2011 and October 7, 2011)
File No. 333-200287 Series C (offered on and after October 7, 2011)
File No. 333-200288 Pioneer PRISM
File No. 333-200289 Pioneer PRISM L
File No. 333-200290 Pioneer PRISM XC
File No. 333-200323 Brighthouse Investment Portfolio ArchitectSM - Standard Version and Brighthouse Investment Portfolio ArchitectSM - C Share Option
File No. 333-203748 Series O (offered on and after July 20, 2015)
File No. 333-209053 Series VA (offered on and after May 2, 2016)
File No. 333-209054 Series VA- 4 (offered on and
after May 2, 2016)
File No. 333-209055 Series S (offered on and after May 2, 2016) and
Series S-L Share Option (offered on and after May 2, 2016)
File No. 333-209411 Brighthouse Prime Options,
| • |
|
Brighthouse Separate Account Eleven for Variable Annuities (811-21262) |
File Nos. 333-101778 and 333-152234 Pioneer AnnuiStar
Plus Annuity, Portfolio Architect Plus Annuity and Scudder Advocate Rewards Annuity
File
No. 333-152189 Universal Annuity
File
No. 333-152190 Universal Select Annuity
File
No. 333-152191 Universal Annuity Advantage
File Nos.
333-152192 and 333-152193 Brighthouse Retirement Account
File No. 333-152194 Gold Track and Gold Track Select
File Nos. 333-152197 and 333-152198 Brighthouse Access
Annuity and Brighthouse Access Select Annuity
File Nos. 333-152199 and 333-152200 Vintage Annuity
File Nos. 333-152201 and 333-152202 Index Annuity
File Nos. 333-152232 and 333-152233 Portfolio Architect Annuity, Portfolio Architect Select Annuity, Premier Advisers Annuity (Class I) and Premier Advisers Annuity (Class II)
File Nos. 333-152235 and 333-152236 Pioneer AnnuiStar
Annuity, Portfolio Architect II Annuity and Pioneer AnnuiStar Value Annuity
File Nos.
333-152237 and 333-152238 Premier Advisers II Annuity, Premier Advisers III (Series I) and Premier Advisers III Annuity (Series II)
File Nos. 333-152239 and 333-152240 Premier Advisers
AssetManager Annuity, Premier Advisers L Annuity (Series I) and Premier Advisers L Annuity (Series II)
File Nos. 333-152255 and 333-152265 Vintage XTRA Annuity, Portfolio Architect XTRA Annuity and Vintage XTRA Annuity (Series II)
File Nos. 333-152256 and 333-152292 Vintage 3 Annuity,
Portfolio Architect 3 Annuity, Portfolio Architect L Annuity, Vintage L Annuity and Pioneer AnnuiStar Flex Annuity
File Nos. 333-152258 and 333-152261 PrimElite Annuity
File Nos. 333-152259 and 333-152262 PrimElite II Annuity
File Nos. 333-152260 and 333-152266 Protected Equity Portfolio Annuity
File Nos. 333-152263 and 333-152269 Marquis Portfolios
File Nos. 333-152264 and 333-152270 Vintage Access,
Portfolio Architect Access, Scudder Advocate Advisor and Scudder Advocate Advisor - ST1 Annuity
File Nos. 333-152267 and 333-152268 Vintage II Annuity and Vintage II Annuity (Series II)
File No. 333-197658 Brighthouse Accumulation Annuity
File No. 333-208464 Brighthouse Premier Variable AnnuitySM,
| • |
|
Brighthouse Separate Account QPN for Variable Annuities |
File No. 333-156867 Unallocated Group Variable Annuity
File No. 333-156911 Brighthouse Retirement Perspectives,
| • |
|
Brighthouse Variable Annuity Account C (811-05200) |
File No. 333-200244 Class XC
File No. 333-200247 Class VA, Class AA and Class B
File No. 333-200249 Class L and Class L - 4 Year
File No. 333-200252 Class A
File No. 333-200255 COVA VA, Firstar Summit VA, Premier Advisor VA, Destiny Select VA and
Prevail VA
File No. 333-200258 COVA VA SPDA
File No. 333-200260 COVA Series A
File No. 333-200262 Navigator-Select/Custom-Select/Russell-Select
File No. 333-200264 Navigator-Select/Custom-Select/Russell-Select (CA)
File No. 333-200266 COVA VA and Premier Advisor (CA)
File No. 333-200267 COVA Series A (CA)
File No. 333-200269 Class C
File No. 333-200271 Class VA (CA), Class AA (CA), and Class B (CA)
File No. 333-200273 Class XC (CA)
File No. 333-200274 Class L (CA) and Class L - 4 Year (CA)
File No. 333-200276 Class A (CA)
File No. 333-200279 Class C (CA),
| • |
|
Brighthouse Variable Life Account A (811-21851) |
File No. 333-200241 Equity Advantage Variable Universal Life,
| • |
|
Brighthouse Variable Life Account One (811-07971) |
File No. 333-200242 Class VL
File No. 333-200245 Class VL (CA)
File No. 333-200248 Modified Single Premium Variable Life
File No. 333-200251 Custom Select and Russell Select Variable Life
File No. 333-200254 Modified Single Premium Variable Life (CA)
File No. 333-200257 Custom Select Variable Life,
| • |
|
Brighthouse Life Insurance Company (RILA MVA) |
File No. 333-282752 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay Plus® II Advisory Annuity
File No. 333-282871 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-283023 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-283024 Brighthouse
Shield® Level II 3-Year Annuity
File No. 333-290021 Fixed Account Annuity (Strategic Value Annuity)
File No. 333-290022 Gold Track and Registered Fixed Account Option and Gold Track Select
and Registered Fixed Account Option
File No. 333-290023 Brighthouse Retirement
Perspectives and Registered Fixed Account Option
File No. 333-290024 Unallocated Group
Variable Annuity and Registered Fixed Account Option
File No. 333-290025 Brighthouse
Retirement Account Annuity, Registered Fixed Account Option and Brighthouse Retirement Account Liquidity Benefit,
And pertaining to:
File No. 333-297104 Brighthouse SmartGuard Plus®
File No. 333-262390 Brighthouse
Shield® Level Pay PlusSM Annuity and Brighthouse Shield® Level Pay PlusSM Advisory Annuity
File
No. 333-226035 Brighthouse Shield® Level Select 6-Year Annuity v.3
File No. 333-233240 Brighthouse
Shield® Level 10 Advisory Annuity
File
No. 333-268427 Brighthouse Shield® Level Select Advisory Annuity
File No. 333-263492 Brighthouse
Shield® Level Select 6-Year Annuity
File No. 333-263495 Brighthouse
Shield® Level Select 3-Year Annuity
File No. 333-238213 Brighthouse
Shield® Level 10 Annuity
File
No. 333-208664 Brighthouse Shield Level Selector® Annuity
File No. 333-207091 Brighthouse Shield Level Selector® 3-Year Annuity
File No. 333-276468 Registered Fixed Account Option
File
No. 333-276469 Fixed Annuity (Strategic Value Annuity)
File No. 333-276470 Brighthouse Retirement Account Liquidity Benefit
File No. 333-276599 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-276762 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-276763 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay
Plus® II Advisory Annuity
File
No. 333-279302 Brighthouse Shield® Level II 3-Year Annuity
T-Mark Fixed Annuity
Target Maturity,
And new annuities and life
products such as:
Brighthouse Shield Annuity
Brighthouse Shield 3-Year Annuity
Brighthouse Shield 6-Year Annuity
Brighthouse Index-linked Life Insurance Policy,
and to have full power and authority to do or cause to be done in my name, place and stead each and every act and thing necessary or appropriate in order to effectuate
the same, as fully to all intents and purposes as I might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact or any of them, may do
or cause to be done by virtue hereof. This Power of Attorney does not revoke any prior powers of attorney.
IN WITNESS WHEREOF, I have hereunto set my hand this 6th
day of October 2026.
|
| /s/ Eric Steigerwalt |
Eric Steigerwalt |
Brighthouse Life Insurance Company
POWER OF ATTORNEY
Myles Lambert
Director and Vice President
KNOW ALL MEN BY THESE PRESENTS, that I,
Myles Lambert, a Director and Vice President of Brighthouse Life Insurance Company, a Delaware company (the “Company”), do hereby constitute and appoint Michele H. Abate, Allie Lin, and Alexander Ulianov, as my attorney-in-fact and agent, each of whom may act individually and none of whom is required to act jointly with any of the others, to sign and file on my behalf and to execute
and file any instrument or document required to be filed as part of or in connection with or in any way related to, the Registration Statements and any and all amendments thereto filed by the Company under the Securities Act of 1933 and/or the
Investment Company Act of 1940, pertaining to:
| • |
|
Brighthouse Fund UL for Variable Life Insurance (811-03927) |
File No. 002-88637 MarketLifeSM and
Invest
File No. 333-152219
MarketLifeSM
File No. 333-56952
Brighthouse Variable Survivorship Life II
File No. 333-69771 Brighthouse Variable
Survivorship Life
File No. 333-96515 and
333-96616 Brighthouse Variable Life Accumulator and Brighthouse Variable Life Accumulator - Series 2
File No. 333-96519 Brighthouse Variable Life
File No. 333-113109 Brighthouse Variable Life Accumulator - Series 3
File No. 333-152216 Portfolio Architect Life
File No. 333-152217 VintageLife
File No. 333-152219 MarketLife,
| • |
|
Brighthouse Fund UL III for Variable Life Insurance (811-09215)
|
File No. 333-71349 Corporate Owned VUL Series 1
File No. 333-94779 Corporate Owned VUL 2000 and Corporate Owned VUL III
File No. 333-105335 Corporate Select Policy
File No. 333-113533 Corporate Owned VUL IV,
| • |
|
Brighthouse Separate Account A (811-03365) |
File No. 333-200231 Series VA (offered between October 7, 2011 and May 1, 2016)
File No. 333-200232 Series S (offered between October 7, 2011 and May 1, 2016) and
Series S-L Share Option (offered between October 7, 2011 and May 1, 2016)
File No. 333-200233 Series VA-4 (offered between October 7, 2011 and May 1, 2016)
File No. 333-200234 Series O (offered between April 30, 2012 and July 19, 2015)
File No. 333-200236 Series L - 4 Year (offered on and after April 29, 2013)
File No. 333-200237 PrimElite IV
File No. 333-200238 Marquis Portfolios (offered on and after April 30, 2012)
File No. 333-200239 Brighthouse Growth and Income
File No. 333-200240 Group Flexible Payment Variable Annuity (Flexible Bonus/Retirement
Companion/Smart Choice)
File No. 333-200243 PrimElite III
File No. 333-200246 Brighthouse Simple SolutionsSM
File No. 333-200250 Marquis
Portfolios (offered between November 7, 2005 and April 30, 2012)
File
No. 333-200253 Series XC
File
No. 333-200256 Series VA (offered between March 22, 2001 and October 7, 2011)
File No. 333-200259 Series L and Series L - 4 Year (offered between November 22, 2004 and October 7, 2011)
File No. 333-200261 Series C (offered between September 4, 2001 and October 7,
2011)
File No. 333-200263 Series XTRA
File No. 333-200265 Series S and Series S-L Share
Option (offered between April 30, 2007 and October 7, 2011)
File No. 333-200268
Series L - 4 Year (offered between October 7, 2011 and April 28, 2013)
File
No. 333-200270 Group Annuity SF 101
File
No. 333-200272 Ultimate Annuity FSL 224
File
No. 333-200275 Foresight SF 137
File
No. 333-200277 SecurAnnuity (CLICO) 224/ SF 1700
File
No. 333-200278 Group VA SF 234 (Texas)
File
No. 333-200280 Sunshine SF 236 FL
File
No. 333-200281 Flexible Value SF 230
File No. 333-200282 Investors Choice
Annuity, Capital Strategist Annuity, Imprint Annuity and Strive Annuity
File
No. 333-200283 Protected Equity Portfolio (PEP)
File
No. 333-200284 Vintage L and Vintage XC
File
No. 333-200285 Series XTRA 6
File
No. 333-200286 Series VA - 4 (offered between May 1, 2011 and October 7, 2011)
File No. 333-200287 Series C (offered on and after October 7, 2011)
File No. 333-200288 Pioneer PRISM
File No. 333-200289 Pioneer PRISM L
File No. 333-200290 Pioneer PRISM XC
File No. 333-200323 Brighthouse Investment Portfolio ArchitectSM - Standard Version and Brighthouse Investment Portfolio ArchitectSM - C Share Option
File No. 333-203748 Series O (offered on and after July 20, 2015)
File No. 333-209053 Series VA (offered on and after May 2, 2016)
File No. 333-209054 Series VA- 4 (offered on and
after May 2, 2016)
File No. 333-209055 Series S (offered on and after May 2, 2016) and
Series S-L Share Option (offered on and after May 2, 2016)
File No. 333-209411 Brighthouse Prime Options,
| • |
|
Brighthouse Separate Account Eleven for Variable Annuities (811-21262) |
File Nos. 333-101778 and 333-152234 Pioneer AnnuiStar
Plus Annuity, Portfolio Architect Plus Annuity and Scudder Advocate Rewards Annuity
File
No. 333-152189 Universal Annuity
File
No. 333-152190 Universal Select Annuity
File
No. 333-152191 Universal Annuity Advantage
File Nos.
333-152192 and 333-152193 Brighthouse Retirement Account
File No. 333-152194 Gold Track and Gold Track Select
File Nos. 333-152197 and 333-152198 Brighthouse Access
Annuity and Brighthouse Access Select Annuity
File Nos. 333-152199 and 333-152200 Vintage Annuity
File Nos. 333-152201 and 333-152202 Index Annuity
File Nos. 333-152232 and 333-152233 Portfolio Architect Annuity, Portfolio Architect Select Annuity, Premier Advisers Annuity (Class I) and Premier Advisers Annuity (Class II)
File Nos. 333-152235 and 333-152236 Pioneer AnnuiStar
Annuity, Portfolio Architect II Annuity and Pioneer AnnuiStar Value Annuity
File Nos.
333-152237 and 333-152238 Premier Advisers II Annuity, Premier Advisers III (Series I)
and Premier Advisers III Annuity (Series II)
File Nos. 333-152239 and 333-152240 Premier Advisers
AssetManager Annuity, Premier Advisers L Annuity (Series I) and Premier Advisers L Annuity (Series II)
File Nos. 333-152255 and 333-152265 Vintage XTRA Annuity, Portfolio Architect XTRA Annuity and Vintage XTRA Annuity (Series II)
File Nos. 333-152256 and 333-152292 Vintage 3 Annuity,
Portfolio Architect 3 Annuity, Portfolio Architect L Annuity, Vintage L Annuity and Pioneer AnnuiStar Flex Annuity
File Nos. 333-152258 and 333-152261 PrimElite Annuity
File Nos. 333-152259 and 333-152262 PrimElite II Annuity
File Nos. 333-152260 and 333-152266 Protected Equity Portfolio Annuity
File Nos. 333-152263 and 333-152269 Marquis Portfolios
File Nos. 333-152264 and 333-152270 Vintage Access,
Portfolio Architect Access, Scudder Advocate Advisor and Scudder Advocate Advisor - ST1 Annuity
File Nos. 333-152267 and 333-152268 Vintage II Annuity and Vintage II Annuity (Series II)
File No. 333-197658 Brighthouse Accumulation Annuity
File No. 333-208464 Brighthouse Premier Variable AnnuitySM,
| • |
|
Brighthouse Separate Account QPN for Variable Annuities |
File No. 333-156867 Unallocated Group Variable Annuity
File No. 333-156911 Brighthouse Retirement Perspectives,
| • |
|
Brighthouse Variable Annuity Account C (811-05200) |
File No. 333-200244 Class XC
File No. 333-200247 Class VA, Class AA and Class B
File No. 333-200249 Class L and Class L - 4 Year
File No. 333-200252 Class A
File No. 333-200255 COVA VA, Firstar Summit VA, Premier Advisor VA, Destiny Select VA and
Prevail VA
File No. 333-200258 COVA VA SPDA
File No. 333-200260 COVA Series A
File No. 333-200262 Navigator-Select/Custom-Select/Russell-Select
File No. 333-200264 Navigator-Select/Custom-Select/Russell-Select (CA)
File No. 333-200266 COVA VA and Premier Advisor (CA)
File No. 333-200267 COVA Series A (CA)
File No. 333-200269 Class C
File No. 333-200271 Class VA (CA), Class AA (CA), and Class B (CA)
File No. 333-200273 Class XC (CA)
File No. 333-200274 Class L (CA) and Class L - 4 Year (CA)
File No. 333-200276 Class A (CA)
File No. 333-200279 Class C (CA),
| • |
|
Brighthouse Variable Life Account A (811-21851) |
File No. 333-200241 Equity Advantage Variable Universal Life,
| • |
|
Brighthouse Variable Life Account One (811-07971) |
File No. 333-200242 Class VL
File No. 333-200245 Class VL (CA)
File No. 333-200248 Modified Single Premium Variable Life
File No. 333-200251 Custom Select and Russell Select Variable Life
File No. 333-200254 Modified Single Premium Variable Life (CA)
File No. 333-200257 Custom Select Variable Life,
| • |
|
Brighthouse Life Insurance Company (RILA MVA) |
File No. 333-282752 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay Plus® II Advisory Annuity
File No. 333-282871 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-283023 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-283024 Brighthouse
Shield® Level II 3-Year Annuity
File No. 333-290021 Fixed Account Annuity (Strategic Value Annuity)
File No. 333-290022 Gold Track and Registered Fixed Account Option and Gold Track Select
and Registered Fixed Account Option
File No. 333-290023 Brighthouse Retirement
Perspectives and Registered Fixed Account Option
File No. 333-290024 Unallocated Group
Variable Annuity and Registered Fixed Account Option
File No. 333-290025 Brighthouse
Retirement Account Annuity, Registered Fixed Account Option and Brighthouse Retirement Account Liquidity Benefit,
And pertaining to:
File No. 333-297104 Brighthouse SmartGuard Plus®
File No. 333-262390 Brighthouse
Shield® Level Pay PlusSM Annuity and Brighthouse Shield® Level Pay PlusSM Advisory Annuity
File
No. 333-226035 Brighthouse Shield® Level Select 6-Year Annuity v.3
File No. 333-233240 Brighthouse
Shield® Level 10 Advisory Annuity
File
No. 333-268427 Brighthouse Shield® Level Select Advisory Annuity
File No. 333-263492 Brighthouse
Shield® Level Select 6-Year Annuity
File No. 333-263495 Brighthouse
Shield® Level Select 3-Year Annuity
File No. 333-238213 Brighthouse
Shield® Level 10 Annuity
File
No. 333-208664 Brighthouse Shield Level Selector® Annuity
File No. 333-207091 Brighthouse Shield Level Selector® 3-Year Annuity
File No. 333-276468 Registered Fixed Account Option
File
No. 333-276469 Fixed Annuity (Strategic Value Annuity)
File No. 333-276470 Brighthouse Retirement Account Liquidity Benefit
File No. 333-276599 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-276762 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-276763 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay
Plus® II Advisory Annuity
File
No. 333-279302 Brighthouse Shield® Level II 3-Year Annuity
T-Mark Fixed Annuity
Target Maturity,
And new annuities and life
products such as:
Brighthouse Shield Annuity
Brighthouse Shield 3-Year Annuity
Brighthouse Shield 6-Year Annuity
Brighthouse Index-linked Life Insurance Policy,
and to have full power and authority to do or cause to be done in my name, place and stead each and every act and thing necessary or appropriate in order to effectuate
the same, as fully to all intents and purposes as I might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact or any of them, may do
or cause to be done by virtue hereof. This Power of Attorney does not revoke any prior powers of attorney.
IN WITNESS WHEREOF, I have hereunto set my hand this 6th
day of October 2026.
Myles Lambert
Brighthouse Life Insurance Company
POWER OF ATTORNEY
David A. Rosenbaum
Director and Vice President
KNOW ALL MEN BY THESE PRESENTS, that I,
David A. Rosenbaum, a Director and Vice President of Brighthouse Life Insurance Company, a Delaware company (the “Company”), do hereby constitute and appoint Michele H. Abate, Allie Lin, and Alexander Ulianov, as my attorney-in-fact and agent, each of whom may act individually and none of whom is required to act jointly with any of the others, to sign and file on my behalf and to execute
and file any instrument or document required to be filed as part of or in connection with or in any way related to, the Registration Statements and any and all amendments thereto filed by the Company under the Securities Act of 1933 and/or the
Investment Company Act of 1940, pertaining to:
| • |
|
Brighthouse Fund UL for Variable Life Insurance (811-03927) |
File No. 002-88637 MarketLifeSM and
Invest
File No. 333-152219
MarketLifeSM
File No. 333-56952
Brighthouse Variable Survivorship Life II
File No. 333-69771 Brighthouse Variable
Survivorship Life
File No. 333-96515 and
333-96616 Brighthouse Variable Life Accumulator and Brighthouse Variable Life Accumulator - Series 2
File No. 333-96519 Brighthouse Variable Life
File No. 333-113109 Brighthouse Variable Life Accumulator - Series 3
File No. 333-152216 Portfolio Architect Life
File No. 333-152217 VintageLife
File No. 333-152219 MarketLife,
| • |
|
Brighthouse Fund UL III for Variable Life Insurance (811-09215)
|
File No. 333-71349 Corporate Owned VUL Series 1
File No. 333-94779 Corporate Owned VUL 2000 and Corporate Owned VUL III
File No. 333-105335 Corporate Select Policy
File No. 333-113533 Corporate Owned VUL IV,
| • |
|
Brighthouse Separate Account A (811-03365) |
File No. 333-200231 Series VA (offered between October 7, 2011 and May 1, 2016)
File No. 333-200232 Series S (offered between October 7, 2011 and May 1, 2016) and
Series S-L Share Option (offered between October 7, 2011 and May 1, 2016)
File No. 333-200233 Series VA-4 (offered between October 7, 2011 and May 1, 2016)
File No. 333-200234 Series O (offered between April 30, 2012 and July 19, 2015)
File No. 333-200236 Series L - 4 Year (offered on and after April 29, 2013)
File No. 333-200237 PrimElite IV
File No. 333-200238 Marquis Portfolios (offered on and after April 30, 2012)
File No. 333-200239 Brighthouse Growth and Income
File No. 333-200240 Group Flexible Payment Variable Annuity (Flexible Bonus/Retirement
Companion/Smart Choice)
File No. 333-200243 PrimElite III
File No. 333-200246 Brighthouse Simple SolutionsSM
File No. 333-200250 Marquis
Portfolios (offered between November 7, 2005 and April 30, 2012)
File
No. 333-200253 Series XC
File
No. 333-200256 Series VA (offered between March 22, 2001 and October 7, 2011)
File No. 333-200259 Series L and Series L - 4 Year (offered between November 22, 2004 and October 7, 2011)
File No. 333-200261 Series C (offered between September 4, 2001 and October 7,
2011)
File No. 333-200263 Series XTRA
File No. 333-200265 Series S and Series S-L Share
Option (offered between April 30, 2007 and October 7, 2011)
File No. 333-200268
Series L - 4 Year (offered between October 7, 2011 and April 28, 2013)
File
No. 333-200270 Group Annuity SF 101
File
No. 333-200272 Ultimate Annuity FSL 224
File
No. 333-200275 Foresight SF 137
File
No. 333-200277 SecurAnnuity (CLICO) 224/ SF 1700
File
No. 333-200278 Group VA SF 234 (Texas)
File
No. 333-200280 Sunshine SF 236 FL
File
No. 333-200281 Flexible Value SF 230
File No. 333-200282 Investors Choice
Annuity, Capital Strategist Annuity, Imprint Annuity and Strive Annuity
File
No. 333-200283 Protected Equity Portfolio (PEP)
File
No. 333-200284 Vintage L and Vintage XC
File
No. 333-200285 Series XTRA 6
File
No. 333-200286 Series VA - 4 (offered between May 1, 2011 and October 7, 2011)
File No. 333-200287 Series C (offered on and after October 7, 2011)
File No. 333-200288 Pioneer PRISM
File No. 333-200289 Pioneer PRISM L
File No. 333-200290 Pioneer PRISM XC
File No. 333-200323 Brighthouse Investment Portfolio ArchitectSM - Standard Version and Brighthouse Investment Portfolio ArchitectSM - C Share Option
File No. 333-203748 Series O (offered on and after July 20, 2015)
File No. 333-209053 Series VA (offered on and after May 2, 2016)
File No. 333-209054 Series VA- 4 (offered on and
after May 2, 2016)
File No. 333-209055 Series S (offered on and after May 2, 2016) and
Series S-L Share Option (offered on and after May 2, 2016)
File No. 333-209411 Brighthouse Prime Options,
| • |
|
Brighthouse Separate Account Eleven for Variable Annuities (811-21262) |
File Nos. 333-101778 and 333-152234 Pioneer AnnuiStar
Plus Annuity, Portfolio Architect Plus Annuity and Scudder Advocate Rewards Annuity
File
No. 333-152189 Universal Annuity
File
No. 333-152190 Universal Select Annuity
File
No. 333-152191 Universal Annuity Advantage
File Nos.
333-152192 and 333-152193 Brighthouse Retirement Account
File No. 333-152194 Gold Track and Gold Track Select
File Nos. 333-152197 and 333-152198 Brighthouse Access
Annuity and Brighthouse Access Select Annuity
File Nos. 333-152199 and 333-152200 Vintage Annuity
File Nos. 333-152201 and 333-152202 Index Annuity
File Nos. 333-152232 and 333-152233 Portfolio Architect Annuity, Portfolio Architect Select Annuity, Premier Advisers Annuity (Class I) and Premier Advisers Annuity (Class II)
File Nos. 333-152235 and 333-152236 Pioneer AnnuiStar
Annuity, Portfolio Architect II Annuity and Pioneer AnnuiStar Value Annuity
File Nos.
333-152237 and 333-152238 Premier Advisers II Annuity, Premier Advisers III (Series I) and Premier Advisers III Annuity (Series II)
File Nos. 333-152239 and 333-152240 Premier Advisers
AssetManager Annuity, Premier Advisers L Annuity (Series I) and Premier Advisers L Annuity (Series II)
File Nos. 333-152255 and 333-152265 Vintage XTRA Annuity, Portfolio Architect XTRA Annuity and Vintage XTRA Annuity (Series II)
File Nos. 333-152256 and 333-152292 Vintage 3 Annuity,
Portfolio Architect 3 Annuity, Portfolio Architect L Annuity, Vintage L Annuity and Pioneer AnnuiStar Flex Annuity
File Nos. 333-152258 and 333-152261 PrimElite Annuity
File Nos. 333-152259 and 333-152262 PrimElite II Annuity
File Nos. 333-152260 and 333-152266 Protected Equity Portfolio Annuity
File Nos. 333-152263 and 333-152269 Marquis Portfolios
File Nos. 333-152264 and 333-152270 Vintage Access,
Portfolio Architect Access, Scudder Advocate Advisor and Scudder Advocate Advisor - ST1 Annuity
File Nos. 333-152267 and 333-152268 Vintage II Annuity and Vintage II Annuity (Series II)
File No. 333-197658 Brighthouse Accumulation Annuity
File No. 333-208464 Brighthouse Premier Variable AnnuitySM,
| • |
|
Brighthouse Separate Account QPN for Variable Annuities |
File No. 333-156867 Unallocated Group Variable Annuity
File No. 333-156911 Brighthouse Retirement Perspectives,
| • |
|
Brighthouse Variable Annuity Account C (811-05200) |
File No. 333-200244 Class XC
File No. 333-200247 Class VA, Class AA and Class B
File No. 333-200249 Class L and Class L - 4 Year
File No. 333-200252 Class A
File No. 333-200255 COVA VA, Firstar Summit VA, Premier Advisor VA, Destiny Select VA and
Prevail VA
File No. 333-200258 COVA VA SPDA
File No. 333-200260 COVA Series A
File No. 333-200262 Navigator-Select/Custom-Select/Russell-Select
File No. 333-200264 Navigator-Select/Custom-Select/Russell-Select (CA)
File No. 333-200266 COVA VA and Premier Advisor (CA)
File No. 333-200267 COVA Series A (CA)
File No. 333-200269 Class C
File No. 333-200271 Class VA (CA), Class AA (CA), and Class B (CA)
File No. 333-200273 Class XC (CA)
File No. 333-200274 Class L (CA) and Class L - 4 Year (CA)
File No. 333-200276 Class A (CA)
File No. 333-200279 Class C (CA),
| • |
|
Brighthouse Variable Life Account A (811-21851) |
File No. 333-200241 Equity Advantage Variable Universal Life,
| • |
|
Brighthouse Variable Life Account One (811-07971) |
File No. 333-200242 Class VL
File No. 333-200245 Class VL (CA)
File No. 333-200248 Modified Single Premium Variable Life
File No. 333-200251 Custom Select and Russell Select Variable Life
File No. 333-200254 Modified Single Premium Variable Life (CA)
File No. 333-200257 Custom Select Variable Life,
| • |
|
Brighthouse Life Insurance Company (RILA MVA) |
File No. 333-282752 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay Plus® II Advisory Annuity
File No. 333-282871 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-283023 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-283024 Brighthouse
Shield® Level II 3-Year Annuity
File No. 333-290021 Fixed Account Annuity (Strategic Value Annuity)
File No. 333-290022 Gold Track and Registered Fixed Account Option and Gold Track Select
and Registered Fixed Account Option
File No. 333-290023 Brighthouse Retirement
Perspectives and Registered Fixed Account Option
File No. 333-290024 Unallocated Group
Variable Annuity and Registered Fixed Account Option
File No. 333-290025 Brighthouse
Retirement Account Annuity, Registered Fixed Account Option and Brighthouse Retirement Account Liquidity Benefit,
And pertaining to:
File No. 333-297104 Brighthouse SmartGuard Plus®
File No. 333-262390 Brighthouse
Shield® Level Pay PlusSM Annuity and Brighthouse Shield® Level Pay PlusSM Advisory Annuity
File
No. 333-226035 Brighthouse Shield® Level Select 6-Year Annuity v.3
File No. 333-233240 Brighthouse
Shield® Level 10 Advisory Annuity
File
No. 333-268427 Brighthouse Shield® Level Select Advisory Annuity
File No. 333-263492 Brighthouse
Shield® Level Select 6-Year Annuity
File No. 333-263495 Brighthouse
Shield® Level Select 3-Year Annuity
File No. 333-238213 Brighthouse
Shield® Level 10 Annuity
File
No. 333-208664 Brighthouse Shield Level Selector® Annuity
File No. 333-207091 Brighthouse Shield Level Selector® 3-Year Annuity
File No. 333-276468 Registered Fixed Account Option
File
No. 333-276469 Fixed Annuity (Strategic Value Annuity)
File No. 333-276470 Brighthouse Retirement Account Liquidity Benefit
File No. 333-276599 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-276762 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-276763 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay
Plus® II Advisory Annuity
File
No. 333-279302 Brighthouse Shield® Level II 3-Year Annuity
T-Mark Fixed Annuity
Target Maturity,
And new annuities and life
products such as:
Brighthouse Shield Annuity
Brighthouse Shield 3-Year Annuity
Brighthouse Shield 6-Year Annuity
Brighthouse Index-linked Life Insurance Policy,
and to have full power and authority to do or cause to be done in my name, place and stead each and every act and thing necessary or appropriate in order to effectuate
the same, as fully to all intents and purposes as I might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact or any of them, may do
or cause to be done by virtue hereof. This Power of Attorney does not revoke any prior powers of attorney.
IN WITNESS WHEREOF, I have hereunto set my hand this 6th
day of October 2026.
David A. Rosenbaum
Brighthouse Life Insurance Company
POWER OF ATTORNEY
Jonathan Rosenthal
Director, Vice President and Chief Investment Officer
KNOW ALL MEN
BY THESE PRESENTS, that I, Jonathan Rosenthal, a Director, Vice President and Chief Investment Officer of Brighthouse Life Insurance Company, a Delaware company (the “Company”), do hereby constitute and appoint Michele H. Abate, Allie
Lin, and Alexander Ulianov, as my attorney-in-fact and agent, each of whom may act individually and none of whom is required to act jointly with any of the others, to
sign and file on my behalf and to execute and file any instrument or document required to be filed as part of or in connection with or in any way related to, the Registration Statements and any and all amendments thereto filed by the Company under
the Securities Act of 1933 and/or the Investment Company Act of 1940, pertaining to:
| • |
|
Brighthouse Fund UL for Variable Life Insurance (811-03927) |
File No. 002-88637 MarketLifeSM and
Invest
File No. 333-152219
MarketLifeSM
File No. 333-56952
Brighthouse Variable Survivorship Life II
File No. 333-69771 Brighthouse Variable
Survivorship Life
File No. 333-96515 and
333-96616 Brighthouse Variable Life Accumulator and Brighthouse Variable Life Accumulator - Series 2
File No. 333-96519 Brighthouse Variable Life
File No. 333-113109 Brighthouse Variable Life Accumulator - Series 3
File No. 333-152216 Portfolio Architect Life
File No. 333-152217 VintageLife
File No. 333-152219 MarketLife,
| • |
|
Brighthouse Fund UL III for Variable Life Insurance (811-09215)
|
File No. 333-71349 Corporate Owned VUL Series 1
File No. 333-94779 Corporate Owned VUL 2000 and Corporate Owned VUL III
File No. 333-105335 Corporate Select Policy
File No. 333-113533 Corporate Owned VUL IV,
| • |
|
Brighthouse Separate Account A (811-03365) |
File No. 333-200231 Series VA (offered between October 7, 2011 and May 1, 2016)
File No. 333-200232 Series S (offered between October 7, 2011 and May 1, 2016) and
Series S-L Share Option (offered between October 7, 2011 and May 1, 2016)
File No. 333-200233 Series VA-4 (offered between October 7, 2011 and May 1, 2016)
File No. 333-200234 Series O (offered between April 30, 2012 and July 19, 2015)
File No. 333-200236 Series L - 4 Year (offered on and after April 29, 2013)
File No. 333-200237 PrimElite IV
File No. 333-200238 Marquis Portfolios (offered on and after April 30, 2012)
File No. 333-200239 Brighthouse Growth and Income
File No. 333-200240 Group Flexible Payment Variable Annuity (Flexible Bonus/Retirement
Companion/Smart Choice)
File No. 333-200243 PrimElite III
File No. 333-200246 Brighthouse Simple SolutionsSM
File No. 333-200250 Marquis
Portfolios (offered between November 7, 2005 and April 30, 2012)
File
No. 333-200253 Series XC
File
No. 333-200256 Series VA (offered between March 22, 2001 and October 7, 2011)
File No. 333-200259 Series L and Series L - 4 Year (offered between November 22, 2004 and October 7, 2011)
File No. 333-200261 Series C (offered between September 4, 2001 and October 7,
2011)
File No. 333-200263 Series XTRA
File No. 333-200265 Series S and Series S-L Share
Option (offered between April 30, 2007 and October 7, 2011)
File No. 333-200268
Series L - 4 Year (offered between October 7, 2011 and April 28, 2013)
File
No. 333-200270 Group Annuity SF 101
File
No. 333-200272 Ultimate Annuity FSL 224
File
No. 333-200275 Foresight SF 137
File
No. 333-200277 SecurAnnuity (CLICO) 224/ SF 1700
File
No. 333-200278 Group VA SF 234 (Texas)
File
No. 333-200280 Sunshine SF 236 FL
File
No. 333-200281 Flexible Value SF 230
File No. 333-200282 Investors Choice
Annuity, Capital Strategist Annuity, Imprint Annuity and Strive Annuity
File
No. 333-200283 Protected Equity Portfolio (PEP)
File
No. 333-200284 Vintage L and Vintage XC
File
No. 333-200285 Series XTRA 6
File
No. 333-200286 Series VA - 4 (offered between May 1, 2011 and October 7, 2011)
File No. 333-200287 Series C (offered on and after October 7, 2011)
File No. 333-200288 Pioneer PRISM
File No. 333-200289 Pioneer PRISM L
File No. 333-200290 Pioneer PRISM XC
File No. 333-200323 Brighthouse Investment Portfolio ArchitectSM - Standard Version and Brighthouse Investment Portfolio ArchitectSM - C Share Option
File No. 333-203748 Series O (offered on and after July 20, 2015)
File No. 333-209053 Series VA (offered on and after May 2, 2016)
File No. 333-209054 Series VA- 4 (offered on and
after May 2, 2016)
File
No. 333-209055 Series S (offered on and after May 2, 2016) and Series S-L Share Option (offered on and after May 2, 2016)
File No. 333-209411 Brighthouse Prime Options,
| • |
|
Brighthouse Separate Account Eleven for Variable Annuities (811-21262) |
File Nos. 333-101778 and 333-152234 Pioneer AnnuiStar
Plus Annuity, Portfolio Architect Plus Annuity and Scudder Advocate Rewards Annuity
File
No. 333-152189 Universal Annuity
File
No. 333-152190 Universal Select Annuity
File
No. 333-152191 Universal Annuity Advantage
File Nos.
333-152192 and 333-152193 Brighthouse Retirement Account
File No. 333-152194 Gold Track and Gold Track Select
File Nos. 333-152197 and 333-152198 Brighthouse Access
Annuity and Brighthouse Access Select Annuity
File Nos. 333-152199 and 333-152200 Vintage Annuity
File Nos. 333-152201 and 333-152202 Index Annuity
File Nos. 333-152232 and 333-152233 Portfolio Architect Annuity, Portfolio Architect Select Annuity, Premier Advisers Annuity (Class I) and Premier Advisers Annuity (Class II)
File Nos. 333-152235 and 333-152236 Pioneer AnnuiStar
Annuity, Portfolio Architect II Annuity and Pioneer AnnuiStar Value Annuity
File Nos.
333-152237 and 333-152238 Premier Advisers II Annuity, Premier Advisers III (Series I) and Premier Advisers III Annuity (Series II)
File Nos. 333-152239 and 333-152240 Premier Advisers
AssetManager Annuity, Premier Advisers L Annuity (Series I) and Premier Advisers L Annuity (Series II)
File Nos. 333-152255 and 333-152265 Vintage XTRA Annuity, Portfolio Architect XTRA Annuity and Vintage XTRA Annuity (Series II)
File Nos. 333-152256 and 333-152292 Vintage 3 Annuity,
Portfolio Architect 3 Annuity, Portfolio Architect L Annuity, Vintage L Annuity and Pioneer AnnuiStar Flex Annuity
File Nos. 333-152258 and 333-152261 PrimElite Annuity
File Nos. 333-152259 and 333-152262 PrimElite II Annuity
File Nos. 333-152260 and 333-152266 Protected Equity
Portfolio Annuity
File Nos. 333-152263 and
333-152269 Marquis Portfolios
File Nos. 333-152264
and 333-152270 Vintage Access, Portfolio Architect Access, Scudder Advocate Advisor and Scudder Advocate Advisor - ST1 Annuity
File Nos. 333-152267 and 333-152268 Vintage II Annuity
and Vintage II Annuity (Series II)
File No. 333-197658 Brighthouse Accumulation
Annuity
File No. 333-208464 Brighthouse Premier Variable AnnuitySM,
| • |
|
Brighthouse Separate Account QPN for Variable Annuities |
File No. 333-156867 Unallocated Group Variable Annuity
File No. 333-156911 Brighthouse Retirement Perspectives,
| • |
|
Brighthouse Variable Annuity Account C (811-05200) |
File No. 333-200244 Class XC
File No. 333-200247 Class VA, Class AA and Class B
File No. 333-200249 Class L and Class L - 4 Year
File No. 333-200252 Class A
File No. 333-200255 COVA VA, Firstar Summit VA, Premier Advisor VA, Destiny Select VA and Prevail VA
File No. 333-200258 COVA VA SPDA
File No. 333-200260 COVA Series A
File No. 333-200262 Navigator-Select/Custom-Select/Russell-Select
File No. 333-200264 Navigator-Select/Custom-Select/Russell-Select (CA)
File No. 333-200266 COVA VA and Premier Advisor (CA)
File No. 333-200267 COVA Series A (CA)
File No. 333-200269 Class C
File No. 333-200271 Class VA (CA), Class AA (CA), and Class B (CA)
File No. 333-200273 Class XC (CA)
File No. 333-200274 Class L (CA) and Class L - 4 Year (CA)
File No. 333-200276 Class A (CA)
File No. 333-200279 Class C (CA),
| • |
|
Brighthouse Variable Life Account A (811-21851) |
File No. 333-200241 Equity Advantage Variable Universal Life,
| • |
|
Brighthouse Variable Life Account One (811-07971) |
File No. 333-200242 Class VL
File No. 333-200245 Class VL (CA)
File No. 333-200248 Modified Single Premium Variable Life
File No. 333-200251 Custom Select and Russell Select Variable Life
File No. 333-200254
Modified Single Premium Variable Life (CA)
File No. 333-200257 Custom Select Variable
Life,
| • |
|
Brighthouse Life Insurance Company (RILA MVA) |
File No. 333-282752 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay Plus® II Advisory Annuity
File No. 333-282871 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-283023 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-283024 Brighthouse
Shield® Level II 3-Year Annuity
File No. 333-290021 Fixed Account Annuity (Strategic Value Annuity)
File No. 333-290022 Gold Track and Registered Fixed Account Option and Gold Track Select
and Registered Fixed Account Option
File No. 333-290023 Brighthouse Retirement
Perspectives and Registered Fixed Account Option
File No. 333-290024 Unallocated Group
Variable Annuity and Registered Fixed Account Option
File No. 333-290025 Brighthouse
Retirement Account Annuity, Registered Fixed Account Option and Brighthouse Retirement Account Liquidity Benefit,
And pertaining to:
File No. 333-297104 Brighthouse SmartGuard Plus®
File No. 333-262390 Brighthouse
Shield® Level Pay PlusSM Annuity and Brighthouse Shield® Level Pay PlusSM Advisory Annuity
File
No. 333-226035 Brighthouse Shield® Level Select 6-Year Annuity v.3
File No. 333-233240 Brighthouse
Shield® Level 10 Advisory Annuity
File No. 333-268427 Brighthouse
Shield® Level Select Advisory Annuity
File No. 333-263492 Brighthouse
Shield® Level Select 6-Year Annuity
File No. 333-263495 Brighthouse
Shield® Level Select 3-Year Annuity
File No. 333-238213 Brighthouse
Shield® Level 10 Annuity
File
No. 333-208664 Brighthouse Shield Level Selector® Annuity
File No. 333-207091 Brighthouse Shield Level Selector® 3-Year Annuity
File No. 333-276468 Registered Fixed Account Option
File
No. 333-276469 Fixed Annuity (Strategic Value Annuity)
File No. 333-276470 Brighthouse Retirement Account Liquidity Benefit
File No. 333-276599 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-276762 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-276763 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay
Plus® II Advisory Annuity
File
No. 333-279302 Brighthouse Shield® Level II 3-Year Annuity
T-Mark Fixed Annuity
Target Maturity,
And new annuities and life
products such as:
Brighthouse Shield Annuity
Brighthouse Shield 3-Year Annuity
Brighthouse Shield 6-Year Annuity
Brighthouse Index-linked Life Insurance Policy,
and to have full
power and authority to do or cause to be done in my name, place and stead each and every act and thing necessary or appropriate in order to effectuate the same, as fully to all intents and purposes as I might or could do in person, hereby ratifying
and confirming all that said attorneys-in-fact or any of them, may do or cause to be done by virtue hereof. This Power of Attorney does not revoke any prior powers of
attorney.
IN WITNESS WHEREOF, I have hereunto set my hand this 6th day of October 2026.
/s/ Jonathan Rosenthal
Jonathan
Rosenthal
Brighthouse Life Insurance Company
POWER OF ATTORNEY
Edward A. Spehar
Director, Vice President and Chief Financial Officer
KNOW ALL MEN
BY THESE PRESENTS, that I, Edward A. Spehar, a Director, Vice President and Chief Financial Officer of Brighthouse Life Insurance Company, a Delaware company (the “Company”), do hereby constitute and appoint Michele H. Abate, Allie Lin,
and Alexander Ulianov, as my attorney-in-fact and agent, each of whom may act individually and none of whom is required to act jointly with any of the others, to sign
and file on my behalf and to execute and file any instrument or document required to be filed as part of or in connection with or in any way related to, the Registration Statements and any and all amendments thereto filed by the Company under the
Securities Act of 1933 and/or the Investment Company Act of 1940, pertaining to:
| • |
|
Brighthouse Fund UL for Variable Life Insurance (811-03927) |
File No. 002-88637 MarketLifeSM and
Invest
File No. 333-152219
MarketLifeSM
File No. 333-56952
Brighthouse Variable Survivorship Life II
File No. 333-69771 Brighthouse Variable
Survivorship Life
File No. 333-96515 and
333-96616 Brighthouse Variable Life Accumulator and Brighthouse Variable Life Accumulator - Series 2
File No. 333-96519 Brighthouse Variable Life
File No. 333-113109 Brighthouse Variable Life Accumulator - Series 3
File No. 333-152216 Portfolio Architect Life
File No. 333-152217 VintageLife
File No. 333-152219 MarketLife,
| • |
|
Brighthouse Fund UL III for Variable Life Insurance (811-09215)
|
File No. 333-71349 Corporate Owned VUL Series 1
File No. 333-94779 Corporate Owned VUL 2000 and Corporate Owned VUL III
File No. 333-105335 Corporate Select Policy
File No. 333-113533 Corporate Owned VUL IV,
| • |
|
Brighthouse Separate Account A (811-03365) |
File No. 333-200231 Series VA (offered between October 7, 2011 and May 1, 2016)
File No. 333-200232 Series S (offered between October 7, 2011 and May 1, 2016) and
Series S-L Share Option (offered between October 7, 2011 and May 1, 2016)
File No. 333-200233 Series VA-4 (offered between October 7, 2011 and May 1, 2016)
File No. 333-200234 Series O (offered between April 30, 2012 and July 19, 2015)
File No. 333-200236 Series L - 4 Year (offered on and after April 29, 2013)
File No. 333-200237 PrimElite IV
File No. 333-200238 Marquis Portfolios (offered on and after April 30, 2012)
File No. 333-200239 Brighthouse Growth and Income
File No. 333-200240 Group Flexible Payment Variable Annuity (Flexible Bonus/Retirement
Companion/Smart Choice)
File No. 333-200243 PrimElite III
File No. 333-200246 Brighthouse Simple SolutionsSM
File No. 333-200250 Marquis
Portfolios (offered between November 7, 2005 and April 30, 2012)
File
No. 333-200253 Series XC
File
No. 333-200256 Series VA (offered between March 22, 2001 and October 7, 2011)
File No. 333-200259 Series L and Series L - 4 Year (offered between November 22, 2004 and October 7, 2011)
File No. 333-200261 Series C (offered between September 4, 2001 and October 7,
2011)
File No. 333-200263 Series XTRA
File No. 333-200265 Series S and Series S-L Share
Option (offered between April 30, 2007 and October 7, 2011)
File No. 333-200268
Series L - 4 Year (offered between October 7, 2011 and April 28, 2013)
File
No. 333-200270 Group Annuity SF 101
File
No. 333-200272 Ultimate Annuity FSL 224
File
No. 333-200275 Foresight SF 137
File
No. 333-200277 SecurAnnuity (CLICO) 224/ SF 1700
File
No. 333-200278 Group VA SF 234 (Texas)
File
No. 333-200280 Sunshine SF 236 FL
File
No. 333-200281 Flexible Value SF 230
File No. 333-200282 Investors Choice
Annuity, Capital Strategist Annuity, Imprint Annuity and Strive Annuity
File
No. 333-200283 Protected Equity Portfolio (PEP)
File
No. 333-200284 Vintage L and Vintage XC
File
No. 333-200285 Series XTRA 6
File
No. 333-200286 Series VA - 4 (offered between May 1, 2011 and October 7, 2011)
File No. 333-200287 Series C (offered on and after October 7, 2011)
File No. 333-200288 Pioneer PRISM
File No. 333-200289 Pioneer PRISM L
File No. 333-200290 Pioneer PRISM XC
File No. 333-200323 Brighthouse Investment Portfolio ArchitectSM - Standard Version and Brighthouse Investment Portfolio ArchitectSM - C Share Option
File No. 333-203748 Series O (offered on and after July 20, 2015)
File No. 333-209053 Series VA (offered on and after May 2, 2016)
File No. 333-209054 Series VA- 4 (offered on and
after May 2, 2016)
File No. 333-209055 Series S (offered on and after May 2, 2016) and
Series S-L Share Option (offered on and after May 2, 2016)
File No. 333-209411 Brighthouse Prime Options,
| • |
|
Brighthouse Separate Account Eleven for Variable Annuities (811-21262) |
File Nos. 333-101778 and 333-152234 Pioneer AnnuiStar
Plus Annuity, Portfolio Architect Plus Annuity and Scudder Advocate Rewards Annuity
File
No. 333-152189 Universal Annuity
File
No. 333-152190 Universal Select Annuity
File
No. 333-152191 Universal Annuity Advantage
File Nos.
333-152192 and 333-152193 Brighthouse Retirement Account
File No. 333-152194 Gold Track and Gold Track Select
File Nos. 333-152197 and 333-152198 Brighthouse Access
Annuity and Brighthouse Access Select Annuity
File Nos. 333-152199 and 333-152200 Vintage Annuity
File Nos. 333-152201 and 333-152202 Index Annuity
File Nos. 333-152232 and 333-152233 Portfolio Architect Annuity, Portfolio Architect Select Annuity, Premier Advisers Annuity (Class I) and Premier Advisers Annuity (Class II)
File Nos. 333-152235 and 333-152236 Pioneer AnnuiStar
Annuity, Portfolio Architect II Annuity and Pioneer AnnuiStar Value Annuity
File Nos.
333-152237 and 333-152238 Premier Advisers II Annuity, Premier Advisers III (Series I)
and Premier Advisers III Annuity (Series II)
File Nos. 333-152239 and 333-152240 Premier Advisers
AssetManager Annuity, Premier Advisers L Annuity (Series I) and Premier Advisers L Annuity (Series II)
File Nos. 333-152255 and 333-152265 Vintage XTRA Annuity, Portfolio Architect XTRA Annuity and Vintage XTRA Annuity (Series II)
File Nos. 333-152256 and 333-152292 Vintage 3 Annuity,
Portfolio Architect 3 Annuity, Portfolio Architect L Annuity,
Vintage L Annuity and Pioneer AnnuiStar Flex Annuity
File Nos. 333-152258 and 333-152261 PrimElite Annuity
File Nos. 333-152259 and 333-152262 PrimElite II
Annuity
File Nos. 333-152260 and 333-152266
Protected Equity Portfolio Annuity
File Nos. 333-152263 and
333-152269 Marquis Portfolios
File Nos. 333-152264
and 333-152270 Vintage Access, Portfolio Architect Access, Scudder Advocate Advisor and Scudder Advocate Advisor - ST1 Annuity
File Nos. 333-152267 and 333-152268 Vintage II Annuity
and Vintage II Annuity (Series II)
File No. 333-197658 Brighthouse Accumulation
Annuity
File No. 333-208464 Brighthouse Premier Variable AnnuitySM,
| • |
|
Brighthouse Separate Account QPN for Variable Annuities |
File No. 333-156867 Unallocated Group Variable Annuity
File No. 333-156911 Brighthouse Retirement Perspectives,
| • |
|
Brighthouse Variable Annuity Account C (811-05200) |
File No. 333-200244 Class XC
File No. 333-200247 Class VA, Class AA and Class B
File No. 333-200249 Class L and Class L - 4 Year
File No. 333-200252 Class A
File No. 333-200255 COVA VA, Firstar Summit VA, Premier Advisor VA, Destiny Select VA and
Prevail VA
File No. 333-200258 COVA VA SPDA
File No. 333-200260 COVA Series A
File No. 333-200262 Navigator-Select/Custom-Select/Russell-Select
File No. 333-200264 Navigator-Select/Custom-Select/Russell-Select (CA)
File No. 333-200266 COVA VA and Premier Advisor (CA)
File No. 333-200267 COVA Series A (CA)
File No. 333-200269 Class C
File No. 333-200271 Class VA (CA), Class AA (CA), and Class B (CA)
File No. 333-200273 Class XC (CA)
File No. 333-200274 Class L (CA) and Class L - 4 Year (CA)
File No. 333-200276 Class A (CA)
File No. 333-200279 Class C (CA),
| • |
|
Brighthouse Variable Life Account A (811-21851) |
File No. 333-200241 Equity Advantage Variable Universal Life,
| • |
|
Brighthouse Variable Life Account One (811-07971) |
File No. 333-200242 Class VL
File No. 333-200245 Class VL (CA)
File No. 333-200248 Modified Single Premium Variable Life
File No. 333-200251 Custom Select and Russell Select Variable Life
File No. 333-200254 Modified Single Premium Variable Life (CA)
File No. 333-200257 Custom Select Variable Life,
| • |
|
Brighthouse Life Insurance Company (RILA MVA) |
File No. 333-282752 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay Plus® II Advisory Annuity
File No. 333-282871 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-283023 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-283024 Brighthouse
Shield® Level II 3-Year Annuity
File No. 333-290021 Fixed Account Annuity (Strategic Value Annuity)
File No. 333-290022 Gold Track and Registered Fixed Account Option and Gold Track Select
and Registered Fixed Account Option
File No. 333-290023 Brighthouse Retirement
Perspectives and Registered Fixed Account Option
File No. 333-290024 Unallocated Group
Variable Annuity and Registered Fixed Account Option
File No. 333-290025 Brighthouse
Retirement Account Annuity, Registered Fixed Account Option and Brighthouse Retirement Account Liquidity Benefit,
And pertaining to:
File No. 333-297104 Brighthouse SmartGuard Plus®
File No. 333-262390 Brighthouse
Shield® Level Pay PlusSM Annuity and Brighthouse Shield® Level Pay PlusSM Advisory Annuity
File
No. 333-226035 Brighthouse Shield® Level Select 6-Year Annuity v.3
File No. 333-233240 Brighthouse
Shield® Level 10 Advisory Annuity
File
No. 333-268427 Brighthouse Shield® Level Select Advisory Annuity
File No. 333-263492 Brighthouse
Shield® Level Select 6-Year Annuity
File No. 333-263495 Brighthouse
Shield® Level Select 3-Year Annuity
File No. 333-238213 Brighthouse
Shield® Level 10 Annuity
File
No. 333-208664 Brighthouse Shield Level Selector® Annuity
File No. 333-207091 Brighthouse Shield Level Selector® 3-Year Annuity
File No. 333-276468 Registered Fixed Account Option
File
No. 333-276469 Fixed Annuity (Strategic Value Annuity)
File No. 333-276470 Brighthouse Retirement Account Liquidity Benefit
File No. 333-276599 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-276762 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-276763 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay
Plus® II Advisory Annuity
File
No. 333-279302 Brighthouse Shield® Level II 3-Year Annuity
T-Mark Fixed Annuity
Target Maturity,
And new annuities and life
products such as:
Brighthouse Shield Annuity
Brighthouse Shield 3-Year Annuity
Brighthouse Shield 6-Year Annuity
Brighthouse Index-linked Life Insurance Policy,
and to have full power and authority to do or cause to be done in my name, place and stead each and every act and thing necessary or appropriate in order to effectuate
the same, as fully to all intents and purposes as I might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact or any of them, may do
or cause to be done by virtue hereof. This Power of Attorney does not revoke any prior powers of attorney.
IN WITNESS WHEREOF, I have hereunto set my hand this 6th
day of October 2026.
|
| /s/ Edward A. Spehar |
Edward A. Spehar |
Brighthouse Life Insurance Company
POWER OF ATTORNEY
Richard A. Cook
Vice President and Chief Accounting Officer
KNOW ALL MEN BY THESE
PRESENTS, that I, Richard A. Cook, Vice President and Chief Accounting Officer of Brighthouse Life Insurance Company, a Delaware company (the “Company”), do hereby constitute and appoint Michele H. Abate, Allie Lin, and Alexander
Ulianov, as my attorney-in-fact and agent, each of whom may act individually and none of whom is required to act jointly with any of the others, to sign and file on my
behalf and to execute and file any instrument or document required to be filed as part of or in connection with or in any way related to, the Registration Statements and any and all amendments thereto filed by the Company under the Securities Act of
1933 and/or the Investment Company Act of 1940, pertaining to:
| • |
|
Brighthouse Fund UL for Variable Life Insurance (811-03927) |
File No. 002-88637 MarketLifeSM and
Invest
File No. 333-152219
MarketLifeSM
File No. 333-56952
Brighthouse Variable Survivorship Life II
File No. 333-69771 Brighthouse Variable
Survivorship Life
File No. 333-96515 and 333-96616 Brighthouse
Variable Life Accumulator and Brighthouse Variable Life Accumulator - Series 2
File
No. 333-96519 Brighthouse Variable Life
File
No. 333-113109 Brighthouse Variable Life Accumulator - Series 3
File No. 333-152216 Portfolio Architect Life
File
No. 333-152217 VintageLife
File
No. 333-152219 MarketLife,
| • |
|
Brighthouse Fund UL III for Variable Life Insurance (811-09215)
|
File No. 333-71349 Corporate Owned VUL Series 1
File No. 333-94779 Corporate Owned VUL 2000 and Corporate Owned VUL III
File No. 333-105335 Corporate Select Policy
File No. 333-113533 Corporate Owned VUL IV,
| • |
|
Brighthouse Separate Account A (811-03365) |
File No. 333-200231 Series VA (offered between October 7, 2011 and May 1, 2016)
File No. 333-200232 Series S (offered between October 7, 2011 and May 1, 2016) and
Series S-L Share Option (offered between October 7, 2011 and May 1, 2016)
File No. 333-200233 Series VA-4 (offered between October 7, 2011 and May 1, 2016)
File No. 333-200234 Series O (offered between April 30, 2012 and July 19, 2015)
File No. 333-200236 Series L - 4 Year (offered on and after April 29, 2013)
File No. 333-200237 PrimElite IV
File No. 333-200238 Marquis Portfolios (offered on and after April 30, 2012)
File No. 333-200239 Brighthouse Growth and Income
File No. 333-200240 Group Flexible Payment Variable Annuity (Flexible Bonus/Retirement
Companion/Smart Choice)
File No. 333-200243 PrimElite III
File No. 333-200246 Brighthouse Simple SolutionsSM
File No. 333-200250 Marquis
Portfolios (offered between November 7, 2005 and April 30, 2012)
File
No. 333-200253 Series XC
File
No. 333-200256 Series VA (offered between March 22, 2001 and October 7, 2011)
File No. 333-200259 Series L and Series L - 4 Year (offered between November 22, 2004 and October 7, 2011)
File No. 333-200261 Series C (offered between September 4, 2001 and October 7,
2011)
File No. 333-200263 Series XTRA
File No. 333-200265 Series S and Series S-L Share
Option (offered between April 30, 2007 and October 7, 2011)
File No. 333-200268
Series L - 4 Year (offered between October 7, 2011 and April 28, 2013)
File
No. 333-200270 Group Annuity SF 101
File
No. 333-200272 Ultimate Annuity FSL 224
File
No. 333-200275 Foresight SF 137
File
No. 333-200277 SecurAnnuity (CLICO) 224/ SF 1700
File
No. 333-200278 Group VA SF 234 (Texas)
File
No. 333-200280 Sunshine SF 236 FL
File
No. 333-200281 Flexible Value SF 230
File No. 333-200282 Investors Choice
Annuity, Capital Strategist Annuity, Imprint Annuity and Strive Annuity
File
No. 333-200283 Protected Equity Portfolio (PEP)
File
No. 333-200284 Vintage L and Vintage XC
File
No. 333-200285 Series XTRA 6
File
No. 333-200286 Series VA - 4 (offered between May 1, 2011 and October 7, 2011)
File No. 333-200287 Series C (offered on and after October 7, 2011)
File No. 333-200288 Pioneer PRISM
File No. 333-200289 Pioneer PRISM L
File No. 333-200290 Pioneer PRISM XC
File No. 333-200323 Brighthouse Investment Portfolio ArchitectSM - Standard Version and Brighthouse Investment Portfolio ArchitectSM - C Share Option
File No. 333-203748 Series O (offered on and after July 20, 2015)
File No. 333-209053 Series VA (offered on and after May 2, 2016)
File No. 333-209054 Series VA- 4 (offered on and
after May 2, 2016)
File No. 333-209055 Series S (offered on and after May 2, 2016) and
Series S-L Share Option (offered on and after May 2, 2016)
File No. 333-209411 Brighthouse Prime Options,
| • |
|
Brighthouse Separate Account Eleven for Variable Annuities (811-21262) |
File Nos. 333-101778 and 333-152234 Pioneer AnnuiStar
Plus Annuity, Portfolio Architect Plus Annuity and Scudder Advocate Rewards Annuity
File
No. 333-152189 Universal Annuity
File
No. 333-152190 Universal Select Annuity
File
No. 333-152191 Universal Annuity Advantage
File Nos.
333-152192 and 333-152193 Brighthouse Retirement Account
File No. 333-152194 Gold Track and Gold Track Select
File Nos. 333-152197 and 333-152198 Brighthouse Access
Annuity and Brighthouse Access Select Annuity
File Nos. 333-152199 and 333-152200 Vintage Annuity
File Nos. 333-152201 and 333-152202 Index Annuity
File Nos. 333-152232 and 333-152233 Portfolio Architect Annuity, Portfolio Architect Select Annuity, Premier Advisers Annuity (Class I) and Premier Advisers Annuity (Class II)
File Nos. 333-152235 and 333-152236 Pioneer AnnuiStar
Annuity, Portfolio Architect II Annuity and Pioneer AnnuiStar Value Annuity
File Nos.
333-152237 and 333-152238 Premier Advisers II Annuity, Premier Advisers III (Series I) and Premier Advisers III Annuity (Series II)
File Nos. 333-152239 and 333-152240 Premier Advisers
AssetManager Annuity, Premier Advisers L Annuity (Series I) and Premier Advisers L Annuity (Series II)
File Nos. 333-152255 and 333-152265 Vintage XTRA Annuity, Portfolio Architect XTRA Annuity and Vintage XTRA Annuity (Series II)
File Nos. 333-152256 and 333-152292 Vintage 3 Annuity,
Portfolio Architect 3 Annuity, Portfolio Architect L Annuity, Vintage L Annuity and Pioneer AnnuiStar Flex Annuity
File Nos. 333-152258 and 333-152261 PrimElite Annuity
File Nos. 333-152259 and 333-152262 PrimElite II Annuity
File Nos. 333-152260 and 333-152266 Protected Equity Portfolio Annuity
File Nos. 333-152263 and 333-152269 Marquis Portfolios
File Nos. 333-152264 and 333-152270 Vintage Access,
Portfolio Architect Access, Scudder Advocate Advisor and Scudder Advocate Advisor - ST1 Annuity
File Nos. 333-152267 and 333-152268 Vintage II Annuity and Vintage II Annuity (Series II)
File No. 333-197658 Brighthouse Accumulation Annuity
File No. 333-208464 Brighthouse Premier Variable AnnuitySM,
| • |
|
Brighthouse Separate Account QPN for Variable Annuities |
File No. 333-156867 Unallocated Group Variable Annuity
File No. 333-156911 Brighthouse Retirement Perspectives,
| • |
|
Brighthouse Variable Annuity Account C (811-05200) |
File No. 333-200244 Class XC
File No. 333-200247 Class VA, Class AA and Class B
File No. 333-200249 Class L and Class L - 4 Year
File No. 333-200252 Class A
File No. 333-200255 COVA VA, Firstar Summit VA, Premier Advisor VA, Destiny Select VA and
Prevail VA
File No. 333-200258 COVA VA SPDA
File No. 333-200260 COVA Series A
File No. 333-200262 Navigator-Select/Custom-Select/Russell-Select
File No. 333-200264 Navigator-Select/Custom-Select/Russell-Select (CA)
File No. 333-200266 COVA VA and Premier Advisor (CA)
File No. 333-200267 COVA Series A (CA)
File No. 333-200269 Class C
File No. 333-200271 Class VA (CA), Class AA (CA), and Class B (CA)
File No. 333-200273 Class XC (CA)
File No. 333-200274 Class L (CA) and Class L - 4 Year (CA)
File No. 333-200276 Class A (CA)
File No. 333-200279 Class C (CA),
| • |
|
Brighthouse Variable Life Account A (811-21851) |
File No. 333-200241 Equity Advantage Variable Universal Life,
| • |
|
Brighthouse Variable Life Account One (811-07971) |
File No. 333-200242 Class VL
File No. 333-200245 Class VL (CA)
File No. 333-200248 Modified Single Premium Variable Life
File No. 333-200251 Custom Select and Russell Select Variable Life
File No. 333-200254 Modified Single Premium Variable Life (CA)
File No. 333-200257 Custom Select Variable Life,
| • |
|
Brighthouse Life Insurance Company (RILA MVA) |
File No. 333-282752 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay Plus® II Advisory Annuity
File No. 333-282871 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-283023 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-283024 Brighthouse
Shield® Level II 3-Year Annuity
File No. 333-290021 Fixed Account Annuity (Strategic Value Annuity)
File No. 333-290022 Gold Track and Registered Fixed Account Option and Gold Track Select
and Registered Fixed Account Option
File No. 333-290023 Brighthouse Retirement
Perspectives and Registered Fixed Account Option
File No. 333-290024 Unallocated Group
Variable Annuity and Registered Fixed Account Option
File No. 333-290025 Brighthouse
Retirement Account Annuity, Registered Fixed Account Option and Brighthouse Retirement Account Liquidity Benefit,
And pertaining to:
File No. 333-297104 Brighthouse SmartGuard Plus®
File No. 333-262390 Brighthouse
Shield® Level Pay PlusSM Annuity and Brighthouse Shield® Level Pay PlusSM Advisory Annuity
File
No. 333-226035 Brighthouse Shield® Level Select 6-Year Annuity v.3
File No. 333-233240 Brighthouse
Shield® Level 10 Advisory Annuity
File
No. 333-268427 Brighthouse Shield® Level Select Advisory Annuity
File No. 333-263492 Brighthouse
Shield® Level Select 6-Year Annuity
File No. 333-263495 Brighthouse
Shield® Level Select 3-Year Annuity
File No. 333-238213 Brighthouse
Shield® Level 10 Annuity
File
No. 333-208664 Brighthouse Shield Level Selector® Annuity
File No. 333-207091 Brighthouse Shield Level Selector® 3-Year Annuity
File No. 333-276468 Registered Fixed Account Option
File
No. 333-276469 Fixed Annuity (Strategic Value Annuity)
File No. 333-276470 Brighthouse Retirement Account Liquidity Benefit
File No. 333-276599 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-276762 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-276763 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay
Plus® II Advisory Annuity
File
No. 333-279302 Brighthouse Shield® Level II 3-Year Annuity
T-Mark Fixed Annuity
Target Maturity,
And new annuities and life
products such as:
Brighthouse Shield Annuity
Brighthouse Shield 3-Year Annuity
Brighthouse Shield 6-Year Annuity
Brighthouse Index-linked Life Insurance Policy,
and to have full power and authority to do or cause to be done in my name, place and stead each and every act and thing necessary or appropriate in order to effectuate
the same, as fully to all intents and purposes as I might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact or any of them, may do
or cause to be done by virtue hereof. This Power of Attorney does not revoke any prior powers of attorney.
IN WITNESS WHEREOF, I have hereunto set my hand this 6th
day of October 2026.
|
| /s/ Richard A. Cook |
| Richard A. Cook |
Brighthouse Life Insurance Company
POWER OF ATTORNEY
Gianna H. Figaro-Sterling
Vice President and Controller
KNOW ALL MEN BY THESE PRESENTS, that
I, Gianna H. Figaro-Sterling, Vice President and Controller of Brighthouse Life Insurance Company, a Delaware company (the “Company”), do hereby constitute and appoint Michele H. Abate, Allie Lin, and Alexander Ulianov, as my attorney-in-fact and agent, each of whom may act individually and none of whom is required to act jointly with any of the others, to sign and file on my behalf and to execute
and file any instrument or document required to be filed as part of or in connection with or in any way related to, the Registration Statements and any and all amendments thereto filed by the Company under the Securities Act of 1933 and/or the
Investment Company Act of 1940, pertaining to:
| • |
|
Brighthouse Fund UL for Variable Life Insurance (811-03927) |
File No. 002-88637 MarketLifeSM and
Invest
File No. 333-152219
MarketLifeSM
File No. 333-56952
Brighthouse Variable Survivorship Life II
File No. 333-69771 Brighthouse Variable
Survivorship Life
File No. 333-96515 and
333-96616 Brighthouse Variable Life Accumulator and Brighthouse Variable Life Accumulator - Series 2
File No. 333-96519 Brighthouse Variable Life
File No. 333-113109 Brighthouse Variable Life Accumulator - Series 3
File No. 333-152216 Portfolio Architect Life
File No. 333-152217 VintageLife
File No. 333-152219 MarketLife,
| • |
|
Brighthouse Fund UL III for Variable Life Insurance (811-09215)
|
File No. 333-71349 Corporate Owned VUL Series 1
File No. 333-94779 Corporate Owned VUL 2000 and Corporate Owned VUL III
File No. 333-105335 Corporate Select Policy
File No. 333-113533 Corporate Owned VUL IV,
| • |
|
Brighthouse Separate Account A (811-03365) |
File No. 333-200231 Series VA (offered between October 7, 2011 and May 1, 2016)
File No. 333-200232 Series S (offered between October 7, 2011 and May 1, 2016) and
Series S-L Share Option (offered between October 7, 2011 and May 1, 2016)
File No. 333-200233 Series VA-4 (offered between October 7, 2011 and May 1, 2016)
File No. 333-200234 Series O (offered between April 30, 2012 and July 19, 2015)
File No. 333-200236 Series L - 4 Year (offered on and after April 29, 2013)
File No. 333-200237 PrimElite IV
File No. 333-200238 Marquis Portfolios (offered on and after April 30, 2012)
File No. 333-200239 Brighthouse Growth and Income
File No. 333-200240 Group Flexible Payment Variable Annuity (Flexible Bonus/Retirement
Companion/Smart Choice)
File No. 333-200243 PrimElite III
File No. 333-200246 Brighthouse Simple SolutionsSM
File No. 333-200250 Marquis
Portfolios (offered between November 7, 2005 and April 30, 2012)
File
No. 333-200253 Series XC
File
No. 333-200256 Series VA (offered between March 22, 2001 and October 7, 2011)
File No. 333-200259 Series L and Series L - 4 Year (offered between November 22, 2004 and October 7, 2011)
File No. 333-200261 Series C (offered between September 4, 2001 and October 7,
2011)
File No. 333-200263 Series XTRA
File No. 333-200265 Series S and Series S-L Share
Option (offered between April 30, 2007 and October 7, 2011)
File No. 333-200268
Series L - 4 Year (offered between October 7, 2011 and April 28, 2013)
File
No. 333-200270 Group Annuity SF 101
File
No. 333-200272 Ultimate Annuity FSL 224
File
No. 333-200275 Foresight SF 137
File
No. 333-200277 SecurAnnuity (CLICO) 224/ SF 1700
File
No. 333-200278 Group VA SF 234 (Texas)
File
No. 333-200280 Sunshine SF 236 FL
File
No. 333-200281 Flexible Value SF 230
File No. 333-200282 Investors Choice
Annuity, Capital Strategist Annuity, Imprint Annuity and Strive Annuity
File
No. 333-200283 Protected Equity Portfolio (PEP)
File
No. 333-200284 Vintage L and Vintage XC
File
No. 333-200285 Series XTRA 6
File
No. 333-200286 Series VA - 4 (offered between May 1, 2011 and October 7, 2011)
File No. 333-200287 Series C (offered on and after October 7, 2011)
File No. 333-200288 Pioneer PRISM
File No. 333-200289 Pioneer PRISM L
File No. 333-200290 Pioneer PRISM XC
File No. 333-200323 Brighthouse Investment Portfolio ArchitectSM - Standard Version and Brighthouse Investment Portfolio ArchitectSM - C Share Option
File No. 333-203748 Series O (offered on and after July 20, 2015)
File No. 333-209053 Series VA (offered on and after May 2, 2016)
File No. 333-209054 Series VA- 4 (offered on and
after May 2, 2016)
File No. 333-209055 Series S (offered on and after May 2, 2016) and
Series S-L Share Option (offered on and after May 2, 2016)
File No. 333-209411 Brighthouse Prime Options,
| • |
|
Brighthouse Separate Account Eleven for Variable Annuities (811-21262) |
File Nos. 333-101778 and 333-152234 Pioneer AnnuiStar
Plus Annuity, Portfolio Architect Plus Annuity and Scudder Advocate Rewards Annuity
File
No. 333-152189 Universal Annuity
File
No. 333-152190 Universal Select Annuity
File
No. 333-152191 Universal Annuity Advantage
File Nos.
333-152192 and 333-152193 Brighthouse Retirement Account
File No. 333-152194 Gold Track and Gold Track Select
File Nos. 333-152197 and 333-152198 Brighthouse Access
Annuity and Brighthouse Access Select Annuity
File Nos. 333-152199 and 333-152200 Vintage Annuity
File Nos. 333-152201 and 333-152202 Index Annuity
File Nos. 333-152232 and 333-152233 Portfolio Architect Annuity, Portfolio Architect Select Annuity, Premier Advisers Annuity (Class I) and Premier Advisers Annuity (Class II)
File Nos. 333-152235 and 333-152236 Pioneer AnnuiStar
Annuity, Portfolio Architect II Annuity and Pioneer AnnuiStar Value Annuity
File Nos.
333-152237 and 333-152238 Premier Advisers II Annuity, Premier Advisers III (Series I) and Premier Advisers III Annuity (Series II)
File Nos. 333-152239 and 333-152240 Premier Advisers
AssetManager Annuity, Premier Advisers L Annuity (Series I) and Premier Advisers L Annuity (Series II)
File Nos. 333-152255 and 333-152265 Vintage XTRA Annuity, Portfolio Architect XTRA Annuity and Vintage XTRA Annuity (Series II)
File Nos. 333-152256 and 333-152292 Vintage 3 Annuity,
Portfolio Architect 3 Annuity, Portfolio Architect L Annuity, Vintage L Annuity and Pioneer AnnuiStar Flex Annuity
File Nos. 333-152258 and 333-152261 PrimElite Annuity
File Nos. 333-152259 and 333-152262 PrimElite II Annuity
File Nos. 333-152260 and 333-152266 Protected Equity Portfolio Annuity
File Nos. 333-152263 and 333-152269 Marquis Portfolios
File Nos. 333-152264 and 333-152270 Vintage Access,
Portfolio Architect Access, Scudder Advocate Advisor and Scudder Advocate Advisor - ST1 Annuity
File Nos. 333-152267 and 333-152268 Vintage II Annuity and Vintage II Annuity (Series II)
File No. 333-197658 Brighthouse Accumulation Annuity
File No. 333-208464 Brighthouse Premier Variable AnnuitySM,
| • |
|
Brighthouse Separate Account QPN for Variable Annuities |
File No. 333-156867 Unallocated Group Variable Annuity
File No. 333-156911 Brighthouse Retirement Perspectives,
| • |
|
Brighthouse Variable Annuity Account C (811-05200) |
File No. 333-200244 Class XC
File No. 333-200247 Class VA, Class AA and Class B
File No. 333-200249 Class L and Class L - 4 Year
File No. 333-200252 Class A
File No. 333-200255 COVA VA, Firstar Summit VA, Premier Advisor VA, Destiny Select VA and
Prevail VA
File No. 333-200258 COVA VA SPDA
File No. 333-200260 COVA Series A
File No. 333-200262 Navigator-Select/Custom-Select/Russell-Select
File No. 333-200264 Navigator-Select/Custom-Select/Russell-Select (CA)
File No. 333-200266 COVA VA and Premier Advisor (CA)
File No. 333-200267 COVA Series A (CA)
File No. 333-200269 Class C
File No. 333-200271 Class VA (CA), Class AA (CA), and Class B (CA)
File No. 333-200273 Class XC (CA)
File No. 333-200274 Class L (CA) and Class L - 4 Year (CA)
File No. 333-200276 Class A (CA)
File No. 333-200279 Class C (CA),
| • |
|
Brighthouse Variable Life Account A (811-21851) |
File No. 333-200241 Equity Advantage Variable Universal Life,
| • |
|
Brighthouse Variable Life Account One (811-07971) |
File No. 333-200242 Class VL
File No. 333-200245 Class VL (CA)
File No. 333-200248 Modified Single Premium Variable Life
File No. 333-200251 Custom Select and Russell Select Variable Life
File No. 333-200254 Modified Single Premium Variable Life (CA)
File No. 333-200257 Custom Select Variable Life,
| • |
|
Brighthouse Life Insurance Company (RILA MVA) |
File No. 333-282752 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay Plus® II Advisory Annuity
File No. 333-282871 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-283023 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-283024 Brighthouse
Shield® Level II 3-Year Annuity
File No. 333-290021 Fixed Account Annuity (Strategic Value Annuity)
File No. 333-290022 Gold Track and Registered Fixed Account Option and Gold Track Select
and Registered Fixed Account Option
File No. 333-290023 Brighthouse Retirement
Perspectives and Registered Fixed Account Option
File No. 333-290024 Unallocated Group
Variable Annuity and Registered Fixed Account Option
File No. 333-290025 Brighthouse
Retirement Account Annuity, Registered Fixed Account Option and Brighthouse Retirement Account Liquidity Benefit,
And pertaining to:
File No. 333-297104 Brighthouse SmartGuard Plus®
File No. 333-262390 Brighthouse
Shield® Level Pay PlusSM Annuity and Brighthouse Shield® Level Pay PlusSM Advisory Annuity
File
No. 333-226035 Brighthouse Shield® Level Select 6-Year Annuity v.3
File No. 333-233240 Brighthouse
Shield® Level 10 Advisory Annuity
File
No. 333-268427 Brighthouse Shield® Level Select Advisory Annuity
File No. 333-263492 Brighthouse
Shield® Level Select 6-Year Annuity
File No. 333-263495 Brighthouse
Shield® Level Select 3-Year Annuity
File No. 333-238213 Brighthouse
Shield® Level 10 Annuity
File
No. 333-208664 Brighthouse Shield Level Selector® Annuity
File No. 333-207091 Brighthouse Shield Level Selector® 3-Year Annuity
File No. 333-276468 Registered Fixed Account Option
File
No. 333-276469 Fixed Annuity (Strategic Value Annuity)
File No. 333-276470 Brighthouse Retirement Account Liquidity Benefit
File No. 333-276599 Brighthouse Shield® Level II 6-Year Annuity
File No. 333-276762 Brighthouse
Shield® Level II Advisory Annuity
File
No. 333-276763 Brighthouse Shield Level Pay Plus® II Annuity and Brighthouse Shield Level Pay
Plus® II Advisory Annuity
File
No. 333-279302 Brighthouse Shield® Level II 3-Year Annuity
T-Mark Fixed Annuity
Target Maturity,
And new annuities and life
products such as:
Brighthouse Shield Annuity
Brighthouse Shield 3-Year Annuity
Brighthouse Shield 6-Year Annuity
Brighthouse Index-linked Life Insurance Policy,
and to have full power and authority to do or cause to be done in my name, place and stead each and every act and thing necessary or appropriate in order to effectuate
the same, as fully to all intents and purposes as I might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact or any of them, may do
or cause to be done by virtue hereof. This Power of Attorney does not revoke any prior powers of attorney.
IN WITNESS WHEREOF, I have hereunto set my hand this 6th
day of October 2026.
|
| /s/ Gianna H. Figaro-Sterling |
| Gianna H. Figaro-Sterling |
EX-FILING FEES
S-3 S-3/A EX-FILING FEES 333-297104 0000733076 BRIGHTHOUSE LIFE INSURANCE Co N/A N/A 0000733076 2026-10-13 2026-10-13 0000733076 1 2026-10-13 2026-10-13 0000733076 2 2026-10-13 2026-10-13 0000733076 3 2026-10-13 2026-10-13 iso4217:USD xbrli:pure xbrli:shares
| Calculation of Filing Fee Tables |
| S-3 |
| BRIGHTHOUSE LIFE INSURANCE Co |
| Table 1: Newly Registered and Carry Forward Securities |
☐Not Applicable |
|
|
|
Security Type |
Security Class Title |
Fee Calculation or Carry Forward Rule |
Amount Registered |
Proposed Maximum Offering Price Per Unit |
Maximum Aggregate Offering Price |
Fee Rate |
Amount of Registration Fee |
Carry Forward Form Type |
Carry Forward File Number |
Carry Forward Initial Effective Date |
Filing Fee Previously Paid in Connection with Unsold Securities to be Carried Forward |
| Newly Registered Securities |
| Fees to be Paid |
|
Other |
Flexible Adjustable Life Insurance Policy |
457(o) |
0 |
|
$ 0.00 |
0.000087 |
$ 0.00 |
|
|
|
|
| Fees Previously Paid |
|
Other |
Flexible Adjustable Life Insurance Policy |
457(o) |
0 |
|
$ 0.00 |
|
$ 0.00 |
|
|
|
|
| Carry Forward Securities |
| Carry Forward Securities |
1 |
Other |
Flexible Adjustable Life Insurance Policy |
415(a)(6) |
0 |
|
$ 445,247,207.50 |
|
|
S-3 |
333-268618 |
07/13/2023 |
$ 49,066.24 |
|
|
|
|
Total Offering Amounts: |
|
$ 445,247,207.50 |
|
$ 0.00 |
|
|
|
|
|
|
|
|
Total Fees Previously Paid: |
|
|
|
$ 0.00 |
|
|
|
|
|
|
|
|
Total Fee Offsets: |
|
|
|
$ 0.00 |
|
|
|
|
|
|
|
|
Net Fee Due: |
|
|
|
$ 0.00 |
|
|
|
|
| 1 |
(1) The Amount Registered and the Proposed Maximum Offering Price Per Unit are not applicable because the securities are not issued in predetermined amounts or units. (2) Approximately $445,247,207.50 of unsold securities previously registered in the Registration Statement on Form S-3, File No. 333-268618 ("Prior Registration Statement"), are hereby carried forward to this Registration Statement on Form S-3. In accordance with Rule 415(a)(6), the offering of securities under the Prior Registration Statement will be deemed terminated as of the Effective Date of this Registration Statement. |
|
| Table 2: Fee Offset Claims and Sources |
☑Not Applicable |
|
|
|
Registrant or Filer Name |
Form or Filing Type |
File Number |
Initial Filing Date |
Filing Date |
Fee Offset Claimed |
Security Type Associated with Fee Offset Claimed |
Security Title Associated with Fee Offset Claimed |
Unsold Securities Associated with Fee Offset Claimed |
Unsold Aggregate Offering Amount Associated with Fee Offset Claimed |
Fee Paid with Fee Offset Source |
| Rules 457(b) and 0-11(a)(2) |
| Fee Offset Claims |
|
|
|
|
|
|
|
|
|
|
|
|
| Fee Offset Sources |
|
|
|
|
|
|
|
|
|
|
|
|
| Rule 457(p) |
| Fee Offset Claims |
|
|
|
|
|
|
|
|
|
|
|
|
| Fee Offset Sources |
|
|
|
|
|
|
|
|
|
|
|
|
| Table 3: Combined Prospectuses |
☑Not Applicable |
|
|
Security Type |
Security Class Title |
Amount of Securities Previously Registered |
Maximum Aggregate Offering Price of Securities Previously Registered |
Form Type |
File Number |
Initial Effective Date |
| |
|
|
|
|
|
|
|